OverWise

Market regime, October 26

Top five drivers, the risk matrix and the book for Monday, October 26, 2026.

Not a flip. Score 43 of 100. The label is NEUTRAL. Yesterday the score was 43. The label was already NEUTRAL. The line for CAUTION is 45. The line for RISK-ON is 30. The line for RISK-OFF is 61. The score did not move. It is 2 points under the CAUTION line.

Read the five drivers
Before the US open Next review 27 Oct 2026 (Tue)

Regime score

43of 100

NEUTRAL

2 under CAUTION, 13 over the RISK-ON line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

This is a Monday edition before the US open. Friday is the last completed US session. US cash opens later today. The weekend did not print a new US close. What did move is the wording out of the Gulf and the price of oil in Asian trade.

The book versus Friday is close to the same book. Hold the crude sleeve. Do not add it on strike talk. Do not sell it on deal talk. Do not buy the technology dip before the earnings prints. Do not cover the long bond before Wednesday.

Three things land in the next three sessions. The policy decision is Wednesday. September personal income and outlays is Thursday. Microsoft and Alphabet report Wednesday, Amazon on Thursday. The week is an event week, not a trend week.

In short

MARKET REGIME, Oct 26 (Mon)

Signal. Neutral. Hold energy. Do not add. Score 43 of 100.

  1. Iran Iran talks go on. No deal, no strike yet.
  2. United States Fed holds Wednesday. December hike still live.
  3. United States Inflation 3.7 percent. Fuel is the whole story.
  4. Gold had its worst week in months.
  5. United States Big tech reports midweek into a weak tape.

Markets bar

Friday is the last completed US session. Equity, yield and fund rows are that close. Oil rows name the settlement. The Asian session on Monday moved oil lower, and that move is described in words, not in a new number.

This note does not cite oil volume. Friday's volume on this feed for Brent, crude and gold equals Thursday's volume. That is a copied print. It is not a thin print, and it is not a settlement volume. A separate Sunday evening screen shows the Brent continuous contract about seven dollars lower than Friday's settlement. That is a contract roll, not a fall in the front month. Do not trade it as a new settlement.

Asset Level Change
S&P 500 (Fri close)7,623.68Down 39.75 points, or 0.52 percent, vs Thursday's 7,663.43. This feed. Fell on the week
Nasdaq Composite (Fri close)25,955.34Down 53.52 points, or 0.21 percent, vs Thursday's 26,008.86. This feed
Dow (Fri close)52,215.16Down 652.82 points, or 1.23 percent, vs Thursday's 52,867.98. Close story. This feed matches
VIX (Fri close, this feed)19.45Up 0.42 points vs Thursday's 19.03. The close is under 20
US 10-year yield index (Fri close)4.988%Up 3.5 basis points vs Thursday's 4.953. This is the index in the score. Not the cash yield
5-year yield index (Fri close)4.805%Up 3.7 basis points vs Thursday's 4.768. Not the cash yield
30-year yield index (Fri close)5.315%Up 2.8 basis points vs Thursday's 5.287. Down 12 basis points on the week. Not the cash yield
Cash 10-year (Fri close story)4.99%The close story said 4.99 percent. Do not average 4.99 and 4.988
Brent (Fri settlement)116.72 dollarsUp 3.55 dollars, or 3.14 percent, from Thursday's 113.17. Highest settlement since April in the settlement story. This feed agrees. Eased in Asian trade on Monday
WTI (Fri settlement)103.27 dollarsUp 3.80 dollars, or 3.8 percent, from Thursday's 99.47. This feed's crude close agrees. Do not print a second price
December gold (Fri close, this feed)4,007.90 dollarsDown 1.3 percent vs Thursday's 4,060.40. Low of the session was 3,989.10. Down 4.1 percent on the week from 4,181.10 on 16 Oct
Gold fund (Fri close)366.61Down 0.6 percent vs Thursday's 369.00. Down 4.0 percent on the week. Not a futures settlement
Dollar index (Fri close, this feed)101.81Up 0.2 percent vs Thursday's 101.61. Flat on the week
Energy sector fund (Fri close)69.33Up 2.6 percent vs Thursday's 67.57. Up 1.6 percent on the week
Oil fund (Fri close, this feed)169.53Up 4.3 percent vs Thursday's 162.51. Up 4.8 percent on the week
Semiconductor fund (Fri close)527.20Up 0.7 percent vs Thursday's 523.35. Down 2.3 percent on the week
Long bond fund (Fri close)81.34Down 0.5 percent vs Thursday's 81.74. Up 1.6 percent on the week
Defense fund (Fri close)202.23Down 1.1 percent vs Thursday's 204.48. Down 3.3 percent on the week
China fund (Fri close)32.31Down 0.4 percent vs Thursday's 32.45. Down 4.5 percent on the week
A refinery lit at night across still water, snow falling
Preemraff refinery at Brofjorden, Sweden, at night. Picture: W.carter, CC0, via Wikimedia Commons.

Top five drivers

Iran Iran Talks Continue

Oil Eased on the Headline, Not on a Deal.

SignalOver the weekend Iran said messages are still being passed to Washington through mediators, and the Qatari channel pressed for a deal. Iran denied it had offered a plan to reopen the strait through Pakistan, and said any agreement would not open the waterway by itself. Trump said it is decision time on Iran and that new strikes remain possible. Oil slipped in Asian trade on Monday from Friday's six-month high, on the prospect of a deal.

Macro ImpactThe strait is not open. A denial is not a deal, and a headline is not a settlement. Friday's Brent settlement of 116.72 dollars still sets the energy input into the inflation data, and the International Energy Agency says Saudi supply has fallen to its lowest in more than three decades after the Houthi attacks. This is genuinely two-sided inside one week. A deal takes a large slice off crude. A strike takes it higher than Friday. The error is to trade either side as if it were decided, because the tape will pay you for being early on one and stop you out on the other.

PositioningHold the crude sleeve. Do not add it on the strike talk. Do not sell it on the deal talk. No airlines and no transports until there is a ship count or an opening. Keep the energy equity weight and do not chase Friday's high.

Key SourcesABC News, 25 Oct, "Iran says messages are still being passed to the US amid war concerns"; Iran International, 25 Oct, "Qatar pushes for Iran deal, new US strikes remain possible"; Hindustan Times, 26 Oct, "Make a deal or finish them off"; Reuters, 25 Oct, "Oil slips from near six-months highs despite supply concerns".

A tanker at anchor off an arid Gulf coast, haze over the water
A tanker off Mina Al Fahal, Oman. Picture: Wusel007, CC BY-SA 3.0, via Wikimedia Commons.

United States The Fed Meets Wednesday

A Hold First, Then a December Rise.

SignalThe policy meeting runs Tuesday and Wednesday, and the decision lands Wednesday. The consensus in the weekend coverage is a hold with language that keeps a December rise on the table. ING titled its preview "a pause before a December hike". The meeting carries no new projections.

Macro ImpactThe hold itself is priced and should not move much. The risk sits in the statement and the press conference. With September consumer prices at 3.7 percent and weekly claims near a 57-year low, there is no domestic reason to sound soft. A hawkish hold keeps the 10-year index near 5 percent, keeps the front end anchored high, and keeps the duration short paid. A surprise softening is the tail that would break that.

PositioningStay underweight long duration. Do not cover before Wednesday. Do not add to the short either, into a two-way event with a statement risk on both sides. Hold cash and short bills over the long end.

Key SourcesING, 24 Oct, "Federal Reserve preview: A pause before a December hike"; Yahoo Finance, 25 Oct, "Fed expected to hold rates steady this week despite hot inflation but signal they're not done hiking"; BNN Bloomberg, 25 Oct, "Fed expected to hold rates steady days ahead of U.S. midterms"; Federal Reserve meeting calendar.

United States Inflation Is an Energy Story

September PCE Lands Thursday.

SignalSeptember consumer prices rose 3.7 percent from a year earlier. The statistics agency put gasoline up 34.2 percent over the year ended September. August core PCE was 3.0 percent. September personal income and outlays, with the first read on third quarter output, both land Thursday morning.

Macro ImpactThe energy shock is doing the work on the headline. Core sits near 3 and the headline near 3.7, and the gap is fuel. That is the mechanism that stops the Fed from easing even with a war running and a soft equity tape. Thursday decides whether the market's December lean survives the week. A core print at or above 3 keeps the front end offered and keeps the dollar bid. A softer core is the one print that could take the hike back out.

PositioningNo duration add ahead of Thursday. Own the energy cash flows rather than the consumer. Keep consumer discretionary light into a fuel bill this high.

Key SourcesBureau of Labor Statistics, "Prices for gasoline increased 34.2 percent over the year ended September 2026"; CNBC, "Consumer prices rose 3.7% annually in September as gas prices skyrocket"; Reuters, "US inflation heats up in September; Fed rate hike this month back on table"; BEA release schedule, 29 Oct.

Gold Broke 4,000

Higher Oil Is Now a Rates Trade.

SignalDecember gold closed at 4,007.90 dollars on Friday, down 1.3 percent on the day. It traded under its 4,000 dollar mark during the session, with a low of 3,989.10. On the week it fell 4.1 percent. Coverage split between calling it the worst week in four months and the worst in five. The gold fund fell 4.0 percent on the week.

Macro ImpactGold is trading as the anti-Fed asset, not the haven. When crude rises, hike odds rise, real yields rise, and gold falls. That is the tell this week, and it is the same mechanism as the duration short. It also means gold is currently not hedging the war. A book that owns gold for Iran risk is not hedged against Iran risk, and that is worth knowing before a week with a strike option in it.

PositioningNo new gold entry. A zero weight is fine. If you want the war hedge, the crude sleeve is doing that job this month. Do not average down into a rate-driven fall.

Key SourcesCNBC, 23 Oct, "Gold set for steep weekly loss as rising oil prices bolster Fed rate hike bets"; Reuters, 23 Oct, same theme; FXStreet, 23 Oct, "Gold declines below $4,000 as higher oil prices reinforce Fed rate-hike expectations".

United States Three Mega Caps Report Midweek Into a Technology-Led Slide

SignalMicrosoft and Alphabet report Wednesday after the close. Amazon, Intel and Eli Lilly report Thursday. The S&P 500 fell 0.52 percent on Friday and fell on the week, led by technology. The Nasdaq fell 0.21 percent. The semiconductor fund is down 2.3 percent on the week. AI spending doubt runs through the coverage.

Macro ImpactThe artificial intelligence capital spending number is now a macro input, not a stock story. If the three raise guidance, that is more debt issuance, more power demand and more inflation pressure at the long end. If they trim it, that is the growth scare the bond market has been quietly waiting for. Either outcome resolves the narrative leg of the score, which is currently the calmest part of it at 9.

PositioningKeep semis underweight. Do not buy the dip before the prints. No new high-beta technology. Utilities remain the cleaner way to own the power demand.

Key SourcesCNBC, "Earnings playbook: Alphabet, Microsoft, Amazon and more report this week"; Yahoo Finance, "What To Expect In Markets This Week: GOOGL, MSFT, AMZN, INTC, HOOD, LLY Earnings, Fed Meeting And More"; Forbes, "Alphabet, Microsoft And Amazon Lead The Busiest Week Of Earnings Season".

Risk matrix

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreStill NEUTRALHighDays↔ 43, from 43. Did not cross 45. Did not cross 30. CAUTION is 45. RISK-ON is 30. RISK-OFF is 61
Iran talksLive, unresolvedHighDays↗ Iran said messages are still being passed through mediators. Qatar pressed for a deal. Iran denied offering one. A denial is not a close
Strike riskOpen, not orderedHighDays↔ Trump said it is decision time and new strikes remain possible. No confirmed new US strike in this note. A comment is not an order
HormuzNot openHighDays↔ Iran said any deal would not open the waterway by itself. No ship count, no opening. The 22 Oct tanker damage count is four days old, not overnight news
Brent settlementFriday's book standsHighDays↔ Settled at 116.72 dollars on Friday, up 3.14 percent. Highest since April in the settlement story. Eased in Asian trade on Monday on deal talk. A headline is not a settlement
WTI settlementFriday's book standsHighDays↔ Settled at 103.27 dollars on Friday, up 3.8 percent. This feed agrees. Do not print a second price
Oil contract rollDo not trade itHighDays↗ The Sunday screen shows the Brent continuous about seven dollars under Friday's settlement. That is a roll into the next month, not a front month fall. Do not average the two
Physical supplyTight on the Gulf sideMedium1 to 3 mo↗ The International Energy Agency said Saudi supply is at its lowest in more than three decades after the Houthi attacks. Supply risk is real, not only rhetoric
S&P 500Friday drop standsHighDays↔ Down 0.52 percent on Friday, to 7,623.68. Fell on the week. Do not buy the dip into the prints
NasdaqEased, not repairedHighDays↔ Down 0.21 percent on Friday, to 25,955.34. Technology led the weekly decline
SemisStill under pressureHighDays↔ The semiconductor fund is down 2.3 percent on the week, up 0.7 percent on Friday. Do not average
Fed pathHold Wednesday, rise risk in DecemberHigh1 to 3 mo↔ Weekend coverage expects a hold and keeps a December rise on the table. ING calls it a pause before a December hike. A cut is not the base
US 10-year indexFriday bounce standsHigh1 to 3 mo↔ Closed at 4.988 percent on Friday, up 3.5 basis points. Down on the week. Do not average the cash story's 4.99
5-year indexFriday bounce standsHigh1 to 3 mo↔ Closed at 4.805 percent on Friday, up 3.7 basis points
30-year indexLong end eased on the weekMedium1 to 3 mo↘ Closed at 5.315 percent on Friday, down 12 basis points on the week. A curve move, not a bond buy
US inflationSeptember already printed, PCE ThursdayHigh1 to 3 mo↔ Headline 3.7 percent. Gasoline up 34.2 percent over the year. August core was 3.0 percent. September personal income and outlays lands Thursday
US laborTight, no new printHigh1 to 3 mo↔ Weekly claims near a 57-year low in last week's coverage, at 194,000. No new print before Thursday. A tight labor market is why the Fed cannot sound soft
GoldRate-driven fallMedium3 to 12 mo↘ December closed at 4,007.90 dollars on Friday, down 1.3 percent and down 4.1 percent on the week. Low was 3,989.10. Not a war hedge right now
DollarFlatLow1 to 4 wk↔ This feed closed at 101.81 on Friday, up 0.2 percent and flat on the week
Energy equitiesStrong on the weekMediumDays↔ Sector fund up 2.6 percent on Friday and 1.6 percent on the week. Not a reason to add at the high
ChinaWeak, no new decisionHigh1 to 3 mo↘ China fund down 0.4 percent on Friday and 4.5 percent on the week. Earnings forecasts are being cut. Do not chase the dip
MidtermsEight days outMediumDays↔ 3 Nov. The Iran file is now read through the election. That is a reason for headlines, not a position
Third quarter outputThursday, with PCEMediumDays↔ First read lands with personal income and outlays at 8:30. Two numbers, one morning

Portfolio

Position Weight Rationale
Overweight
Crude / energy (USO, XOM, CVX)+2%Hold it. Brent settled at 116.72 dollars and US crude at 103.27. The strait is not open and the agency says Saudi supply is at a multi-decade low. The strike talk is why you do not sell. The deal talk is why you do not add. Neither is a settlement
Power / utilities (XLU)+1%Hold the starter. It is the cleaner way to own the power demand behind the technology capex. The fund fell 0.7 percent on Friday, to 42.56. That is not a reason to add
Energy equity cash flows+1%The sector fund is up 1.6 percent on the week and 2.6 percent on Friday. Own the cash flow, not the crude print. Do not chase the Friday high
Cash / short billsHighThe yield index closed at 4.988 percent. The score is 43. Cash is paid to wait through an event week, and this is an event week
Underweight
Long duration (TLT, IEF)−5%The yield index is still 4.988 percent, and the long end eased 12 basis points on the week. Do not cover before Wednesday's statement. Do not add to the short either, into a decision with two-way language risk
Semis / high beta tech (SMH)−2%The semiconductor fund is down 2.3 percent on the week. Three mega caps report Wednesday and Thursday. Do not buy the dip before the prints
Airlines / transport (DAL, AAL)−2%No opening, no ship count. A deal headline is not a fuel bill falling. Wait for the waterway, not the rumour
China cyclicals (FXI, EEM)−2%The China fund is down 4.5 percent on the week and earnings forecasts are being cut. No new policy decision. Do not chase the dip
Consumer discretionary (XLY)−1%A fuel bill this high with gasoline up 34.2 percent over the year is a tax on the consumer. The Fed cannot offset it
Defense (ITA, LMT)0%Strike talk is not an order. The fund is down 3.3 percent on the week, which tells you the market is pricing de-escalation odds. Do not add on the rhetoric
Gold (GLD)0%The fund is down 4.0 percent on the week and December gold broke 4,000 dollars. The crude sleeve is the war hedge this month. No new entry
Financials (XLF)0%Keep it small. The fund fell 1.3 percent on Friday. A hawkish hold helps net interest margin and hurts credit. Those offset
Hedges
Long volatility into Wednesday and ThursdaySmallVIX closed at 19.45, under 20, into a policy decision and three mega cap prints in two days. That is cheap insurance for an event week, sized as insurance and not as a position

Cash stays high. A 43 score says the CAUTION label is still off and the dip bid is still off. It does not say buy duration, sell energy, or buy chips. Trade 43 as a 4.988 percent yield index, a Brent settlement of 116.72 dollars, a US crude settlement of 103.27 dollars, a strait that is not open, and a gold market that has stopped hedging the war. The deal talk is a reason to hold the crude sleeve. It is not a reason to sell it. The strike talk is a reason to hold it. It is not a reason to add it.

The next two weeks

Date Event Importance
26 Oct (Mon)US cash reopens. Asian trade already eased oil from Friday's high on deal talk. No new data print. A gap is not a settlement until it settlesHigh
27 Oct (Tue)US policy meeting, first day. No projections at this meetingHigh
28 Oct (Wed)US policy decision. Microsoft and Alphabet report after the close, 16:00 ET. The single busiest session of the windowHigh
29 Oct (Thu)September personal income and outlays, with the first read on third quarter output, both at 8:30 ET. Amazon and Intel report after the close. Eli Lilly reports at 08:00 ETHigh
30 Oct (Fri)Exxon and Chevron report at 08:00 ET. Month end. A month end rebalance can move the long end without newsMedium
2 Nov (Mon)Apple reports at 15:00 ET. Outside this weekMedium
3 Nov (Tue)US midterms. The Iran file is being read through the election. Headlines, not positionsMedium
4 Nov (Wed)September trade in goods and services at 8:30 ET. The edge of this windowLow
17 Nov (Tue)Next Nvidia date, 15:00 ET. Outside this window. The prior quarter has already been reported. Do not treat 17 Nov as this weekMedium
8 to 9 Dec (Tue to Wed)Following US policy meeting, with projections. Outside this window. The weekend coverage leans to a rise. A cut is not the base case in this noteHigh

Weekdays above match the calendar. September consumer prices already printed. September payrolls already printed. Do not treat either as a new release. The tanker damage count from the strait is dated 22 Oct and is not overnight news. A four-day-old count is not a fresh escalation.

Scorecard

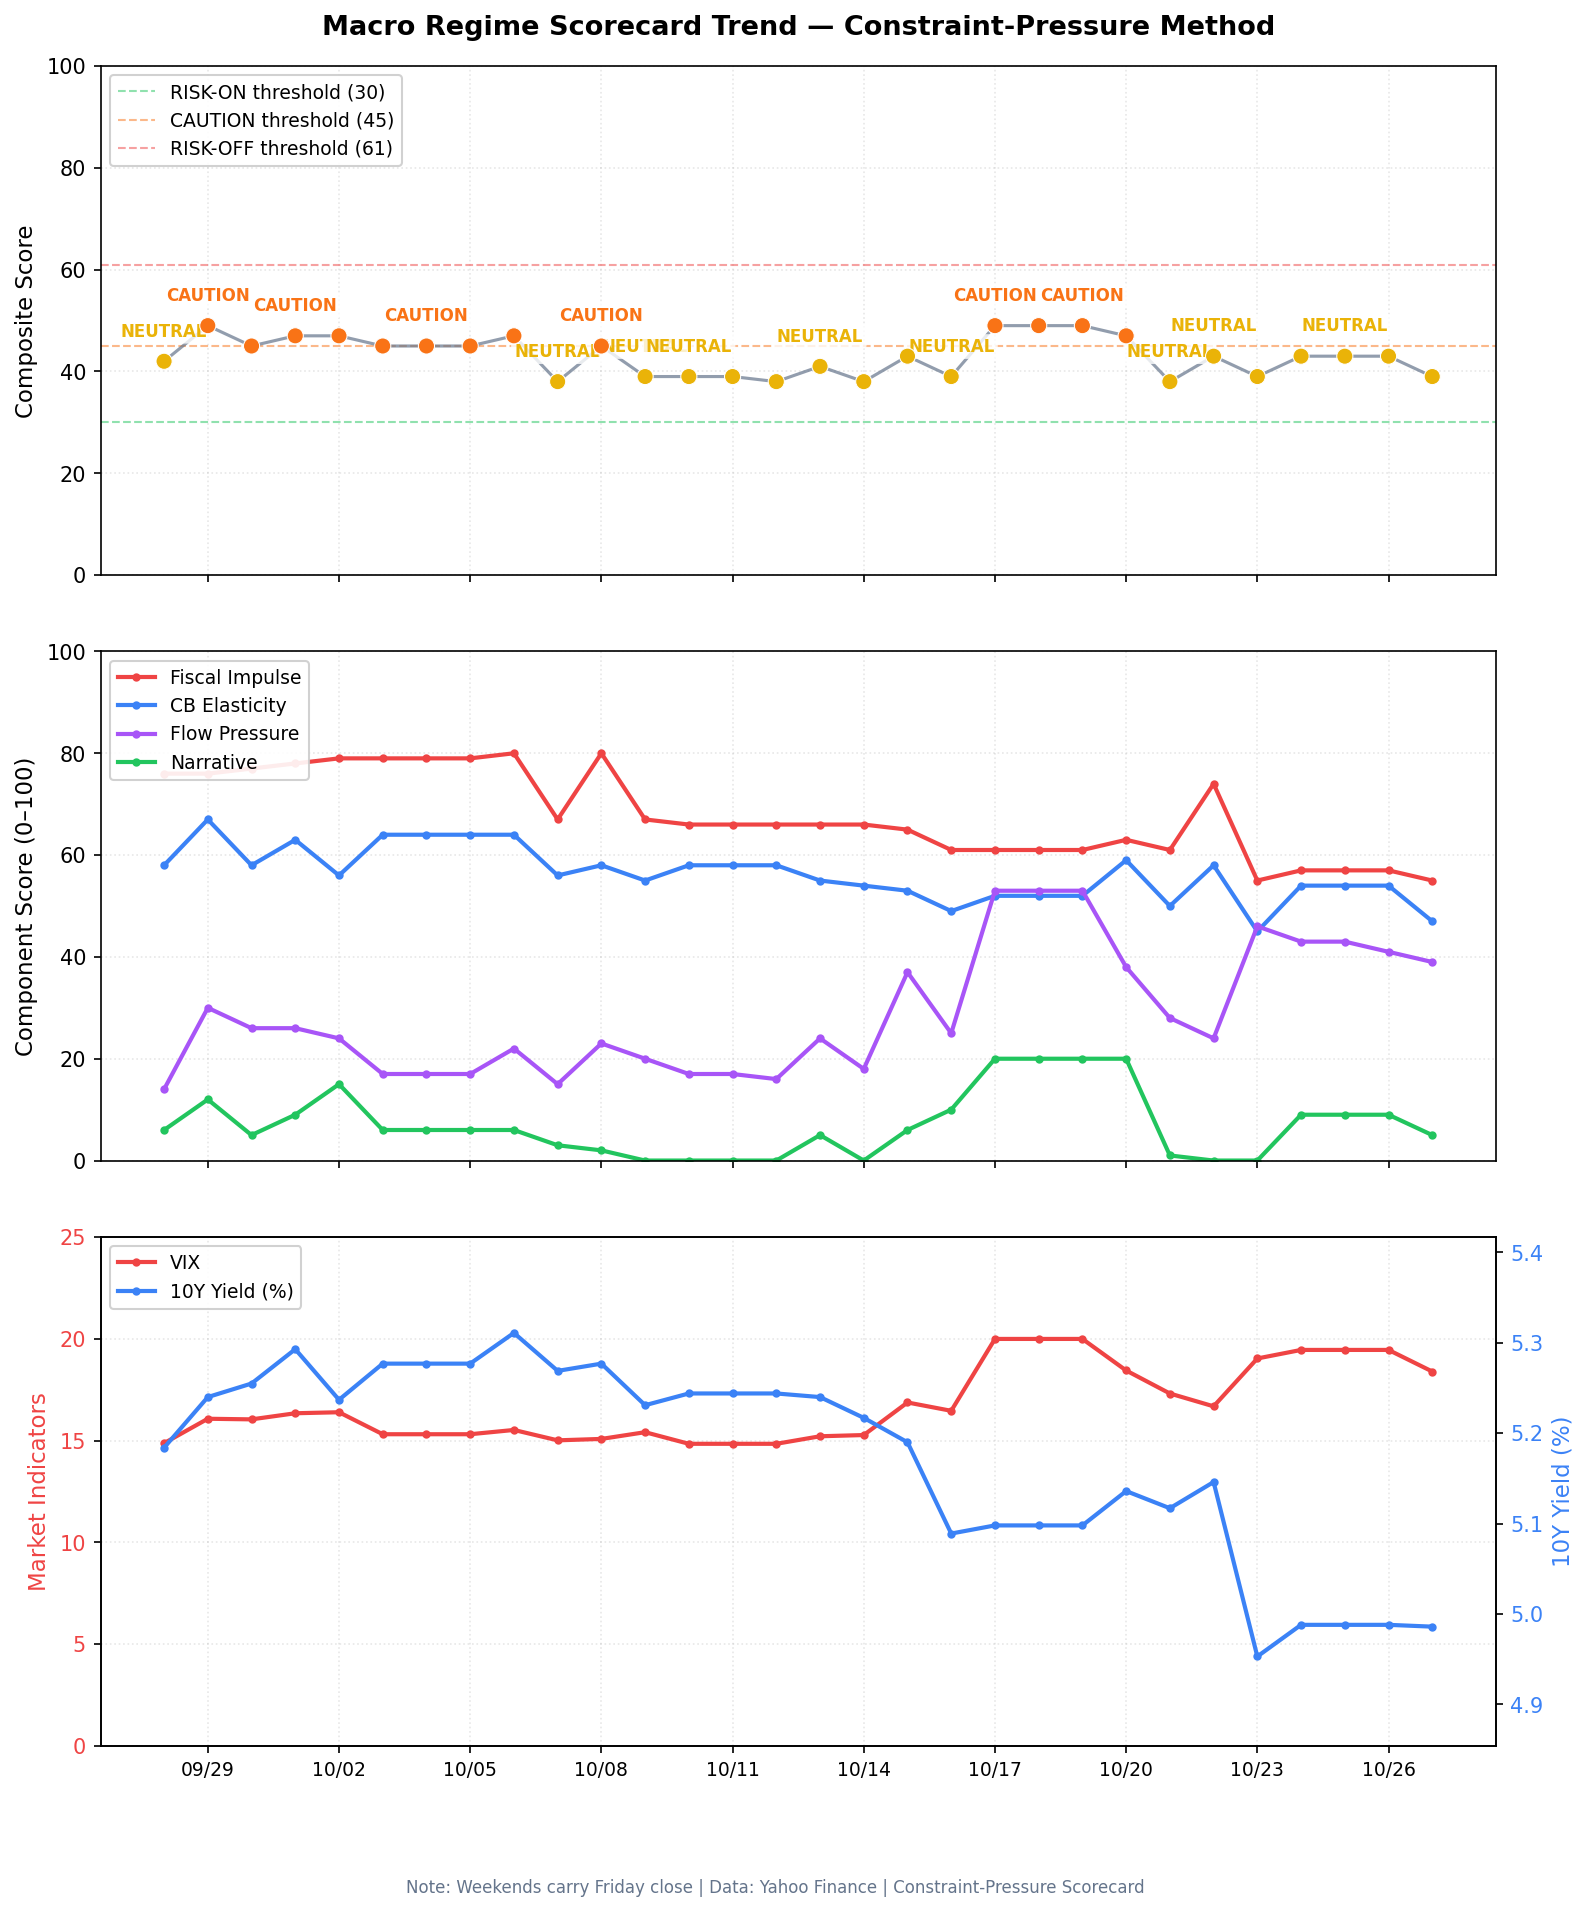
43 of 100 sits in NEUTRAL. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse57Unchanged. The yield index closed at 4.988 percent on Friday, up 3.5 basis points on the day and lower on the week. The 10-year level is the binding constraint here, not the weekly drift. Still not a bond bid
CB Elasticity54Unchanged. A hold on Wednesday is the base in the weekend coverage, with a December rise kept on the table. The 5-year index at 4.805 percent leaves little room to ease. No reason to change the score before the statement
Flow Pressure41Down 2 points from 43. VIX closed at 19.45 on Friday, up 0.42 points, under 20. The move is small and does not change the total
Narrative Coherence9Unchanged, and the calmest leg. One story is being traded: oil up, hike odds up, yields up, gold down, technology down. A coherent but uncomfortable story scores low because there is nothing to arbitrage between narratives
Composite43NEUTRAL

The label did not flip. The score is 43. Yesterday it was 43. The line for CAUTION is 45. The line for RISK-ON is 30. The line for RISK-OFF is 61. A higher score means more stress. This score did not rise. It did not fall. It did not cross 45. It did not cross 30. It is 2 points from CAUTION, with a policy decision, an inflation print and three mega cap earnings inside the next four sessions. A 43 going into that calendar is a hold, not a signal.

Data through the 23 Oct 2026 US close. This is a Monday edition before the US open. The Asian session moved oil and is described above. A pre-open screen is not a new settlement.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.