OverWise

Market regime, November 7

Top five drivers, the risk matrix and the book for Saturday, November 07, 2026.

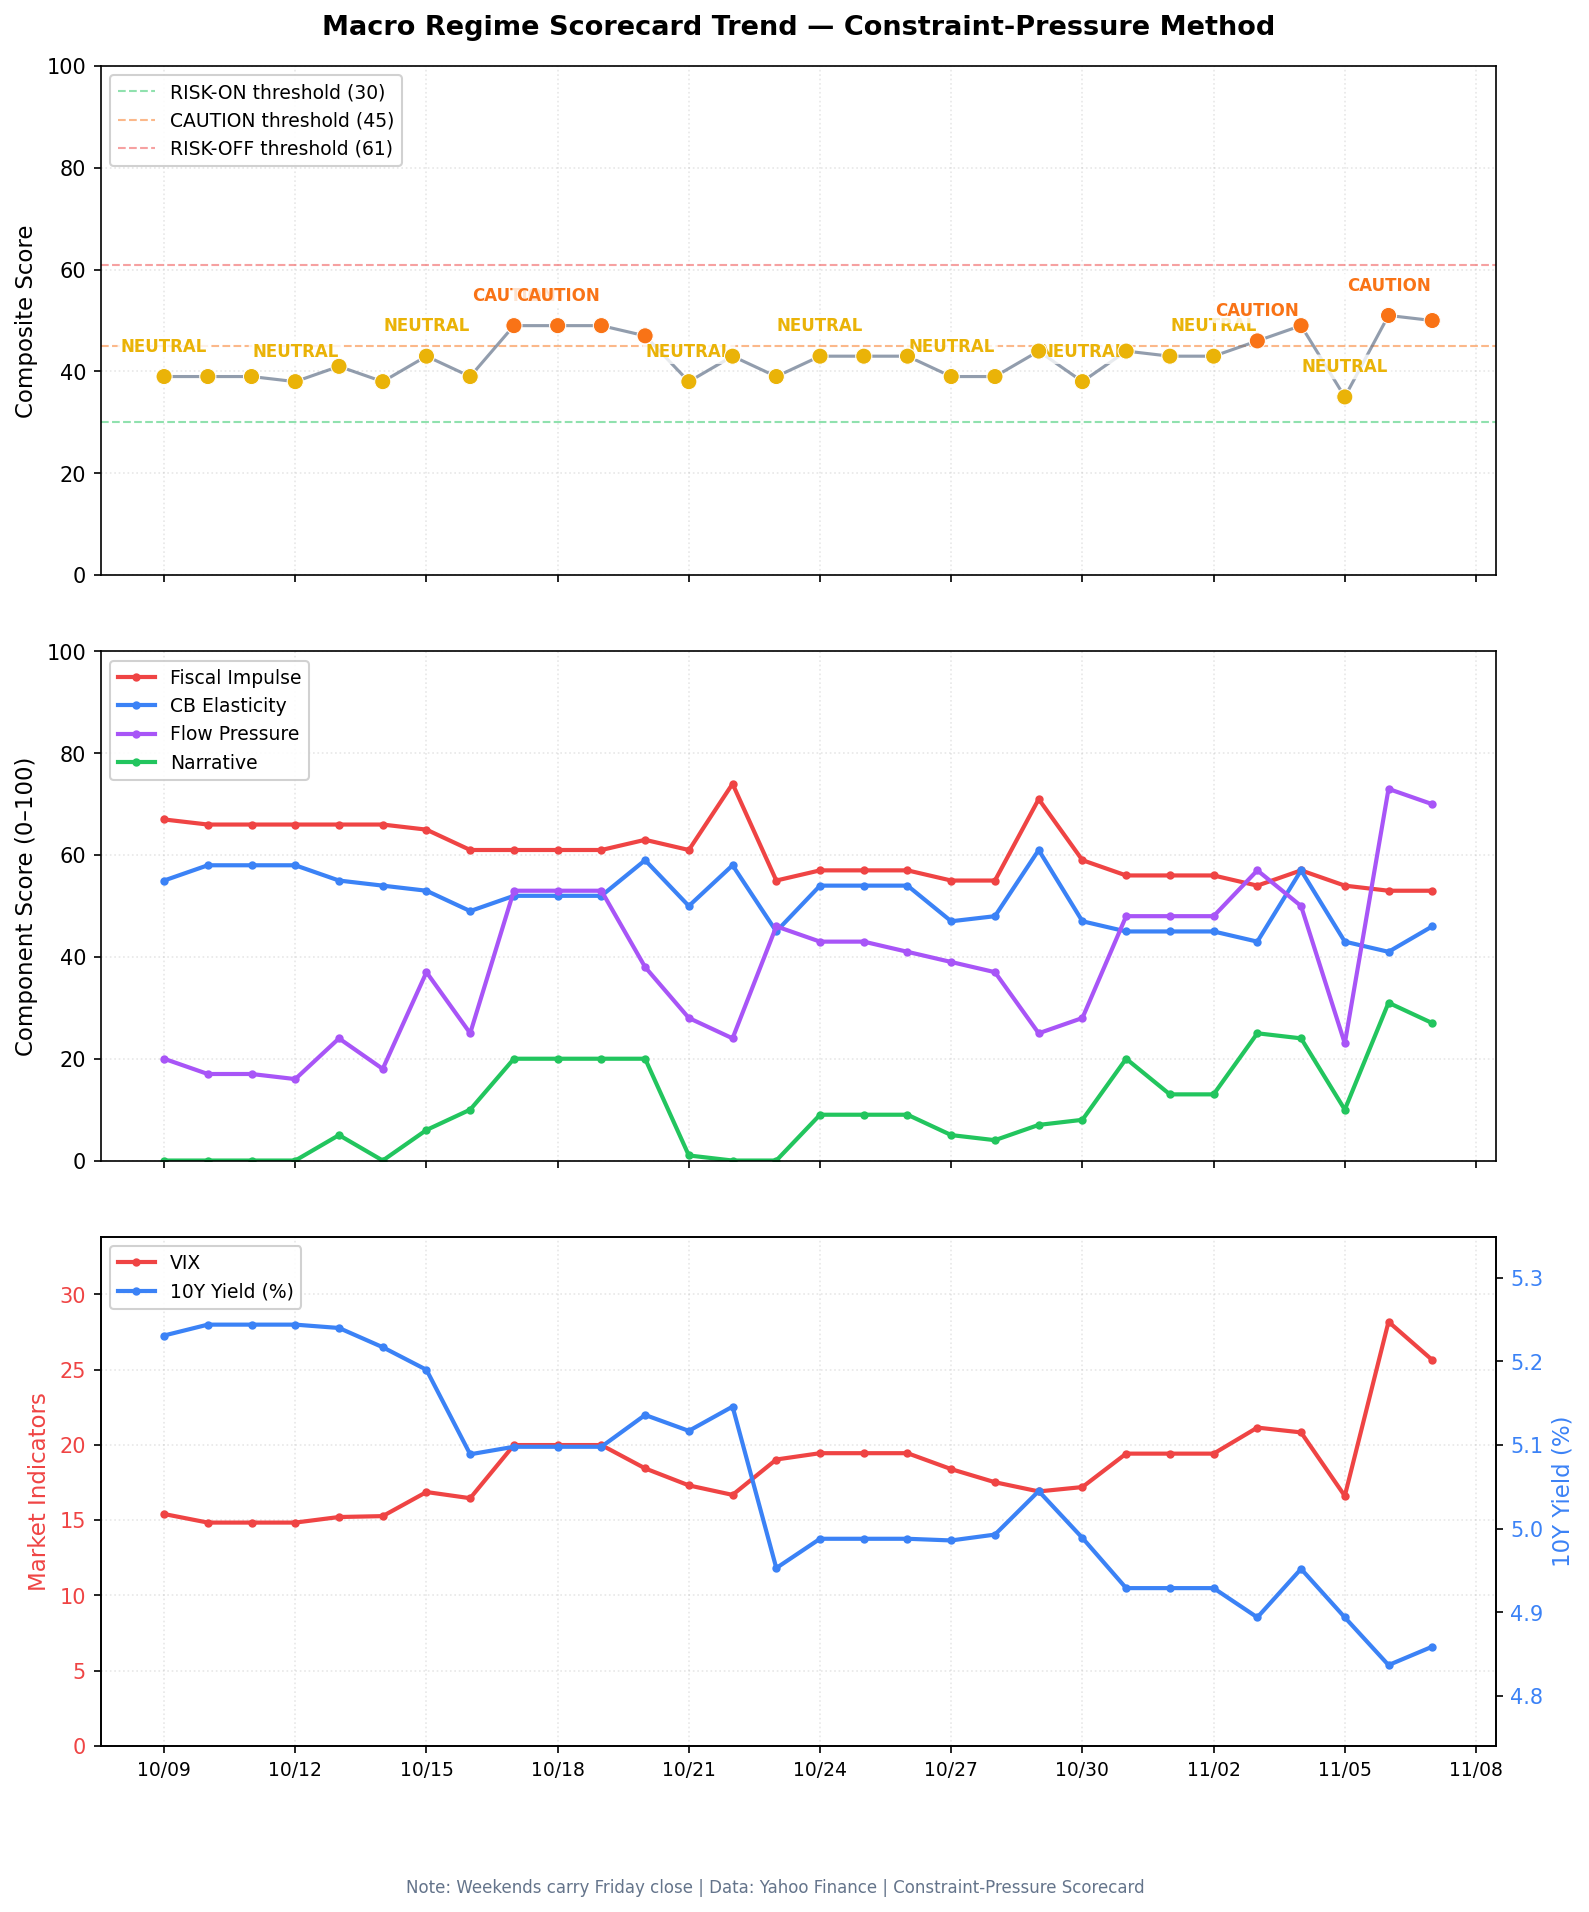
The label did not flip. The score is 50 of 100. The label is CAUTION. Yesterday the score was 51, and the label was already CAUTION. CAUTION runs from 45 to 60. NEUTRAL runs from 30 to 44. RISK-ON is below 30. RISK-OFF starts at 61. Volatility came off Thursday's spike, and yields backed up after the labor print. Those two moves almost offset, so the score eased by one point and stayed in the same band.

Read the five drivers
Before the US open Next review 8 Nov 2026 (Sun)

Regime score

50of 100

CAUTION

11 under RISK-OFF, 5 over the NEUTRAL line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Friday's US cash close is in. This note is Saturday morning. Cash markets are closed. Equity, yield, dollar, and fund rows are Friday's close, against Thursday. The oil rows are Friday's settlement. The continuous last on this series is a different print, and it is not in the settlement row. A Saturday missile report is a wire. It is not a new close. This note does not cite oil or gold volume, and it does not treat a gold futures last as a settlement. The gold row is the fund.

The book does not buy Friday's bounce. The labor print was stronger than the poll. Hold a residual crude sleeve. The week in oil was still a large drop, and that is not a reason to sell the last of the sleeve. A Saturday headline is not a reason to add it. Do not cover the bond. Tuesday's inflation print is the next number that can change that.

In short

MARKET REGIME, Nov 7 (Sat)

Signal. Caution. Hold energy. Do not chase. Score 50 of 100.

  1. United States October jobs rose 165,000. Do not cover the bond.
  2. United States Stocks bounced a little Friday. Do not buy it.
  3. United States Yields rose Friday. A December hike looks likely.
  4. Iran Oil settled a few cents higher. Hold the sleeve.
  5. United States Chips bounced Friday. The week is still down.

Markets bar

Equity, yield, dollar, and fund rows are Friday's cash close, against Thursday. Brent and WTI rows are the settlement in the oil story. The continuous last on this series is a different print, and it is not the settlement. This note does not cite oil or gold volume. The gold row is the fund. There is no Saturday cash close in this table.

The week did not get repaired. Reuters said the S&P 500 dropped 2.7 percent for the week, the Nasdaq 3.4 percent, and the Dow 0.9 percent. Reuters also said the S&P 500 energy index dropped 12 percent for the week, its worst week since April 2025.

Asset Level Change
S&P 500 (Fri close)7,376.86Up 23.13 points, or 0.31 percent, vs Thursday's 7,353.73. Reuters printed the same close
Nasdaq Composite (Fri close)24,579.42Up 264.42 points, or 1.09 percent, vs Thursday's 24,315.00. Reuters called the day 1.1 percent
Dow (Fri close)51,285.73Down 237.33 points, or 0.46 percent, vs Thursday's 51,523.06
Russell 2000 (Fri close)2,754.11Up 0.89 percent vs Thursday's 2,729.89, on this series
VIX (Fri close)25.64Down 2.54 points vs Thursday's 28.18. The score uses this close
US 10 year yield index (Fri close)4.859 percentUp 2.2 basis points vs Thursday's 4.837. This is the index in the score
5 year yield index (Fri close)4.648 percentUp 4.0 basis points vs Thursday's 4.608
30 year yield index (Fri close)5.260 percentUp 0.9 basis points vs Thursday's 5.251
3 month yield index (Fri close)4.000 percentUp 1.3 basis points vs Thursday's 3.987
Brent January settlement98.32 dollarsUp 3 cents, or 0.03 percent, from Thursday's 98.29
WTI settlement90.83 dollarsUp 31 cents, or 0.34 percent, from Thursday's 90.52
Dollar index (Fri close)102.279Up 0.72 percent vs Thursday's 101.55 on this series
Gold fund (Fri close)372.52Down 0.79 percent vs Thursday's 375.49
Energy fund (Fri close)61.62Unchanged on the day, from Thursday's 61.63
Oil fund (Fri close)148.41Up 0.13 percent vs Thursday's 148.21. The fund is not the settlement
Semiconductor fund (Fri close)463.96Up 3.62 percent vs Thursday's 447.73
Philadelphia semiconductor index (Fri close)9,390.25Up 4.21 percent vs Thursday's 9,011.14. Reuters called the rally 4.2 percent
Long bond fund (Fri close)81.92Unchanged on the day, from Thursday's 81.93
High yield fund (Fri close)77.23Down 0.06 percent vs Thursday's 77.28
Investment grade fund (Fri close)104.53Down 0.12 percent vs Thursday's 104.66
Large cap China fund (Fri close)34.95Unchanged on the day, from Thursday's 34.94
Emerging markets fund (Fri close)59.33Up 2.21 percent vs Thursday's 58.05
Brent continuous last (this series)97.76 dollarsNot Friday's settlement. The settlement is 98.32
WTI continuous last (this series)90.34 dollarsNot Friday's settlement. The settlement is 90.83

Top five drivers

United States The labor print is in

It was much stronger than the poll.

SignalYesterday's note was waiting on this number. It is no longer waiting.

Employers added 165,000 jobs in October. Economists polled by Reuters had looked for 65,000. The unemployment rate fell to 4.1 percent from 4.2 percent in September. The Bureau's own headline called that little changed. The table shows the tenth of a point. August and September together were revised up by 84,000. September is now a gain of 60,000, not the 29,000 in yesterday's note. August is now 186,000.

The headline was broad. Professional and business services added 70,000. Health care added 42,000. Transportation and warehousing added 25,000. Manufacturing added 19,000. Average hourly earnings rose 14 cents, or 0.4 percent, to 38.00 dollars, and 3.1 percent on the year. The workweek stayed at 34.4 hours.

The print is not clean underneath. A broader measure that counts discouraged workers and people working part time because they could not find full time work rose to 7.9 percent from 7.6 percent. That part time group increased by 339,000, to 4.8 million. The median spell of unemployment rose to 11.9 weeks. Reuters said September consumer prices were up 3.7 percent on the year. October prices are not in this print. They come on Tuesday.

Macro ImpactYesterday the trap was covering the bond, or adding to the short, before a number that was not out. Today the number is out, and it was hot. Covering the long bond because stocks bounced on Friday is how you buy duration into a labor market that just cleared a low bar by a wide margin, with Tuesday's inflation print still ahead. Adding to the short because the 10 year index is 4.859 percent is a chase into a closed market, after a day that already marked the hike odds higher. The level is not easy. The day is not a new vote.

PositioningStay underweight long duration. Do not cover. The wait for the labor print is over. The wait for Tuesday's prices is not.

Key SourcesReuters, 6 Nov, https://www.reuters.com/business/us-job-growth-beats-expectations-october-unemployment-rate-falls-41-2026-11-06/ ; Bureau of Labor Statistics, Employment Situation for October 2026, https://www.bls.gov/news.release/archives/empsit_11062026.htm ; Reuters, 6 Nov, https://www.reuters.com/world/us/four-things-note-fridays-us-jobs-report-2026-11-06/
United States The label held

Friday's bounce did not repair Thursday.

SignalThursday's break is still the week. Friday was a partial bounce, and the Dow did not join it.

The S&P 500 closed at 7,376.86, up 23.13 points, or 0.31 percent, from Thursday's 7,353.73. Reuters printed that same close and called the day 23 points, or 0.32 percent. The Nasdaq Composite closed at 24,579.42 on this series, up 1.09 percent. Reuters said it ended up 1.1 percent, a gain of 264 points, after trading as much as 2 percent higher. The Dow closed at 51,285.73, down 0.46 percent. On this series the Russell 2000 rose 0.89 percent, to 2,754.11. The volatility index closed at 25.64, down 2.54 points from 28.18. That close is why flow pressure eased. It is still the stress in the score.

Reuters said the week was still a loss. The S&P 500 dropped 2.7 percent, the Nasdaq 3.4 percent, and the Dow 0.9 percent. Reuters said the week took the Nasdaq into correction territory, a 10 percent decline from its peak a month ago. Friday did not close that gap.

Macro ImpactYesterday the trap was buying the break because the tape had fallen 4.36 percent. Today the trap is buying the same tape because it rose 0.31 percent with the market shut for the weekend. A correction is a description of the drop from the peak. It is not a schedule for a bounce, and a one day bounce inside a down week is not the repair. The labor print is already in the Friday close. It is not a reason to add equity risk on a Saturday screen.

PositioningDo not add equity risk on the bounce. The label did not change. The sleeves do not either. Cash still beats a chase into a closed market.

Key SourcesReuters, 6 Nov, https://www.reuters.com/business/nasdaq-futures-rise-after-steep-ai-selloff-chip-stocks-stabilize-2026-11-06/

United States Yields backed up

A December hike looks more likely. There is still no new vote.

SignalThere is no new US rate decision this morning. The October meeting already happened, on 27 Oct (Tue) and 28 Oct (Wed). The Fed left the policy rate in a range of 3.75 to 4.00 percent. The next meeting is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections. That date sits outside this two week list.

The yield index in the score closed Friday at 4.859 percent, up 2.2 basis points from 4.837. The 5 year index closed at 4.648 percent, up 4.0 basis points. The 30 year index closed at 5.260 percent, up 0.9 basis points. The 3 month index closed at 4.000 percent, up 1.3 basis points. The long bond fund was unchanged at 81.92. A hot labor print and a flat long bond fund can sit in the same session. The yield index is the one in the score.

Reuters said markets were pricing about an 80 percent chance of a quarter point increase at the December meeting, up from 66.9 percent on Thursday, on the CME tool in the jobs story. The same day's equity close story had a different screen, 78 percent versus 70 percent earlier, on LSEG. The direction agrees. The gap between 78 and 80 is not a trade. San Francisco Fed president Mary Daly said she expects further tightening, and that the path should be deliberate and gradual. She is not a voter this year. St. Louis Fed president Alberto Musalem said inflation remained the top concern in his district and that policy has to be set for the economy of the day. That is comment, not a decision.

The dollar index on this series closed at 102.279, up 0.72 percent from Thursday's 101.55. That agrees with a rates story that got a little tighter. It is one session.

Macro ImpactA higher yield close is the labor print, written into Friday's bond market, while two Fed presidents were still arguing for more restraint on inflation. Covering the short because the equity bounce was small is how you buy a bond into hike odds that rose, and into an inflation print that is not out. Adding to the short because the index is 4.859 percent, with the market closed, is the other chase. The level is not easy. The day is not a new Fed path.

PositioningStay underweight long duration. Do not cover, and do not add to the short, before Tuesday. Hold cash and short bills over the long end.

Key SourcesReuters, 6 Nov, https://www.reuters.com/business/traders-raise-bets-fed-rate-hike-after-jobs-report-2026-11-06/ ; Reuters, 6 Nov, https://www.reuters.com/business/daly-says-fed-rate-hike-likely-despite-painful-tech-stock-dive-2026-11-06/ ; Federal Reserve calendar, December 8 to 9, 2026, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm

Iran Oil settled a few cents higher

The week is still a large drop. Saturday is not a new close.

SignalFriday's settlement is the number. The continuous last after it is not a second close. A Saturday wire is not a third.

January Brent settled 3 cents higher, at 98.32 dollars, 0.03 percent above Thursday's 98.29. WTI settled 31 cents higher, at 90.83 dollars, 0.34 percent above Thursday's 90.52. Reuters and a second wire both printed those settlements. On this series the continuous Brent last was 97.76 dollars, and the continuous WTI last was 90.34 dollars. Those lasts are not the settlements.

The day was small. The week was not. Reuters said January Brent was set for a 17 percent decline on the week, and WTI for a 13 percent decline. A second wire put the weekly drop at more than 16 percent for Brent and close to 13 percent for WTI. Either weekly print is a large drop. The settlement is the day.

The late uptick was the war, not a signed opening. Reuters said crude edged up late on Friday after the president said he would soon decide whether to pursue a peace agreement or destroy what remains of Iran. A Greek ship manager said a seafarer was killed in a 5 Nov explosion on an oil products tanker in the Gulf, believed to have been a missile. UKMTO figures in the same story still show attacks running close to a record pace. On Saturday, Iran's Tasnim agency said initial reports indicated two missiles had struck Qeshm Island, and that there was no official information on damage. Qatar's International Media Office denied reports that the United States and Iran had failed to reach an agreement, and said both sides continue to work toward one. Neither side has announced a breakthrough.

The oil fund rose 0.13 percent, to 148.41. The energy fund was unchanged at 61.62. Reuters said the energy index in the S&P 500 dropped 12 percent for the week. The fund and the settlement did not tell the week's story. The settlement is still the crude sleeve.

Macro ImpactYesterday the trap was adding because the settlement had risen 3.67 dollars on tanker hits that had not closed the strait. Today the trap is selling the last of the sleeve because the week was a large drop, or adding because a Saturday agency report says missiles hit an island. A few cents on the settlement, with no deal signed, is not a reopening and not a new war premium you can trade on a closed screen. The continuous last near 97.76 dollars is a different contract print. It is not a reason to mark the sleeve down to that number.

PositioningHold a residual crude sleeve. Do not add it, and do not sell the last of it. No airlines and no transports. A settlement of 98.32 dollars is a few cents above Thursday. It is not a signed reopening, and Saturday is not a new settlement.

Key SourcesReuters, 6 Nov, https://www.reuters.com/business/energy/oil-set-sharp-weekly-drop-middle-east-supply-concerns-provide-floor-2026-11-06/ ; Reuters, 7 Nov, https://www.reuters.com/world/middle-east/two-missiles-strike-irans-qeshm-island-tasnim-news-agency-says-2026-11-06/ ; CNBC, 6 Nov, https://www.cnbc.com/2026/11/06/oil-price-today-brent-wti.html

United States Chips bounced on Friday

The week did not.

SignalFriday's cash close gave back part of Thursday's unwind. It did not end it.

On this series the semiconductor fund rose 3.62 percent, to 463.96. The Philadelphia semiconductor index rose 4.21 percent, to 9,390.25. Reuters called that rally 4.2 percent. Nvidia closed 2.78 percent higher on this series, at 186.64. Reuters said it rose 2.8 percent. AMD closed 11.04 percent higher on this series, at 449.04. Reuters said it added 11 percent. The Nasdaq 100 fund rose 1.40 percent, to 656.10.

The cash rich names did not all follow. Microsoft closed 0.99 percent lower on this series, at 530.61. Amazon closed 0.35 percent lower. Meta closed 0.84 percent higher, and Alphabet closed 0.78 percent higher. Reuters said the revival was still the buildout, and that the week had put that trade on trial again without a verdict.

Nvidia is on the calendar for 17 Nov (Tue). That date is a slot on this series. It is not a confirmed release clock, and it is not a reason to buy the fund on a Saturday.

Macro ImpactThursday the tape sold the suppliers hardest. Friday it bought some of them back, and it bought AMD harder than the cash rich names. Buying the semiconductor fund because it rose 3.62 percent is how a bounce becomes a position you have to defend into Tuesday's inflation print, with the week still down and the market closed. Shorting the cash rich names into a mixed Friday, after they fell on Thursday, is the other side of the same chase.

PositioningDo not buy the semiconductor fund, and do not short the cash rich names into the bounce. Cash still beats a chase into a closed market.

Key SourcesReuters, 6 Nov, https://www.reuters.com/business/nasdaq-futures-rise-after-steep-ai-selloff-chip-stocks-stabilize-2026-11-06/

Risk matrix

The method note is above, in the markets bar. Cells below are the Friday fact, or the Saturday wire after it. The continuous last is not in this table.

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreCAUTIONHighDays51 to 50. The label did not flip. It did not leave 45 to 60, and it did not reach 61
US equitiesSmall bounce, week still downHighDaysS&P 500 up 0.31 percent to 7,376.86. Reuters put the week at down 2.7 percent
VolatilityLower, still elevatedHighDays25.64, down 2.54 points from 28.18. Still the stress in the score
LaborIn, stronger than the pollHighDone for this printOctober payrolls up 165,000. Unemployment 4.1 percent. The poll was 65,000
US 10 year indexHigherHighDaysScore uses 4.859 percent, up 2.2 basis points
Fed pathHike odds higher, no new voteHighWeeksPolicy rate still 3.75 to 4.00 percent. December odds rose. The meeting is 8 Dec and 9 Dec
Brent settlementA few cents higherHighDaysSettled at 98.32 dollars, up 3 cents from 98.29. The week is still a large drop
WTI settlementA few cents higherHighDaysSettled at 90.83 dollars, up 31 cents from 90.52
StraitAttacks and talks, no signed dealHighWeeksFriday settlement first. Saturday Qeshm report is a wire, not a new close
ChipsBounced on the day, week still downHighDaysSemiconductor fund up 3.62 percent. Nvidia is on the calendar for 17 Nov
DollarHigherMediumDays102.279, up 0.72 percent vs Thursday's 101.55 on this series
Gold fundLowerMediumDaysDown 0.79 percent to 372.52. The hedge question did not change hands
Emerging markets fundHigher on the dayMediumDaysUp 2.21 percent to 59.33. The China fund was unchanged. That is not a package
High yieldLittle changedMediumDaysDown 0.06 percent to 77.23

Portfolio

Sleeve Stance Rationale
CrudeHold a residual. Do not add. Do not sell the last of itJanuary Brent settled 3 cents higher, at 98.32. No deal is signed. Saturday is not a new close
Energy equities (XLE)Do not addThe fund was unchanged at 61.62. Reuters said the energy index dropped 12 percent for the week
Oil fund (USO)Hold with the sleeveUp 0.13 percent on Friday. The fund is not the settlement, and it is not a new entry
Long duration (TLT)Underweight. Do not coverYield index at 4.859 percent. The labor print was hot. Tuesday's prices are not in
Cash and short billsOverweight versus the long endPaid to wait through Tuesday's inflation print, with the market closed today
Semiconductors (SMH)Do not buy the bounce. Do not short the cash rich namesThe fund rose 3.62 percent. The week is still down
Gold (GLD)No new entryThe fund fell 0.79 percent. A down day does not replace the crude sleeve
Airlines and transportsNoThe settlement is a few cents higher. The opening is not signed
China cyclicalsUnderweightThe large cap fund was unchanged. The emerging markets fund rose 2.21 percent. That is not a package
Broad equityDo not addThe S&P 500 rose 0.31 percent. A bounce inside a down week is not a buy, and the label is still CAUTION

The next two weeks

Date Event Why it matters
10 Nov (Tue)Consumer price index for October, and real earnings, both at 8:30 a.m. EasternThe inflation print in front of December. Not in. September prices were up 3.7 percent on the year, in the jobs story
11 Nov (Wed)Veterans DayA holiday on the statistics calendar. No Bureau release that day
13 Nov (Fri)Producer price index for October, 8:30 a.m. EasternThe wholesale price print in the same window. Not in
17 Nov (Tue)Import and export price indexes for October, 8:30 a.m. Eastern. Nvidia is on the calendar the same dayThe trade price print is a Bureau date. The Nvidia date is a slot on this series, not a confirmed release clock
20 Nov (Fri)State employment and unemployment for October, 10:00 a.m. EasternA state print. Not the national labor report

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections. The next national employment situation is 4 Dec (Fri), also outside this list. The new Congress is not seated for either date.

Scorecard

50 of 100 sits in CAUTION. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse53Unchanged. The 10 year index closed Friday at 4.859 percent. The backup from Thursday was small. The level is still not easy
CB Elasticity46Up from 41. The 5 year index closed at 4.648 percent. December hike odds rose. That is less room, not a new vote
Flow Pressure70Down from 73. The volatility index closed at 25.64, down 2.54 points. It is still the stress in the score. The high yield fund was little changed
Narrative Coherence27Down from 31. Friday was a split tape. The Nasdaq rose, the Dow fell, and oil did not tell the equity story
Composite50CAUTION

The label held. Yesterday was 51, CAUTION. Today is 50, CAUTION. RISK-ON is below 30. RISK-OFF is 61 and above. A higher score means more stress. The one point ease was volatility coming off Thursday's spike, almost fully offset by a tighter rates score after the labor print. A score of 50 into a closed weekend is a hold on the sleeves you have. It is not a signal to buy Friday's bounce, and it is not a signal to dump the crude hedge.

Data through the 6 Nov 2026 US close. This is a Saturday morning note. Cash markets are closed. There is no Saturday US settlement in this note.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.