OverWise

Market regime, November 6

Top five drivers, the risk matrix and the book for Friday, November 06, 2026.

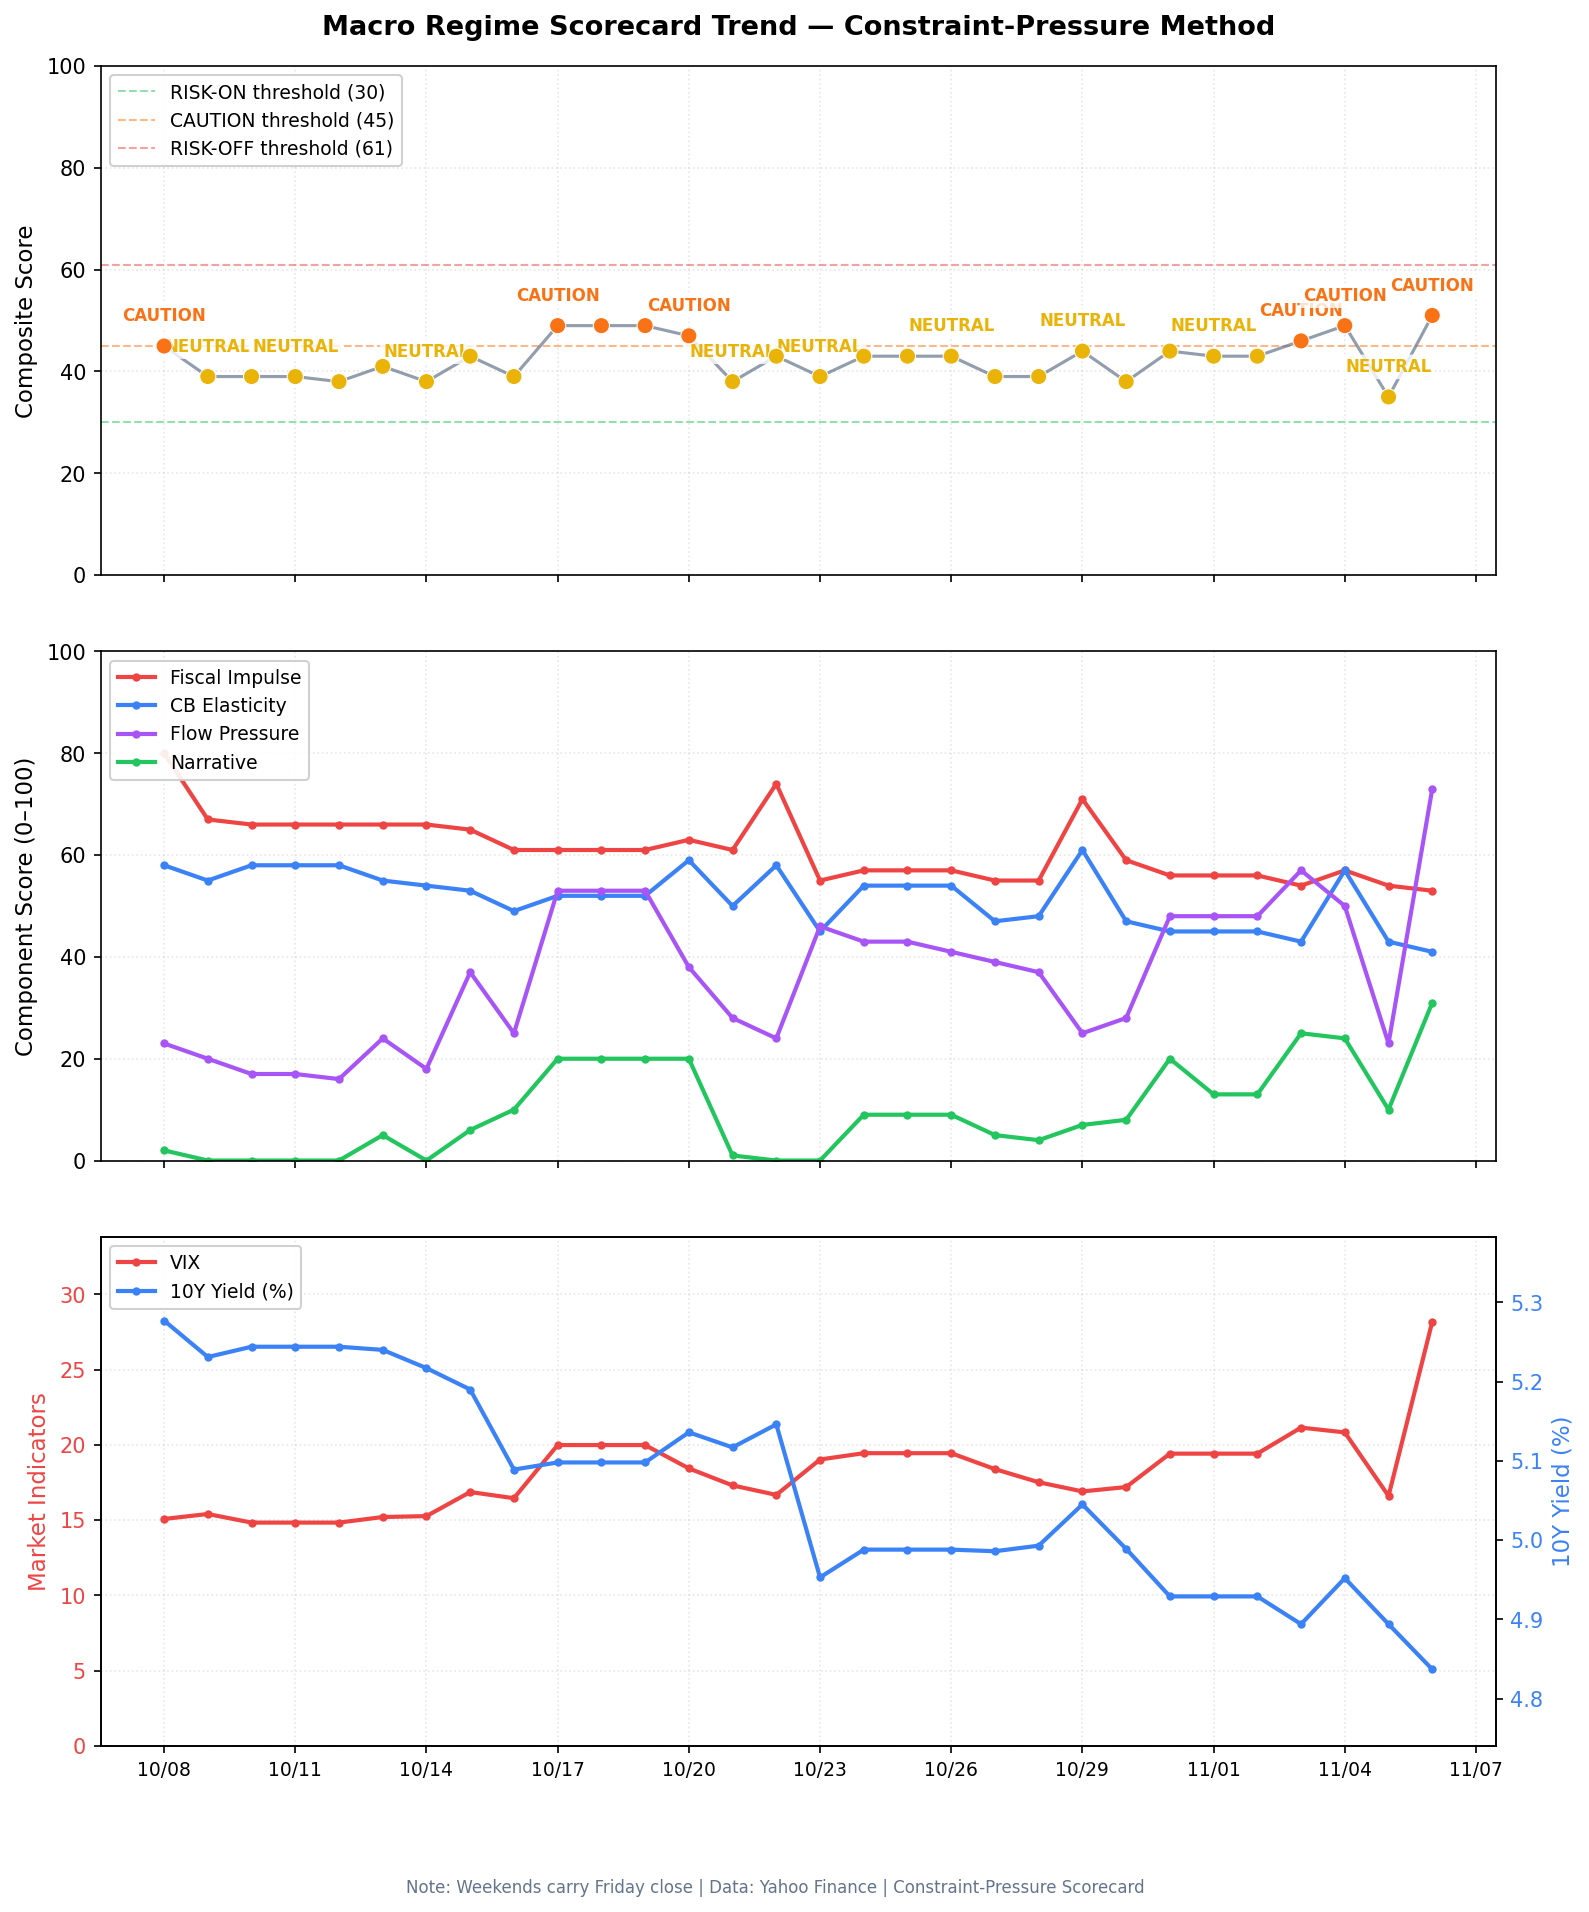
This is a regime flip. The score is 51 of 100. The label is CAUTION. Yesterday the score was 35, and the label was NEUTRAL. CAUTION runs from 45 to 60. NEUTRAL runs from 30 to 44. RISK-ON is below 30. RISK-OFF starts at 61. The score rose because volatility came back in one session. The new Congress is still not seated.

Read the five drivers
Before the US open Next review 7 Nov 2026 (Sat)

Regime score

51of 100

CAUTION

10 under RISK-OFF, 6 over the NEUTRAL line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Thursday's US cash close is in. This note is Friday morning, before the US cash open. Asia is open. Equity, yield, dollar, and fund rows are Thursday's close. The oil rows are Thursday's settlement. Prints after that close are screens. The October employment print is later today.

The book does not buy the break. Hold a residual crude sleeve. Do not sell the last of it, and do not add it because the settlement bounced. Do not buy chips because Asia is already down. Do not cover the bond before the labor print.

In short

MARKET REGIME, Nov 6 (Fri)

Signal. Caution. Hold energy. Do not chase. Score 51 of 100.

  1. United States Stocks fell hard yesterday. Do not buy the dip.
  2. Iran Oil settled higher yesterday. Hold the sleeve.
  3. United States Yields eased yesterday. Do not cover the bond.
  4. United States Chips led yesterday's drop. Asia is still selling.
  5. United Kingdom Britain hiked to 4 percent. Jobs print is today.

Markets bar

Equity, yield, dollar, and fund rows are Thursday's cash close, against Wednesday. Brent and WTI rows are the settlement in the oil story. The continuous last on this series is a different print, and it is not in the table. Asia rows and the Friday oil screen are open prints in the morning wrap. This note does not cite oil or gold volume, and it does not treat a gold futures last as a settlement. The gold row is the fund.

The continuous Brent last on this series was 100.25 dollars. The continuous WTI last was 91.89 dollars. Those are not Thursday's settlements. The settlements are 98.29 and 90.52.

Asset Level Change
S&P 500 (Thu close)7,353.73Down 334.89 points, or 4.36 percent, vs Wednesday's 7,688.62
Nasdaq Composite (Thu close)24,315.00Down 1,421.51 points, or 5.52 percent, vs Wednesday's 25,736.51
Dow (Thu close)51,523.06Down 1,833.06 points, or 3.44 percent, vs Wednesday's 53,356.12
Russell 2000 (Thu close)2,729.89Down 4.45 percent vs Wednesday's 2,856.95, on this series
VIX (Thu close)28.18Up 11.57 points vs Wednesday's 16.61. The score uses this close
US 10 year yield index (Thu close)4.837 percentDown 5.7 basis points vs Wednesday's 4.894. This is the index in the score
5 year yield index (Thu close)4.608 percentDown 8.1 basis points vs Wednesday's 4.689
30 year yield index (Thu close)5.251 percentDown 3.1 basis points vs Wednesday's 5.282
3 month yield index (Thu close)3.987 percentDown 3.8 basis points vs Wednesday's 4.025
Brent January settlement98.29 dollarsUp 3.67 dollars, or 3.88 percent, from Wednesday's 94.62
WTI December settlement90.52 dollarsUp 2.40 dollars, or 2.72 percent, from Wednesday's 88.12
Dollar index (Thu close)101.719Up 0.21 percent vs Wednesday's 101.510 on this series
Gold fund (Thu close)375.49Up 0.81 percent vs Wednesday's 372.49
Energy fund (Thu close)61.63Down 2.98 percent vs Wednesday's 63.52
Oil fund (Thu close)148.21Up 1.93 percent vs Wednesday's 145.41. The fund is not the settlement
Semiconductor fund (Thu close)447.73Down 11.21 percent vs Wednesday's 504.27
Long bond fund (Thu close)81.93Up 0.21 percent vs Wednesday's 81.76
High yield fund (Thu close)77.28Down 0.31 percent vs Wednesday's 77.52
Investment grade fund (Thu close)104.66Up 0.15 percent vs Wednesday's 104.50
Large cap China fund (Thu close)34.94Up 1.01 percent vs Wednesday's 34.59
Emerging markets fund (Thu close)58.05Down 5.79 percent vs Wednesday's 61.62
Brent Friday screen99.86 dollars1.57 dollars above the Thursday settlement, as of 0222 GMT. Not a settlement
WTI Friday screen91.62 dollars1.10 dollars above the Thursday settlement, as of 0222 GMT. Not a settlement
10 year screen (Fri Asia)4.838 percentThe wrap's morning print. Not the index in the score
Kospi (morning)Down more than 8 percent, then a circuit breakerAn open session print. Last down 7 percent after trading resumed. Not a close
Nikkei (morning)Down 6 percentAn open session print in the Friday wrap. Not a close
Taiwan benchmark (morning)Down more than 8 percentAn open session print in the same wrap. Not a close

Top five drivers

United States The label flipped back

The relief day was given back.

SignalWednesday's rally did not survive Thursday's cash session.

The S&P 500 fell 4.36 percent, to 7,353.73. The Nasdaq Composite fell 5.52 percent, to 24,315.00, its deepest one day drop in 19 months, and Reuters said that close confirmed a correction, more than 10 percent under the 6 Oct record close. The Dow fell 3.44 percent, to 51,523.06. On this series the Russell 2000 fell 4.45 percent, to 2,729.89. Reuters said the selloff took 3 trillion dollars off S&P 500 companies, and 2.5 trillion dollars off the Nasdaq 100. The volatility index closed at 28.18, up 11.57 points from 16.61. Reuters said it jumped as much as 11.75 points, to an intraday 28.36, before that close. The close is the number in the score. That close is why the score rose from 35 to 51, and why the label left NEUTRAL for CAUTION.

The story is the buildout, not a new seat in Congress. Democrats already hold both chambers, and the new majority still takes office in January. Reuters tied Thursday's drop to fear that the sweep slows data center construction and the AI spending that had carried the tape. The same close story said Cleveland Fed president Beth Hammack and Richmond Fed president Thomas Barkin, speaking Thursday, favored a gradual path of further rate increases. That is a comment, not a decision.

Asia did not wait for the US open. In the Friday morning wrap, the Kospi fell more than 8 percent and triggered a circuit breaker, and was last down 7 percent after trading resumed. The Nikkei was down 6 percent. Taiwan was down more than 8 percent. European futures were down 1 percent. Those sessions were still open.

Macro ImpactYesterday the trap was buying the Dow because the label had flipped to NEUTRAL. Today the trap is buying the same tape because it fell 4.36 percent. A correction on the Nasdaq is a description of the drop from the 6 Oct close. It is not a schedule for a bounce, and it is not a reason to sell the last of the crude hedge. The labor print is still ahead of the open. A morning screen in Seoul is not Thursday's cash close, and it is not a second US settlement.

PositioningDo not add equity risk on the break. The label changed back. The sleeves do not. Wait for today's labor print, not for the Kospi screen.

Key SourcesReuters, 5 Nov, https://www.reuters.com/business/sp-500-futures-steady-after-midterm-rally-nasdaq-lags-chip-weakness-2026-11-05/ ; Reuters, 5 Nov, https://www.reuters.com/business/wall-street-fear-gauge-jumps-most-since-liberation-day-ai-trade-stumbles-2026-11-05/ ; Reuters, 6 Nov, https://www.reuters.com/business/energy/global-markets-global-markets-2026-11-05/
Iran Oil settled higher

The strait did not become a deal.

SignalThursday's settlement is the number. The continuous last after it is not a second close. The Friday screen is not a third.

Brent settled 3.67 dollars higher, at 98.29 dollars, 3.88 percent above Wednesday's 94.62. WTI settled 2.40 dollars higher, at 90.52 dollars, 2.72 percent above Wednesday's 88.12. Reuters called that a reversal from Wednesday, when both benchmarks fell more than 8 percent to the lowest settlement since 31 Aug (Mon). The Friday wrap, as of 0222 GMT, had January Brent 1.57 dollars higher, at 99.86 dollars, and WTI 1.10 dollars higher, at 91.62 dollars. Those screens sit above Thursday's settlements. They are not a new settlement. On this series the continuous Brent last was 100.25 dollars, and the continuous WTI last was 91.89 dollars. Those lasts are not the settlements either.

The bounce was the water, not a signed opening. Iran reported three more tankers damaged in the Strait of Hormuz on Thursday. The Revolutionary Guards said two tankers and a tugboat caught fire after using routes Tehran had not authorized. UKMTO figures in the Reuters story show at least five vessels reporting incidents since Sunday. That pace is close to October, when the agency said 35 vessels were hit. Qatar has said the United States and Iran are reviewing proposals. Neither side has announced a breakthrough. Two sources told Reuters they still believe the president is likely to resume strikes. Eurasia Group cut the chance of renewed US strikes to 60 percent from 65 percent, cut the chance of a deal to 10 percent from 20 percent, and raised the chance of a continued standoff to 30 percent from 15 percent.

The week is still a large drop if Friday's screen holds. Reuters said January Brent was on track to fall 12 percent this week, and WTI 12.1 percent, after the earlier plunge. ANZ said flows through the strait are under 60 percent of capacity, and that Iran is unlikely to give that control up. That is a strategist's note, not a measured cargo count in this report.

The oil fund rose 1.93 percent, to 148.21. The energy fund fell 2.98 percent, to 61.63. The fund and the settlement did not tell the same story. The settlement is still the crude sleeve.

Macro ImpactYesterday the trap was selling the sleeve into an 8.98 dollar drop on talks that had not broken through. Today the trap is adding because the settlement rose 3.67 dollars on tanker hits that have not closed the strait, and have not opened it. A higher price, with no deal signed and the new Congress not seated until January, is the premium coming back into a market that is still down hard on the week. Selling the last of the sleeve into the bounce gives away the hedge. Adding because a screen at 0222 GMT is higher is the other trap.

PositioningHold a residual crude sleeve. Do not add it, and do not sell the last of it. No airlines and no transports. A settlement of 98.29 dollars is higher than Wednesday. It is not a signed reopening.

Key SourcesReuters, 5 Nov, https://www.reuters.com/business/energy/oil-falls-fourth-day-expectations-lower-risk-iran-war-escalation-2026-11-05/ ; Reuters, 6 Nov, https://www.reuters.com/business/energy/oil-set-sharp-weekly-drop-middle-east-supply-concerns-provide-floor-2026-11-06/ ; Reuters, 5 Nov, https://www.reuters.com/world/middle-east/tankers-hit-hormuz-iran-keeps-up-pressure-after-us-vote-2026-11-05/

United States Yields eased on the close

Today's labor print is not in.

SignalThere is no new US rate decision this morning. The October meeting already happened, on 27 Oct (Tue) and 28 Oct (Wed). The Fed left the policy rate in a range of 3.75 to 4.00 percent. The next meeting is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections.

The yield index in the score closed Thursday at 4.837 percent, down 5.7 basis points from 4.894. The 5 year index closed at 4.608 percent, down 8.1 basis points. The 30 year index closed at 5.251 percent, down 3.1 basis points. The 3 month index closed at 3.987 percent, down 3.8 basis points. The Friday wrap had the 10 year screen at 4.838 percent. That screen is not the index in the score.

The labor print in front of December is still today's employment situation. The Bureau of Labor Statistics calendar has the October report on 6 Nov (Fri) at 8:30 a.m. Eastern. A Reuters poll looks for nonfarm payrolls to rise 65,000, with unemployment unchanged at 4.2 percent. September payrolls rose 29,000. The print is not in.

Hammack said policy will need to move to a restrictive stance, and that she prefers more frequent smaller steps. Barkin said inflation is too high and that a gradual pace makes sense. Reuters said futures still price a December increase, around 70 percent, down from more than 80 percent on Wednesday. That is a market probability in the story, not a vote.

The long bond fund rose 0.21 percent, to 81.93. That agrees with the lower yield index. It is one session, and a small one next to the equity drop. The dollar index on this series closed at 101.719, up 0.21 percent from Wednesday's 101.510.

Macro ImpactA lower yield close is the haven bid, written into Thursday's bond market, while two Fed presidents were still arguing for higher rates. Covering the short because the index fell 5.7 basis points is how you buy a bond into a labor print that is not out, and into a December meeting that still carries a hike probability in the story. Adding to the short because the level is still 4.837 percent is a chase into a tape that just bought duration for shelter. The level is not easy. The day is not a new Fed path.

PositioningStay underweight long duration. Do not cover, and do not add to the short, before the print. Hold cash and short bills over the long end.

Key SourcesReuters, 5 Nov, https://www.reuters.com/business/feds-hammack-favors-gradual-rate-hike-path-lower-inflation-2026-11-05/ ; Bureau of Labor Statistics calendar, October employment situation on 6 Nov 2026 at 8:30 a.m. Eastern, https://www.bls.gov/schedule/news_release/empsit.htm ; Federal Reserve calendar, December 8 to 9, 2026, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm

United States The chips led the drop

Asia is still selling them.

SignalThursday's cash close was a buildout unwind, not a broad story with one hole in it.

On this series the semiconductor fund fell 11.21 percent, to 447.73. The Philadelphia semiconductor index fell 12.25 percent, to 9,011.14. Reuters called that a drop of more than 12 percent, to a six month low. Nvidia fell 9.26 percent on this series, to 181.60. Reuters said it dropped more than 9 percent. AMD fell 17.26 percent on this series, to 404.40. Reuters said it slumped 17 percent. The Nasdaq 100 fell 6.4 percent in the Reuters account. On this series the Nasdaq 100 fund fell 6.49 percent, to 647.05.

The cash rich names fell too, just less. Microsoft fell 3.58 percent on this series, to 535.93. Reuters called that 3.6 percent. Meta fell 3.96 percent on this series, to 605.08. Reuters said it slid 4 percent. Amazon fell 2.19 percent on this series, and Alphabet fell 2.20 percent. Reuters said each dropped 2.2 percent. CoreWeave dropped almost 10 percent, in the same story, and its five year credit default spread widened to a record.

UBS estimated that around 30 percent of expected US data center capacity additions in 2028 could be at risk from construction pauses. That is an estimate, not a permit count. The Friday Asia wrap said the same trade was still on. Samsung was down nearly 10 percent, SK Hynix 11.7 percent, Kioxia 14 percent, and TSMC 8.5 percent. SoftBank was down 11 percent. Those are morning prints.

Macro ImpactWednesday the tape bought the companies that write the checks and sold the companies that pour the concrete. Thursday it sold both, and it sold the suppliers harder. Buying the semiconductor fund because it fell 11.21 percent is how a break becomes a position you have to defend while Asia is still in the same trade and the labor print is not in. Shorting the cash rich names into a 3 to 4 percent drop, after they rose hard on Wednesday, is the other side of the same chase.

PositioningDo not buy the semiconductor fund, and do not short the cash rich names into the break. Cash still beats a chase into a morning screen.

Key SourcesReuters, 5 Nov, https://www.reuters.com/legal/transactional/ai-data-center-stocks-slip-democratic-sweep-clouds-expansion-plans-2026-11-05/ ; Reuters, 5 Nov, https://www.reuters.com/business/sp-500-futures-steady-after-midterm-rally-nasdaq-lags-chip-weakness-2026-11-05/ ; Reuters, 6 Nov, https://www.reuters.com/business/energy/global-markets-global-markets-2026-11-05/

United Kingdom The Bank of England hiked

That vote does not replace today's US print.

SignalThe decision is in. The poll is no longer the story.

The Monetary Policy Committee voted 8 to 1 to raise Bank Rate by 0.25 percentage points, to 4 percent. Catherine Mann preferred a rise of 0.50 percentage points, to 4.25 percent. The Bank of England said UK inflation was 3.5 percent in September and is expected to rise to around 5 percent by the middle of next year. The next decision is 17 Dec (Thu). That date sits outside this two week list.

The hike was the last large developed central bank move that yesterday's note was waiting on. It does not change the US book this morning. The US labor print is still ahead. The October consumer price index is on 10 Nov (Tue) at 8:30 a.m. Eastern. The producer price index for October is on 13 Nov (Fri) at 8:30 a.m. Eastern. Neither is in.

China is the other temptation, and it is not a package. The large cap China fund rose 1.01 percent, to 34.94. The emerging markets fund fell 5.79 percent, to 58.05. Those are Thursday's closes. The emerging markets fund sold off with the global tape. The China fund did not. One divergent close is not a growth program. The gold fund rose 0.81 percent, to 375.49. A small up day does not make the fund the new hedge.

Macro ImpactFading the Bank of England after the vote is how you trade a finished decision as if it were still a poll. Adding UK duration because oil is off the week's high is how you trade a commodity screen as the inflation path the Bank just marked up. Adding China cyclicals because one fund rose 1.01 percent treats a split tape as a policy turn. The US book does not need either bet this morning. It needs to not buy the break, and not cover its own bond, before the labor print.

PositioningNo new UK rate position after the vote. Stay underweight China cyclicals. Do not buy the gold fund as a replacement for the crude sleeve.

Key SourcesBank of England, Monetary Policy Summary, November 2026, https://www.bankofengland.co.uk/monetary-policy-summary-and-minutes/2026/november-2026 ; Bank of England, current interest rate, next decision 17 Dec 2026, https://www.bankofengland.co.uk/explainers/current-interest-rate ; Bureau of Labor Statistics, October CPI on 10 Nov 2026 and October PPI on 13 Nov 2026, both at 8:30 a.m. Eastern, https://www.bls.gov/schedule/news_release/cpi.htm

Risk matrix

The method note is above, in the markets bar. Cells below are the Thursday fact, or the wire after it. Asia screens are not in this table.

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreCAUTIONHighDays35 NEUTRAL to 51 CAUTION. The label flipped back. It did not reach 61
US equitiesSharply lowerHighDaysS&P 500 down 4.36 percent to 7,353.73. Nasdaq down 5.52 percent
VolatilitySharply higherHighDays28.18, up 11.57 points. This is the flip inside the score
CongressCalled, not seatedHighWeeksBoth chambers already called. The new majority sits in January
Brent settlementHigher on the dayHighDaysSettled at 98.29 dollars, up 3.67 dollars from 94.62
WTI settlementHigher on the dayHighDaysSettled at 90.52 dollars, up 2.40 dollars from 88.12
StraitAttacks ongoing, deal not signedHighWeeksFresh tanker hits. Talks have not produced a breakthrough
ChipsSharply lowerHighDaysSemiconductor fund down 11.21 percent. Asia suppliers were still falling this morning
US 10 year indexLowerHighDaysScore uses 4.837 percent, down 5.7 basis points. The Asia screen was 4.838
LaborNot inHighHoursOctober employment situation at 8:30 a.m. Eastern today. A poll looks for 65,000
Fed pathHike talk, no new voteMediumWeeksPolicy rate still 3.75 to 4.00 percent. December meeting is 8 Dec and 9 Dec
Bank of EnglandHike is inHighDoneBank Rate to 4 percent, 8 to 1. Next decision 17 Dec
Gold fundSlightly higherMediumDaysUp 0.81 percent to 375.49. The hedge question did not change hands
Emerging markets fundSharply lowerHighDaysDown 5.79 percent to 58.05. The China fund rose 1.01 percent
DollarSlightly higherMediumDays101.719, up 0.21 percent vs Wednesday's 101.510 on this series

Portfolio

Sleeve Stance Rationale
CrudeHold a residual. Do not add. Do not sell the last of itBrent settled 3.67 dollars higher, at 98.29. No deal is signed. The new Congress sits in January
Energy equities (XLE)Do not addThe fund fell 2.98 percent while crude settled higher. That split is not a dip to buy before the labor print
Oil fund (USO)Hold with the sleeveUp 1.93 percent yesterday. The fund is not the settlement, and it is not a new entry
Long duration (TLT)Underweight. Do not coverYield index at 4.837 percent. Today's labor print is not in
Cash and short billsOverweight versus the long endPaid to wait through today's labor print, Tuesday's inflation print, and a Congress that is not seated
Semiconductors (SMH)Do not buy the dip. Do not short the cash rich namesThe fund fell 11.21 percent. Asia was still selling the suppliers this morning
Gold (GLD)No new entryThe fund rose 0.81 percent. A small up day does not replace the crude sleeve
Airlines and transportsNoThe settlement is higher. The opening is not signed
China cyclicalsUnderweightThe large cap fund rose 1.01 percent. The emerging markets fund fell 5.79 percent. That is not a package
Broad equityDo not addThe S&P 500 fell 4.36 percent. The label flip back to CAUTION is not a buy

The next two weeks

Date Event Why it matters
6 Nov (Fri)Employment situation for October, 8:30 a.m. EasternThe print is not in. September was a 29,000 gain. A poll looks for 65,000 in October, with unemployment at 4.2 percent
10 Nov (Tue)Consumer price index for October, 8:30 a.m. EasternThe inflation print that sits with the labor print in front of December. Not in
13 Nov (Fri)Producer price index for October, 8:30 a.m. EasternThe wholesale price print in the same window. Not in

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections. The Bank of England's next decision also sits beyond this list, on 17 Dec (Thu). The new Congress is not seated for either date.

Scorecard

51 of 100 sits in CAUTION. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse53Down from 54. The 10 year index closed Thursday at 4.837 percent. The backup eased again. The level is still not easy
CB Elasticity41Down from 43. The 5 year index closed at 4.608 percent. December is still the meeting with projections
Flow Pressure73Up from 23. This is the flip. The volatility index closed at 28.18, up 11.57 points. The high yield fund fell 0.31 percent
Narrative Coherence31Up from 10. The drop was coherent. Stocks fell with volatility. Oil and the chip complex did not tell the same story
Composite51CAUTION

The label flipped back. Yesterday was 35, NEUTRAL. Today is 51, CAUTION. RISK-ON is below 30. RISK-OFF is 61 and above. A higher score means more stress. The move was the volatility jump, not a new Fed path. Going into today's labor print at 51 is a hold on the sleeves you have, not a signal to buy the break, and not a signal to dump the crude hedge.

Data through the 5 Nov 2026 US close. This is a Friday morning note, before the US cash open. Asia is open. There is no Friday US settlement in this note.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.