OverWise

Market regime, November 5

Top five drivers, the risk matrix and the book for Thursday, November 05, 2026.

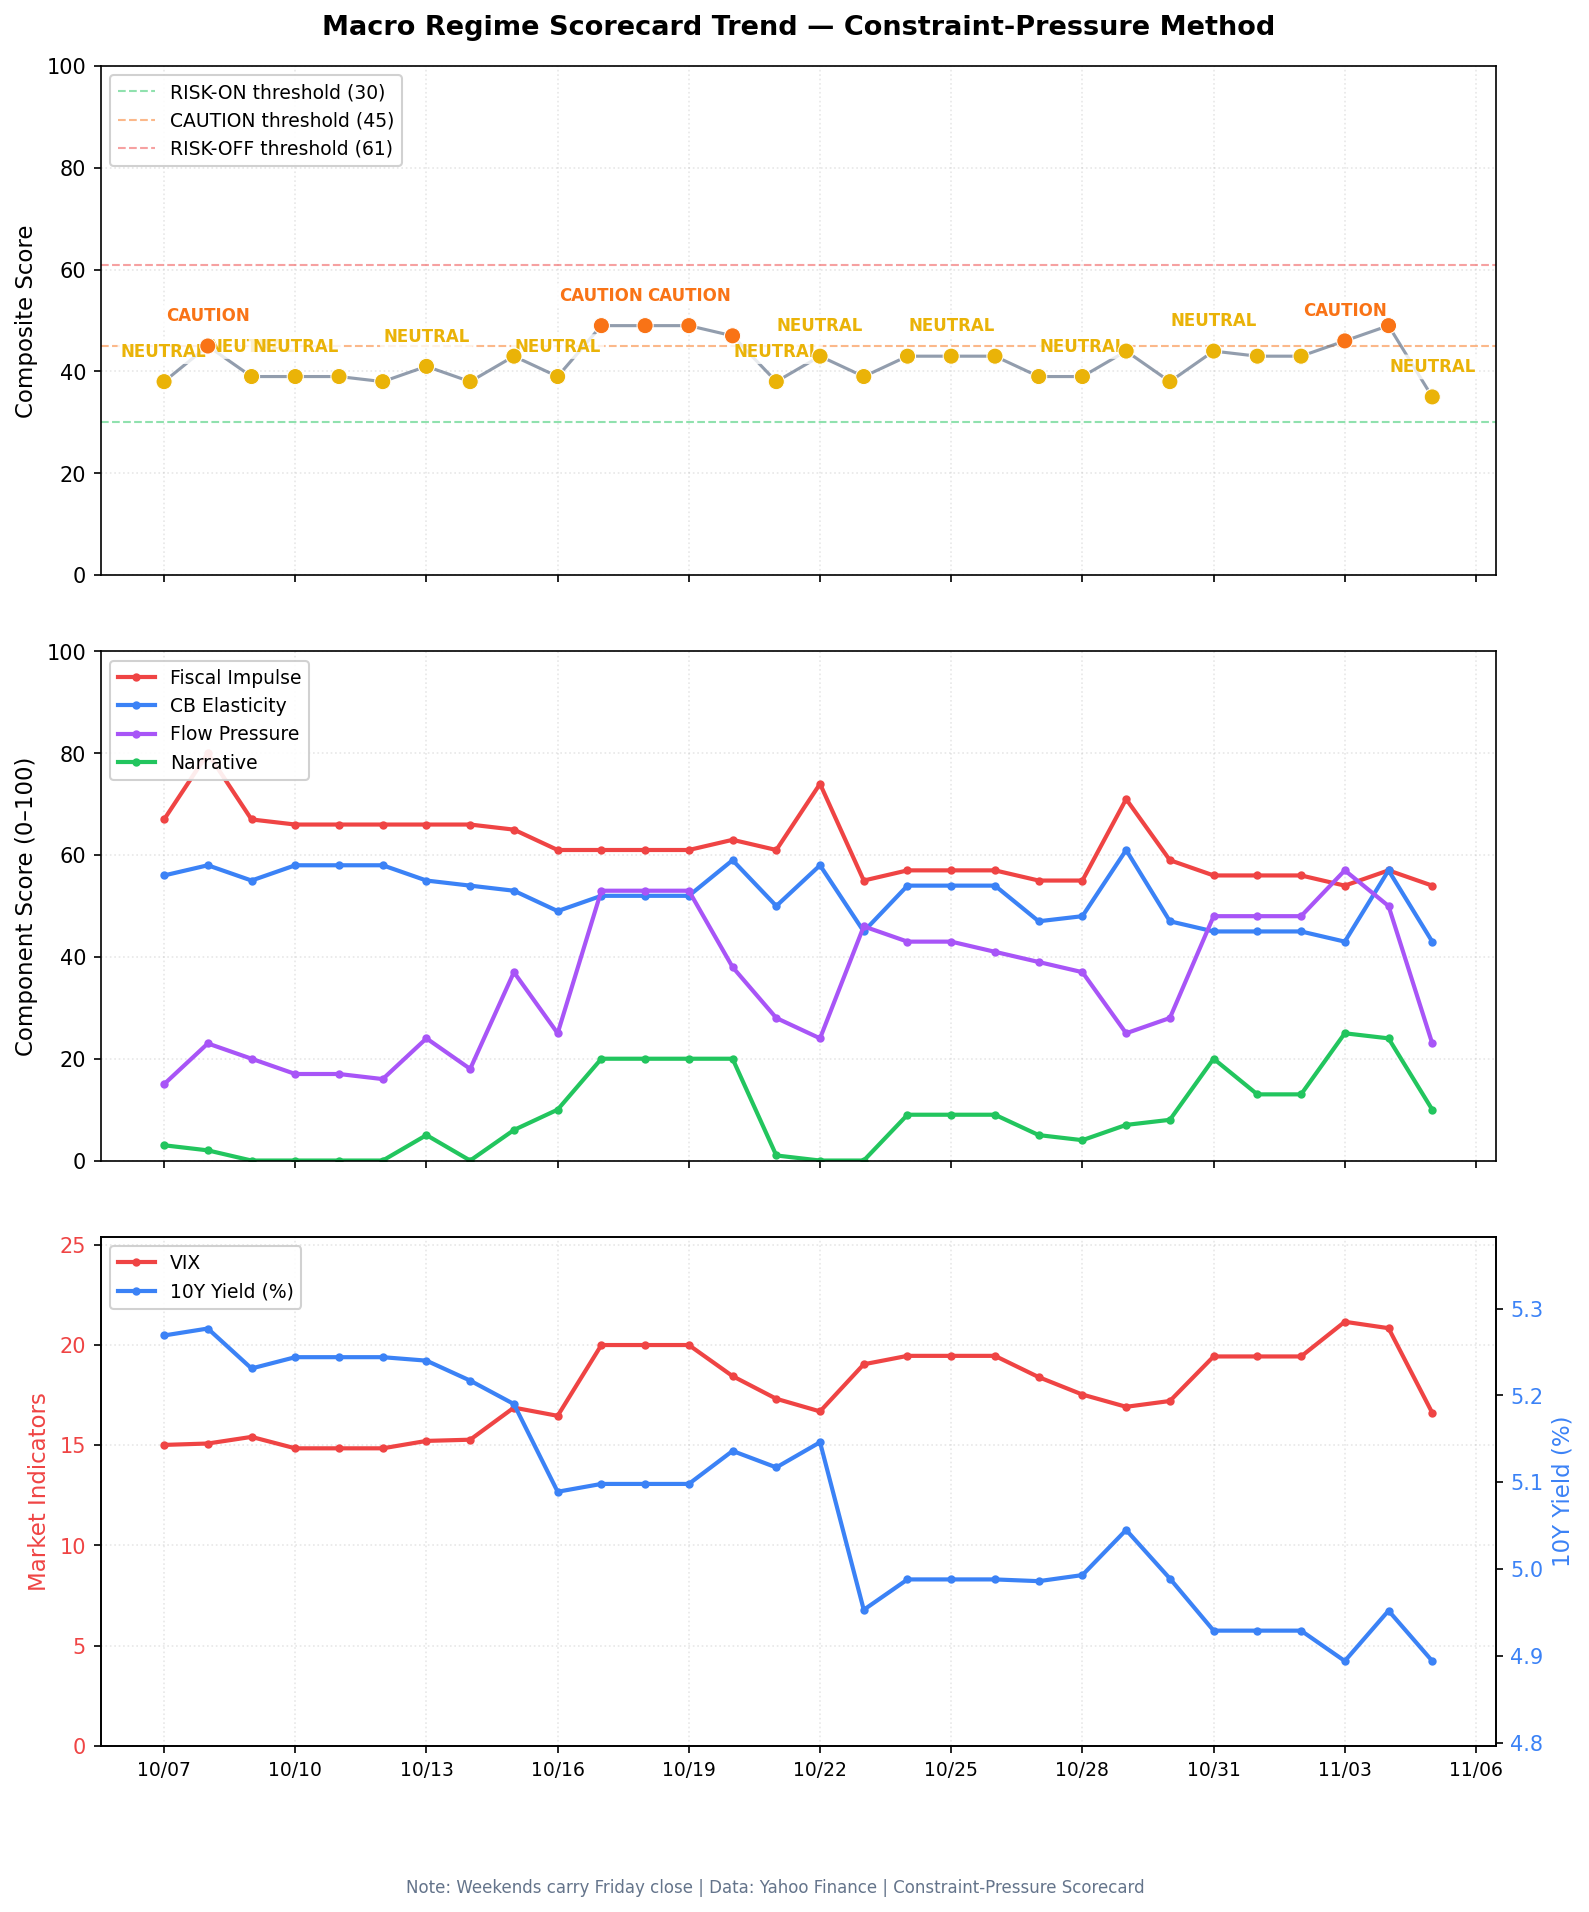
This is a regime flip. The score is 35 of 100. The label is NEUTRAL. Yesterday the score was 49, and the label was CAUTION. NEUTRAL runs from 30 to 44. CAUTION runs from 45 to 60. RISK-ON is below 30. RISK-OFF starts at 61. The score fell because volatility collapsed. Yields eased. The new fact is the count, and the new Congress is not seated until January.

Read the five drivers
Before the US open Next review 6 Nov 2026 (Fri)

Regime score

35of 100

NEUTRAL

10 under CAUTION, 5 over the RISK-ON line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Wednesday's US cash close is in. This note is Thursday morning, before the US cash open. Asia is open. Equity, yield, dollar, and fund rows are Wednesday's close. The oil rows are Wednesday's settlement. Prints after that close are screens.

The book does not chase the flip. Hold a residual crude sleeve. Do not sell the last of it, and do not add it. Do not buy the Dow because the label changed. Do not cover the bond before Friday's labor print. A seated majority is not a majority that has taken the oath, and an Asia screen is not Wednesday's close.

In short

MARKET REGIME, Nov 5 (Thu)

Signal. Neutral. Hold energy. Do not chase. Score 35 of 100.

  1. United States Democrats took both chambers. Do not chase the rally.
  2. Iran Oil settled sharply lower. The war is not over.
  3. United States Yields fell yesterday. Do not cover the bond.
  4. United States Chips fell while the Dow jumped. Do not buy them.
  5. United Kingdom Britain may hike today. The vote is not in.

Markets bar

Equity, yield, dollar, and fund rows are Wednesday's cash close, against Tuesday. Brent and WTI rows are the settlement in the oil story. The continuous last on this series is a different print, and it is not in the table. Asia rows and the Thursday oil screen are open prints in the morning wrap. This note does not cite oil or gold volume, and it does not treat a gold futures last as a settlement.

The continuous Brent last on this series was 93.69 dollars. The continuous WTI last was 86.86 dollars. Those are not Wednesday's settlements. The settlements are 94.62 and 88.12. The continuous gold last on this series was 4,144.90, up 5.19 percent from Tuesday's 3,940.40 on the same series. The gold row in the table is the fund.

Asset Level Change
S&P 500 (Wed close)7,688.62Up 119.70 points, or 1.58 percent, vs Tuesday's 7,568.92
Nasdaq Composite (Wed close)25,736.51Up 364.50 points, or 1.44 percent, vs Tuesday's 25,372.01
Dow (Wed close)53,356.12Up 1,569.40 points, or 3.03 percent, vs Tuesday's 51,786.72
Russell 2000 (Wed close)2,856.95Up 1.58 percent vs Tuesday's 2,812.45
VIX (Wed close)16.61Down 4.22 points vs Tuesday's 20.83. The score uses this close
US 10 year yield index (Wed close)4.894 percentDown 5.8 basis points vs Tuesday's 4.952. This is the index in the score
5 year yield index (Wed close)4.689 percentDown 5.4 basis points vs Tuesday's 4.743
30 year yield index (Wed close)5.282 percentDown 4.2 basis points vs Tuesday's 5.324
3 month yield index (Wed close)4.025 percentUnchanged vs Tuesday
Brent January settlement94.62 dollarsDown 8.98 dollars, or 8.67 percent, from Tuesday's 103.60. The oil story called that the lowest settle since 31 Aug (Mon)
WTI December settlement88.12 dollarsDown 7.97 dollars, or 8.29 percent, from Tuesday's 96.09
Dollar index (Wed close)101.258Down 0.60 percent vs Tuesday's 101.87 on this series
Gold fund (Wed close)372.49Up 3.68 percent vs Tuesday's 359.26
Energy fund (Wed close)63.52Down 4.74 percent vs Tuesday's 66.68
Oil fund (Wed close)145.41Down 8.07 percent vs Tuesday's 158.17. The fund is not the settlement
Semiconductor fund (Wed close)504.27Down 2.75 percent vs Tuesday's 518.52
Long bond fund (Wed close)81.76Up 0.80 percent vs Tuesday's 81.11
High yield fund (Wed close)77.52Up 0.70 percent vs Tuesday's 76.98
Investment grade fund (Wed close)104.50Up 0.75 percent vs Tuesday's 103.72
Large cap China fund (Wed close)34.59Up 4.22 percent vs Tuesday's 33.19
Emerging markets fund (Wed close)61.62Up 0.85 percent vs Tuesday's 61.10
Brent Thursday screen93.65 dollars97 cents under the Wednesday settlement, as of 0211 GMT. Not a settlement
WTI Thursday screen86.98 dollars1.14 dollars under the Wednesday settlement, as of 0211 GMT. Not a settlement
10 year screen (Thu Tokyo)4.87 percentThe wrap's early Tokyo print, after a 6 basis point drop overnight in that story. Not the index in the score
Kospi (morning)Down 4 percentAn open session print in the Thursday wrap. Not a close
Taiwan benchmark (morning)Down 1.8 percentAn open session print in the same wrap. Not a close
Nikkei (morning)Down 0.5 percentAn open session print in the same wrap. Not a close

Top five drivers

United States The label flipped

Both chambers changed hands. Neither is seated.

SignalThe vote is no longer a projection. The new Congress is still not in the chair.

Reuters reported on Wednesday that Democrats seized control of both the Senate and the House, in a voter backlash against the war and the cost of living. The Senate majority is at least 54 to 44. Alaska and Mississippi were still uncalled as of that story, so the majority could grow to 56 to 44. Democrats gained at least 30 House seats. Texas fell, including the governorship. President Trump accepted the result and said he has the veto. The new majority takes office in January. Republicans still hold the reins through the lame duck, and Reuters said the funding fight was postponed to an 11 Dec (Fri) deadline.

The tape traded the result, not the oath. The Dow rose 1,569.40 points, or 3.03 percent, to 53,356.12. CNBC called that the best day since 9 Apr 2025. The S&P 500 rose 1.58 percent, to 7,688.62. The Nasdaq Composite rose 1.44 percent, to 25,736.51. The Russell 2000 rose 1.58 percent, to 2,856.95. The volatility index closed at 16.61, down 4.22 points from 20.83. That close is why the score fell from 49 to 35, and why the label left CAUTION for NEUTRAL.

Asia did not buy the whole tape. In the Thursday morning wrap, the Kospi was down 4 percent, Taiwan was down 1.8 percent, and the Nikkei was down 0.5 percent. Those sessions were still open.

Macro ImpactYesterday the trap was trading a House projection as a fiscal regime. Today the trap is trading a finished count as a seated Congress. A Democratic House and Senate can slow new spending and put the buildout under more scrutiny, but that power starts in January. The lame duck can still pass a funding bill. Buying the Dow because the score is 35 gives away Friday's labor print, Tuesday's inflation print, and a Congress that has not taken the oath. Selling because Asia chips are down gives away Wednesday's cash close for a morning screen.

PositioningDo not add equity risk on the flip. The label changed. The sleeves do not. Wait for Friday's labor print, not for the Kospi screen.

Key SourcesReuters, 4 Nov, https://www.reuters.com/legal/government/democrats-seize-congress-sweeping-midterm-repudiation-trump-2026-11-04/ ; Reuters, 4 Nov, https://www.reuters.com/business/us-stock-index-futures-steady-democrats-seize-congress-2026-11-04/ ; CNBC, 4 Nov, https://www.cnbc.com/2026/11/03/stock-market-today-live-updates.html ; Reuters, 5 Nov, https://www.reuters.com/business/energy/global-markets-global-markets-2026-11-05/
Iran Oil settled sharply lower

The strait did not become a deal.

SignalWednesday's settlement is the number. The continuous last after it is not a second close. The Thursday screen is not a third.

Brent for January delivery settled 8.98 dollars lower, at 94.62 dollars. That is 8.67 percent under Tuesday's settlement of 103.60. WTI for December delivery settled 7.97 dollars lower, at 88.12 dollars, 8.29 percent under Tuesday's 96.09. Xinhua and CNBC carried those settles. Reuters said both benchmarks tumbled by more than 8 percent and settled at their lowest since 31 Aug (Mon).

The drop was the election, not a signed opening. Vice President JD Vance wrote that the reason Republicans lost is the war. Two sources close to Gulf government circles told Reuters that a full-scale assault now looks less likely, and that a weakened White House has a greater incentive to seek a deal. Andy Lipow told CNBC the elections are leading the market to conclude that a deal is now more likely. Bob McNally said the odds still favor military escalation, and that the president is unlikely to walk away from the nuclear aim after paying this political price. Mukesh Sahdev said the incoming Congress does not take office until January, so US policy options have not immediately changed.

The physical picture is not a shut strait, and it is not a surplus you can see in the stocks. Reuters said crude shipments through the Strait of Hormuz have recovered to close to pre-war levels, at a higher cost. JPMorgan said the market returned to a surplus of 1.1 million barrels a day in September and 1.4 million in October. The same Reuters story said the Energy Information Administration reported that US crude, gasoline, and distillate inventories all fell last week, with demand at its highest in a year. Sahdev said commercial inventories in major consuming countries are near their lowest in 15 years. A recovered flow and a thin stock can both be true.

As of 0211 GMT on Thursday, Reuters had the Brent screen 97 cents lower, at 93.65 dollars, and the WTI screen 1.14 dollars lower, at 86.98 dollars. Those screens sit under Wednesday's settlements. They are not a new settlement. On this series the continuous Brent last was 93.69 dollars, and the continuous WTI last was 86.86 dollars. Those lasts are not the settlements either.

The energy fund fell 4.74 percent, to 63.52. The oil fund fell 8.07 percent, to 145.41. Reuters said the energy sector index fell 4.8 percent. The fund and the settlement moved together this time. The settlement is still the crude sleeve.

Macro ImpactYesterday the trap was selling the sleeve into a 1.17 dollar settle on talks that had not broken through. Today the settle is 8.98 dollars lower, and the trap is the same trade for a larger number. A cheaper price, with no deal signed and the new Congress not seated until January, is the premium leaving before the opening. Selling the last of the sleeve into that gives away the hedge. Adding because a fourth down morning looks washed out is the other trap. A screen at 0211 GMT is not a lost cargo, and it is not a bottom.

PositioningHold a residual crude sleeve. Do not add it, and do not sell the last of it. No airlines and no transports. A settlement of 94.62 dollars is lower. It is not a signed reopening.

Key SourcesXinhua, 5 Nov, https://english.news.cn/20261105/7f27da3589b64d618f24ad7ebcd6f039/c.html ; CNBC, 4 Nov, https://www.cnbc.com/2026/11/04/oil-price-iran-war-us-election-strait-hormuz.html ; Reuters, 5 Nov, https://www.reuters.com/business/energy/oil-falls-fourth-day-expectations-lower-risk-iran-war-escalation-2026-11-05/

United States Yields eased on the close

Friday's labor print is not in.

SignalThere is no new US rate decision this morning. The October meeting already happened, on 27 Oct (Tue) and 28 Oct (Wed). The Fed left the policy rate in a range of 3.75 to 4.00 percent. The next meeting is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections.

The yield index in the score closed Wednesday at 4.894 percent, down 5.8 basis points from 4.952. The 5 year index closed at 4.689 percent, down 5.4 basis points. The 30 year index closed at 5.282 percent, down 4.2 basis points. The 3 month index was unchanged at 4.025 percent. The Thursday wrap had the 10 year screen at 4.87 percent in early Tokyo, after a 6 basis point drop overnight in that story. That screen is not the index in the score.

The labor print in front of December is still Friday's employment situation, not Wednesday's private survey. ADP said private employment rose by 86,000 in October, after a downwardly revised 86,000 in September. Economists polled by Reuters had looked for 69,000. The Bureau of Labor Statistics calendar has the October employment situation on 6 Nov (Fri) at 8:30 a.m. Eastern. A Reuters survey looks for nonfarm payrolls to rise 65,000, with unemployment unchanged at 4.2 percent. September payrolls rose 29,000. Reuters said in the same story that ADP has been a poor gauge of the official private payrolls estimate.

The long bond fund rose 0.80 percent, to 81.76. That agrees with the lower yield index. It is one session. The dollar index on this series closed at 101.258, down 0.60 percent from Tuesday's 101.87. The wrap's euro print, 1.1273 dollars per euro, is a different quote.

Macro ImpactA lower yield close is the election bid for bonds, written into Wednesday's settlement of the bond market. Covering the short because the index fell 5.8 basis points is how you buy a bond into Friday's labor print and Tuesday's inflation print. Adding to the short because the level is still 4.894 percent is a chase into a number the oil drop has started to soften, if the drop sticks. The level is not easy. The day is not a new Fed path.

PositioningStay underweight long duration. Do not cover, and do not add to the short, before Friday. Hold cash and short bills over the long end.

Key SourcesReuters, 4 Nov, https://www.reuters.com/business/us-private-payrolls-rise-october-adp-says-2026-11-04/ ; Bureau of Labor Statistics calendar, October employment situation on 6 Nov 2026 at 8:30 a.m. Eastern, https://www.bls.gov/schedule/news_release/empsit.htm ; Federal Reserve calendar, December 8 to 9, 2026, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm ; Reuters, 5 Nov, https://www.reuters.com/business/energy/global-markets-global-markets-2026-11-05/

United States The Dow bought the sweep

The chips did not.

SignalWednesday's cash close was a broad relief rally with a hole in the buildout.

All but two S&P sectors rose, in the markets story. Consumer discretionary jumped 4.3 percent. Energy fell 4.8 percent. Those are sector indexes, not the funds in the table.

The split inside technology is the point. Microsoft rose 6.68 percent on this series, to 555.80. Reuters called that 6.7 percent. Amazon rose 6.1 percent, Alphabet gained 3.2 percent, and Meta rose 1.4 percent, in the same story. On this series Meta rose 1.44 percent, to 630.00, and Apple rose 5.31 percent, to 349.51. Nvidia fell 3.17 percent on this series, to 200.13. The markets story called that drop about 3 percent. AMD rose 1.01 percent on this series, to 488.78, and Reuters said it rose 1 percent after the forecast. The semiconductor fund fell 2.75 percent, to 504.27. The Philadelphia semiconductor index dropped 3.1 percent in the close story, to a six-month low.

Data center operators fell harder. Hut 8 was down 23 percent, IREN was off 11 percent, Core Scientific was down 10 percent, and Applied Digital was lower by 6.7 percent. Reuters tied that to Democratic gains in Texas and Georgia, where opposition to the buildout has been growing, and to the expectation that a slower buildout eases the cash demand on the large buyers while it pressures the suppliers. The Thursday Asia wrap said the same trade was still on. Chip and equipment shares were sliding, and the Kospi was down 4 percent in morning trade.

Macro ImpactThe open question is still whether the spending turns into cash, and now whether a new Congress slows the buildings. Wednesday's cash session answered it by buying the companies that write the checks and selling the companies that pour the concrete. Buying the semiconductor fund because the Dow rose 3.03 percent is how a relief day becomes a position you have to defend when Asia is already selling the suppliers and Friday's labor print is not in.

PositioningDo not buy the semiconductor fund, and do not short the cash-rich names. The split already happened. Cash still beats a chase into a morning screen.

Key SourcesReuters, 4 Nov, https://www.reuters.com/business/us-stock-index-futures-steady-democrats-seize-congress-2026-11-04/ ; Reuters, 4 Nov, https://www.reuters.com/business/media-telecom/democrat-sweep-adds-new-twist-markets-iran-ai-debt-worries-2026-11-04/ ; Reuters, 5 Nov, https://www.reuters.com/business/energy/global-markets-global-markets-2026-11-05/

United Kingdom The Bank of England is expected to hike today

The oil drop is not that vote.

SignalThere is no Bank of England decision in this note. The meeting is today, and the poll is not the vote.

Economists polled by Reuters expect the Monetary Policy Committee to vote 7 to 2 to raise Bank Rate to 4 percent from 3.75 percent. The decision is due at 1200 GMT, with the press conference at 1230 GMT. It would be the first increase since August 2023, and the first change since a cut last December. At the September meeting the hold was 6 to 3. UK inflation in September was 3.5 percent, above the 2 percent target. Reuters said the bank is the last big developed central bank not to have raised rates in this cycle, and that the drawn out Iran conflict is what made a hold harder. That story still framed oil around 100 dollars a barrel.

That framing is already behind Wednesday's settlement. Brent January settled at 94.62 dollars. A hike priced on a 100 dollar oil story meets a market that just took 8.67 percent out of the January contract. The vote can still be a hike. The oil print does not cancel the meeting.

China is the other temptation, and it is not a package. The large cap China fund rose 4.22 percent, to 34.59. The emerging markets fund rose 0.85 percent, to 61.62. Those are Wednesday's closes. They came with the global relief, on the day a previously announced buyback relending rate cut to 1 percent took effect. That cut supports share prices. It does not put money into factories. The foreign exchange reserve ratio hike to 6 percent from 4 percent is still on the calendar for 15 Nov (Sun). The gold fund rose 3.68 percent, to 372.49. One relief day does not make the fund the new hedge.

Macro ImpactFading the Bank of England because oil settled lower is how you trade Wednesday's commodity close as Thursday's policy vote. Adding UK duration because the poll says 7 to 2 is how you trade a survey as a decision. Adding China cyclicals because the fund rose 4.22 percent treats a global relief day, and a stock tool, as a growth tool. The US book does not need either bet this morning. It needs to not cover its own bond before Friday.

PositioningNo new UK rate position before 1200 GMT. Stay underweight China cyclicals. Do not buy the gold fund as a replacement for the crude sleeve.

Key SourcesReuters, 5 Nov, https://www.reuters.com/world/uk/bank-england-poised-hike-rates-first-time-3-years-2026-11-05/ ; Xinhua, 4 Nov, https://english.news.cn/20261104/04d091f0d7254e9eae0e8b22e2026650/c.html

Risk matrix

The method note is above, in the markets bar. Cells below are the Wednesday fact, or the wire after it. Asia screens are not in this table.

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreNEUTRALHighDays49 CAUTION to 35 NEUTRAL. The label flipped. It did not reach 30
CongressCalled, not seatedHighWeeksSenate at least 54 to 44. House gain at least 30 seats. Seated in January
Brent settlementSharply lowerHighDaysJanuary settled at 94.62 dollars, down 8.98 dollars from 103.60
WTI settlementSharply lowerHighDaysDecember settled at 88.12 dollars, down 7.97 dollars from 96.09
StraitFlow back, deal not signedHighWeeksShipments near pre-war levels, at a higher cost. Policy options unchanged until January
DowSharply higherHighDaysUp 3.03 percent to 53,356.12
S&P 500HigherHighDaysUp 1.58 percent to 7,688.62
VolatilityLowerHighDays16.61, down 4.22 points. This is the flip inside the score
US 10 year indexLowerHighDaysScore uses 4.894 percent, down 5.8 basis points. The Tokyo screen was 4.87
ChipsLower in cashHighDaysFund down 2.75 percent. Cash-rich names rose. Asia suppliers were sliding this morning
LaborPrivate survey firmerHighDaysADP rose 86,000. The official October print is Friday. Not in
Bank of EnglandHike expected, not inMediumHoursPoll looks for 4 percent from 3.75 percent. Decision at 1200 GMT
Gold fundHigher on the dayMediumDaysUp 3.68 percent to 372.49. The war hedge question did not change hands
China fundsHigher with the tapeMediumDaysLarge cap China fund up 4.22 percent. No new spending package
DollarLower on the closeMediumDays101.258, down 0.60 percent vs Tuesday's 101.87 on this series

Portfolio

Sleeve Stance Rationale
CrudeHold a residual. Do not add. Do not sell the last of itJanuary Brent settled 8.98 dollars lower. No deal is signed. The new Congress sits in January
Energy equities (XLE)Do not addThe fund fell 4.74 percent with the settle. That is not a dip to buy before Friday
Oil fund (USO)Hold with the sleeveDown 8.07 percent yesterday. The fund is not the settlement, and it is not a new entry
Long duration (TLT)Underweight. Do not coverYield index at 4.894 percent. Friday's labor print is not in
Cash and short billsOverweight versus the long endPaid to wait through Friday's labor print, Tuesday's inflation print, and a Congress that is not seated
Semiconductors (SMH)Do not chase. Do not short the cash-rich namesThe fund fell 2.75 percent. Microsoft rose. Asia was selling the suppliers this morning
Gold (GLD)No new entryThe fund rose 3.68 percent. One relief day does not replace the crude sleeve
Airlines and transportsNoThe settlement is lower. The opening is not signed
China cyclicalsUnderweightThe fund rose 4.22 percent with the tape. A buyback rate cut is not spending
Broad equityDo not addThe Dow rose 3.03 percent on a count that is not a seated Congress. The label flip is not a buy

The next two weeks

Date Event Why it matters
5 Nov (Thu)Bank of England decision, 1200 GMT. Press conference 1230 GMTThe poll looks for a hike to 4 percent from 3.75 percent. The vote is not in
6 Nov (Fri)Employment situation for October, 8:30 a.m. EasternThe print is not in. September was a 29,000 gain, with unemployment at 4.2 percent. A survey looks for 65,000 in October
10 Nov (Tue)Consumer price index for October, 8:30 a.m. EasternThe inflation print that sits with the labor print in front of December. Not in
15 Nov (Sun)China foreign exchange reserve ratio rises to 6 percent from 4 percentA currency rule already announced. The buyback rate cut does not cancel it

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections. The funding deadline Reuters described also sits beyond this list, on 11 Dec (Fri). The new Congress is not seated for either date.

Scorecard

35 of 100 sits in NEUTRAL. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse54Down from 57. The 10 year index closed Wednesday at 4.894 percent. The backup eased. The level is still not easy
CB Elasticity43Down from 57. The 5 year index closed at 4.689 percent. December is still the meeting with projections
Flow Pressure23Down from 50. This is the flip. The volatility index closed at 16.61, down 4.22 points. The high yield fund rose 0.70 percent
Narrative Coherence10Down from 24. The count was clear enough for the Dow to rise with the Nasdaq. Oil and chips did not join that story
Composite35NEUTRAL

The label flipped. Yesterday was 49, CAUTION. Today is 35, NEUTRAL. RISK-ON is below 30. RISK-OFF is 61 and above. A higher score means more stress. The move was the volatility collapse, not a new Fed path. Going into Friday's labor print at 35 is a hold on the sleeves you have, not a signal to add risk, and not a signal to dump the crude hedge.

Data through the 4 Nov 2026 US close. This is a Thursday morning note, before the US cash open. Asia is open. There is no Thursday US settlement in this note.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.