OverWise

Market regime, November 4

Top five drivers, the risk matrix and the book for Wednesday, November 04, 2026.

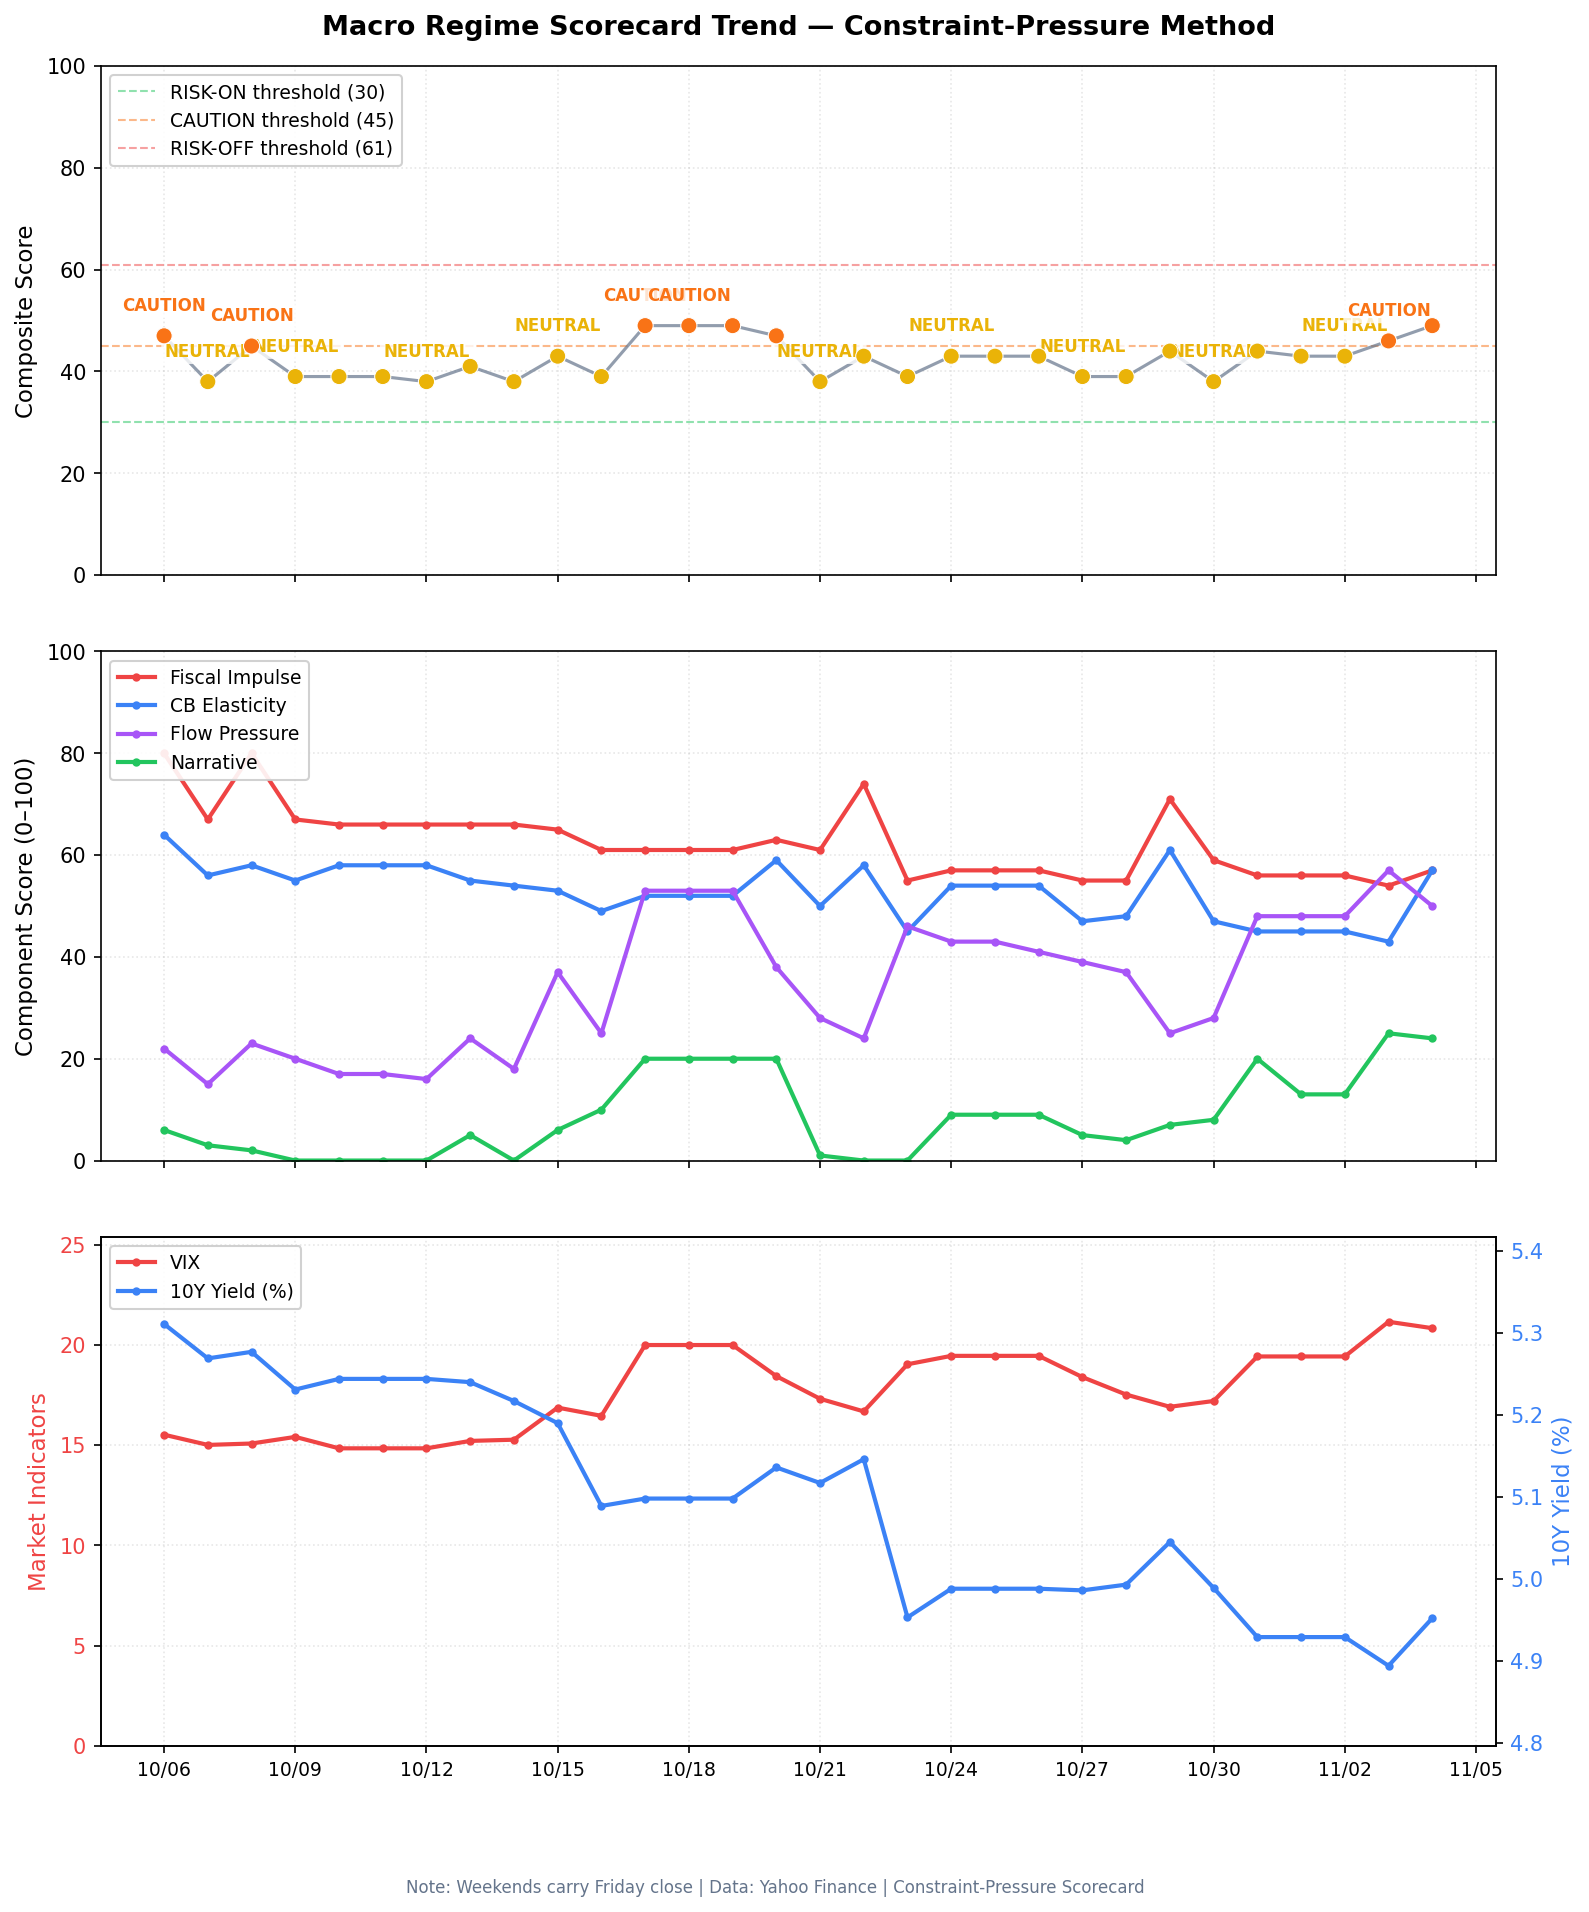
The label did not flip. The score is 49 of 100. The label is CAUTION. Yesterday the score was 46, and that was the day it crossed 45. CAUTION runs from 45 to 60. RISK-OFF starts at 61. RISK-ON is below 30. The score rose because yields rose. Volatility eased. The new fact is the count, and the count is not finished.

Read the five drivers
Before the US open Next review 5 Nov 2026 (Thu)

Regime score

49of 100

CAUTION

12 under RISK-OFF, 4 over the NEUTRAL line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Tuesday's US cash close is in. This note is Wednesday morning, before the US cash open. Asia is open. Japan has reopened after Tuesday's holiday, and that session is still running. Equity, yield, dollar, and fund rows are Tuesday's close. The oil rows are Tuesday's settlement. Prints after that close are screens.

The book does not change its sleeves. Hold the crude sleeve. Do not sell it, and do not add it. Do not buy the futures dip. Do not cover the bond. A projected House is not a seated majority, and an Asia screen is not Tuesday's close.

In short

MARKET REGIME, Nov 4 (Wed)

Signal. Caution. Hold energy. Do not chase. Score 49 of 100.

  1. United States US media project a Democratic House. Senate not called.
  2. United States Yields rose yesterday. Do not cover the bond.
  3. Iran Oil settled lower again. The strait is still shut.
  4. United States Chips bounced in cash. Do not chase the beat.
  5. China A China buyback rate cut is not growth spending.

Markets bar

Equity, yield, dollar, and fund rows are Tuesday's cash close, against Monday. Brent and WTI rows are the settlement in the oil story. The continuous last on this series is a different print, and it is not in the table. Asia rows are open session prints in the Wednesday wrap. This note does not cite oil or gold volume, and it does not treat a gold futures last as a settlement.

The continuous Brent last on this series was 103.07 dollars. The continuous WTI last was 95.53 dollars. Those are not Tuesday's settlements. The settlements are 103.60 and 96.09.

Asset Level Change
S&P 500 (Tue close)7,568.92Up 27.52 points, or 0.36 percent, vs Monday's 7,541.40
Nasdaq Composite (Tue close)25,372.01Up 207.70 points, or 0.83 percent, vs Monday's 25,164.31
Dow (Tue close)51,786.72Down 197.26 points, or 0.38 percent, vs Monday's 51,983.98
Russell 2000 (Tue close)2,812.45Up 0.23 percent vs Monday's 2,805.88
VIX (Tue close)20.83Down 0.32 points vs Monday's 21.15. Still above 20. The score uses this close
US 10 year yield index (Tue close)4.952 percentUp 5.8 basis points vs Monday's 4.894. This is the index in the score
5 year yield index (Tue close)4.743 percentUp 5.0 basis points vs Monday's 4.693
30 year yield index (Tue close)5.324 percentUp 5.5 basis points vs Monday's 5.269
3 month yield index (Tue close)4.025 percentUp 4.3 basis points vs Monday's 3.982
Brent Tuesday settlement103.60 dollarsDown 1.17 dollars from Monday's 104.77. The oil story called that about 1 percent, and the lowest close since 7 Oct
WTI Tuesday settlement96.09 dollarsDown 37 cents from Monday's 96.46. The oil story called that the lowest close since 14 Oct
Dollar index (Tue close)101.405Down 0.34 percent vs Monday's 101.75 on this series
Gold fund (Tue close)359.26Down 0.66 percent vs Monday's 361.65
Energy fund (Tue close)66.68Down 0.85 percent vs Monday's 67.25
Oil fund (Tue close)158.17Up 0.83 percent vs Monday's 156.87. The fund is not the settlement
Semiconductor fund (Tue close)518.52Up 2.01 percent vs Monday's 508.31
Long bond fund (Tue close)81.11Down 0.76 percent vs Monday's 81.73
High yield fund (Tue close)76.98Up 0.12 percent vs Monday's 76.89
Investment grade fund (Tue close)103.72Up 0.01 percent vs Monday's 103.71
S&P futures (Wed wrap)Down 0.8 percentA screen in the Singapore wrap. Not a cash close
Nasdaq futures (Wed wrap)Down 1.8 percentA screen in the same wrap. Not a cash close
10 year screen (Wed wrap)4.906 percentDown 6 basis points in that story. Not the index in the score
Nikkei (open session)Down 3 percentJapan returned from Tuesday's holiday. The session was still open
Kospi (open session)Down 1.6 percentAn open session print in the same wrap. Not a close

Top five drivers

United States The House is projected

The Senate is not called.

SignalThe vote has produced projections. It has not produced a finished Congress.

US media projected on Tuesday that Democrats were on track to win the House. Reuters reported that several networks made that projection, and that most of the tight races were still uncalled. So far, Democrats have picked up four House seats. Reuters said they can afford to lose one existing seat and still take the 435 member chamber. Four pickups are not a seated majority.

The Senate is the open question. Annie Andrews won South Carolina, according to media projections, the first Democratic Senate win there since 1998, in a state the president carried by nearly 18 points in 2024. Roy Cooper flipped the Republican held seat in North Carolina. Those two wins are two of the four net gains Democrats need to overturn a 53 to 47 Republican majority. Jon Ossoff held Georgia. Chris Pappas held New Hampshire. Alaska, Iowa, Michigan, Maine, Ohio, and Texas were still uncounted in the races that decide the chamber. A board is not those states.

The tape after the close traded the projection, not the unfinished count. In the Wednesday wrap, S&P futures were down 0.8 percent and Nasdaq futures were down 1.8 percent. The 10 year screen in that story was 4.906 percent, down 6 basis points there. The dollar index in the same story was 0.32 percent lower, at 101.39. Japan's Nikkei was down 3 percent after the holiday, Korea was down 1.6 percent, and the broad Asia index outside Japan was down 0.5 percent. Those Asia cash sessions were still open. None of those prints replaces Tuesday's close.

Prediction markets were pricing a Democratic sweep, with more than 1.48 billion dollars wagered on the election, in the same wrap. A wager is not a seat.

Macro ImpactYesterday the trap was trading a poll as a count. Today the trap is trading a House projection as a fiscal regime. A House that changes hands can slow new spending and put the buildout under more scrutiny. That is a story for next year, and it is not in the price as a fact until the tight races are called and the Senate is known. Selling the open because Nasdaq futures are down 1.8 percent gives away Tuesday's cash close for a screen. Buying the dip because a sweep is "in the boards" does the same trade in the other direction. The Senate still needs two more net seats, and those states are not in.

PositioningDo not add equity risk on the projection. Do not cut the crude sleeve because a board likes one outcome in Washington. Wait for the Senate, not for the futures screen.

Key SourcesReuters, 3 Nov, https://www.reuters.com/world/us/trump-faces-midterm-verdict-with-control-congress-stake-2026-11-03/ ; Reuters, 4 Nov, https://www.reuters.com/world/us/democrats-projected-win-majority-control-us-house-us-media-project-2026-11-04/ ; Reuters, 4 Nov, https://www.reuters.com/world/us/democrat-annie-andrews-wins-us-senate-seat-south-carolina-upset-2026-11-04/ ; Reuters, 4 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-04/
United States Yields rose on the close

The Asia screen gave some back.

SignalThere is no new US rate decision this morning. The October meeting already happened, on 27 Oct (Tue) and 28 Oct (Wed). The Fed left the policy rate in a range of 3.75 to 4.00 percent and said inflation remains elevated. The next meeting is 8 Dec (Tue) and 9 Dec (Wed). It is still the meeting with projections.

The yield index in the score closed Tuesday at 4.952 percent, up 5.8 basis points from 4.894. The 5 year index closed at 4.743 percent, up 5.0 basis points. The 30 year index closed at 5.324 percent, up 5.5 basis points. The 3 month index closed at 4.025 percent, up 4.3 basis points. These are indexes. The Wednesday wrap had the 10 year screen at 4.906 percent, down 6 basis points in that story. That screen is the election bid for bonds. It is not the index in the score.

The labor print that sits in front of December is still not the payrolls. Tuesday's openings survey was for September. Job openings rose 333,000, to 7.523 million, against a forecast of 7.100 million. August was revised to 7.190 million. Layoffs fell 127,000, to 1.641 million, the lowest since March 2025. Quits rose 321,000, to 3.365 million. There were 1.06 openings for every unemployed person, up from 1.02 in August. Oxford Economics read that as a reason for the Fed to stay on inflation, and said it expects hikes in December and in March. A Reuters survey looks for October payrolls to rise 65,000, with unemployment unchanged at 4.2 percent. September payrolls rose 29,000, and unemployment was 4.2 percent. That is the last employment situation, from the Bureau of Labor Statistics. October is due 6 Nov (Fri) at 8:30 a.m. Eastern. Do not trade September openings as October payrolls.

The long bond fund fell 0.76 percent, to 81.11. That is the cash close, and it agrees with the higher yield index. The gold fund fell 0.66 percent, to 359.26. The bounce on Monday did not extend. The war hedge is still crude.

The dollar is not the signal. Tuesday's close on this series was 101.405, down 0.34 percent from Monday's 101.75. The wrap's 101.39 is a screen sitting on top of that close.

Macro ImpactA firm openings survey and a higher yield close are the hike case, written into Tuesday's settlement of the bond market. The Asia screen then bought bonds because the election started to look like a check on new spending. Covering the short because that screen fell 6 basis points is how you buy a bond into Friday's labor print, Tuesday's inflation print, and a December meeting that a named house still treats as a hike. Adding to the short because the cash index rose 5.8 basis points is a chase into a number the election screen has already started to fade, and into a Senate that is not called.

PositioningStay underweight long duration. Do not cover, and do not add to the short, before Friday's labor print. Hold cash and short bills over the long end. Do not buy the gold fund as the war hedge.

Key SourcesReuters, 3 Nov, https://www.reuters.com/business/us-job-openings-increase-sharply-september-2026-11-03/ ; Bureau of Labor Statistics, September employment situation, https://www.bls.gov/news.release/empsit.htm ; Bureau of Labor Statistics calendar, October employment situation on 6 Nov 2026 at 8:30 a.m. Eastern, https://www.bls.gov/schedule/news_release/empsit.htm ; Federal Reserve calendar, December 8 to 9, 2026, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm

Iran Oil settled lower again

The strait did not open.

SignalTuesday's settlement is the number. The continuous last after it is not a second close.

Brent settled 1.17 dollars lower, at 103.60 dollars. That is 1.17 dollars under Monday's settlement of 104.77. The oil story called the move about 1 percent, and the lowest close since 7 Oct (Wed). WTI settled 37 cents lower, at 96.09 dollars, under Monday's 96.46, and the story called that the lowest close since 14 Oct (Wed).

The drop was talks, not new barrels. A senior Iranian official told Reuters that Iran and the United States are still far from a deal. Qatar said both sides remain committed to mediation and are reviewing proposals. ING said it is too early to think the escalation risk has passed, and that a real sign of progress would mean more downside. The limited strikes on Qeshm Island were already in yesterday's note. Officials called them defensive, and not a return to major combat. They did not open the strait. The Wednesday wrap still described an effective blockade of the route that used to carry about 20 percent of global oil supply.

Aramco is working to expand a pipeline that goes around the strait, the chief executive said. A pipeline plan is not barrels this week. Russia, Ukraine, and the United States are due in Abu Dhabi on 10 Nov (Tue) and 11 Nov (Wed), the Kremlin confirmed. Russia hit Ukraine's power system ahead of those talks. That is a separate war track. It is not an Iran deal.

On this series the continuous Brent last was 103.07 dollars, and the continuous WTI last was 95.53 dollars. Those lasts are not the settlements above. The energy fund fell 0.85 percent, to 66.68. The oil fund rose 0.83 percent, to 158.17. The fund and the settlement did not move together. The settlement is the crude sleeve. The fund is not a reason to add, and it is not a reason to sell the commodity.

Macro ImpactYesterday the trap was selling the sleeve into a 7.63 percent settle on talks that had not broken through. Today the settle is only 1.17 dollars lower, and the trap is the same trade for a smaller number. A cheaper price, with the strait still shut and the talks still short of a deal, is the premium leaving before the opening. Selling the sleeve into that, on the morning the Senate is uncounted, gives away the hedge. Adding because futures in other markets are down is the other trap. An election screen is not a lost cargo.

PositioningHold the crude sleeve. Do not add it, and do not sell it. No airlines and no transports. A settlement of 103.60 dollars is still a high price while the strait is shut.

Key SourcesThe Business Times, 4 Nov, https://www.businesstimes.com.sg/companies-markets/energy-commodities/oil-prices-ease-settle-near-4-week-low-hopes-peace-talks-will-end-wars ; Reuters, 4 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-04/

United States Chips bounced in cash

The beat was after the bell.

SignalTuesday's cash close was a bounce inside a correction, not a new high.

The S&P 500 rose 0.36 percent, to 7,568.92. The Nasdaq Composite rose 0.83 percent, to 25,372.01. The Dow fell 0.38 percent, to 51,786.72. The Russell 2000 rose 0.23 percent, to 2,812.45. Six of the eleven sectors fell. Decliners led advancers in the S&P 500 by 1.6 to 1. The index was higher because tech was higher. The tape was not broad.

Nvidia rose 2.3 percent, to 206.69, after four down sessions. Microsoft rose 2.7 percent, to 520.99. Amazon rose 2.1 percent, to 250.69. The semiconductor fund rose 2.01 percent, to 518.52. Oracle rose 5.8 percent on this series, to 126.19, after Monday's drop on the stock sale and the bond sale. Apple fell 1.9 percent, to 331.90, after it warned that memory costs would keep pressing the holiday quarter margin. Those are Tuesday's closes.

AMD's cash close was before the release. On this series the stock rose 3.65 percent, to 483.90, and the markets story said it rose ahead of the release due after the bell. After the bell the company beat. Adjusted profit was 2.09 dollars a share, against 1.95. Revenue was 13.38 billion dollars, against 13.09 billion, and up 45 percent from a year earlier. That 45 percent is the year, not the day. Data center revenue rose 97 percent, to 8.55 billion dollars, against 8.20 billion. The December quarter revenue guide was about 17 billion dollars, plus or minus 3 percent, against 16.23 billion. The company said it expects revenue to rise more than 80 percent in 2027, against a 77 percent estimate, and that 80 percent of 2027 sales would come from data center chips. The gross margin guide was about 55 percent, in line with estimates and down from 56 percent in the quarter just reported. Client and gaming sales fell 8 percent, to 3.72 billion dollars, against 3.79 billion. The stock was up 8 percent in extended trading. That 8 percent is not Tuesday's close, and it is not Wednesday's open.

The funding did not stop. Meta raised 15 billion dollars in a five part bond sale to pay for the buildout. The 2031 notes were 3.25 billion dollars at a 5.85 percent coupon. The 2033 notes were 3.25 billion dollars at 6.25 percent. The company has said capital spending this year is 135 billion to 145 billion dollars. A beat in one chip report does not retire that bill.

The markets story said the Nasdaq 100 ended Monday more than 10 percent below its 6 Oct record, and that the S&P 500 is about 3 percent under that same record and still up more than 10 percent in 2026. Tuesday's bounce did not end that correction. Asia did not buy the beat. The wrap said stocks there reversed and traded lower, brushing off the AMD print, as the election screens took over.

Macro ImpactThe open question is still whether the spending turns into cash. Tuesday's cash session answered it the way a dip buyer answers it, by buying the chip names and selling the Dow. The report after the bell said demand in the data center is real. The bond sale said the buildout is still being borrowed. Buying the semiconductor fund because the Nasdaq rose, or because the extended print was up 8 percent, is how a bounce inside a correction becomes a position you have to defend when the Senate is still uncalled and Nasdaq futures are already down 1.8 percent.

PositioningDo not buy the semiconductor fund, and do not short it. The cash bounce already happened. The 8 percent is not the close. Cash still beats a chase into an unfinished count.

Key SourcesReuters, 3 Nov, https://www.reuters.com/business/retail-consumer/us-stock-futures-mixed-apple-slides-midterms-loom-2026-11-03/ ; Reuters, 3 Nov, https://www.reuters.com/business/amd-forecasts-quarterly-revenue-above-estimates-data-center-growth-accelerates-2026-11-03/ ; Reuters, 3 Nov, https://www.reuters.com/technology/meta-raises-15-billion-in-five-part-us-bond-sale-2026-11-03/

China A buyback rate cut is not a spending package

SignalChina did not announce a growth package overnight. It cheapened a stock tool, and a private survey said services slowed.

The central bank cut the interest rate on its relending facility for share buybacks and increased holdings by 25 basis points, to 1 percent, effective Wednesday. The facility covers 21 nationwide banks and five systemically important city commercial banks, at 100 percent of eligible loans, for one year. Banks have applied for more than 200 billion yuan, about 30 billion dollars, in quotas, after a meeting on Monday. That is support for share prices. It does not put money into factories.

The new activity print is private, and it is services. The RatingDog services gauge fell to 50.8 in October, from 51.6 in September. It is still above 50, and it is the weakest reading since July. Firms cut selling prices for a second month while input costs rose at the fastest pace in five months. Confidence was the weakest since July. This is not the official factory gauge. The standing official manufacturing print is still the late October figure, 49.3, below 50. This note has no newer official factory figure.

The currency rule from yesterday still stands. The foreign exchange deposit reserve ratio rises to 6 percent from 4 percent on 15 Nov (Sun). One tool supports stocks. The other drains dollar liquidity. Neither one is a spending package.

The equity funds did not price a China bid. The emerging markets fund closed at 61.10, flat on the day. The large cap China fund closed at 33.19, also flat. Those are Tuesday's closes, before the rate cut.

Macro ImpactA cheaper buyback loan can steady a tape. It does not restart the factories, and it does not offset a services slowdown or a reserve ratio hike that is still on the calendar. Adding China cyclicals because US oil settled 1.17 dollars lower, or because Beijing cut a stock facility rate, treats a market tool as a growth tool. Keeping the underweight is the same call as yesterday, with one new reason not to fade it and one new reason not to call it stimulus.

PositioningStay underweight China cyclicals. Do not add because the rate is 1 percent, and do not cover the underweight because the currency rule might steady the yuan.

Key SourcesXinhua, 4 Nov, https://english.news.cn/20261104/04d091f0d7254e9eae0e8b22e2026650/c.html ; China Daily, 4 Nov, https://www.chinadaily.com.cn/a/202611/04/WS6aea9f92e4b06d4aa0566feb.html ; Reuters, 4 Nov, https://www.reuters.com/business/finance/chinas-services-growth-slows-three-month-low-confidence-weakens-2026-11-04/

Risk matrix

The method note is above, in the markets bar. Cells below are the Tuesday fact, or the wire after it. Asia screens are not in this table.

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreCAUTIONHighDays46 to 49. Same label. Did not reach 61
HouseProjected, not seatedHighDaysMedia project a Democratic majority. Most tight races uncalled
SenateNot calledHighDaysTwo of four net gains in. SC and NC. The chamber is open
Brent settlementLowerHighDaysSettled at 103.60 dollars, down 1.17 dollars from 104.77
WTI settlementLowerHighDaysSettled at 96.09 dollars, down 37 cents from 96.46
StraitStill shutHighDaysTalks are not a deal. The blockade line in the wrap still stands
Nasdaq cashHigherHighDaysUp 0.83 percent to 25,372.01. Six sectors fell
S&P 500HigherHighDaysUp 0.36 percent to 7,568.92. The Dow fell 0.38 percent
Fed pathHike still aheadHigh1 to 3 monthsNo new US decision. Openings were firm. December is 8 Dec (Tue) and 9 Dec (Wed)
US 10 year indexHigherHigh1 to 3 monthsScore uses 4.952 percent, up 5.8 basis points. The Asia screen was 4.906
ChipsHigher in cashHighDaysFund up 2.01 percent. AMD's 8 percent is extended trading, not the close
LaborFirmer openingsHighWeeksSeptember openings 7.523 million. October payrolls are Friday. Not in
Gold fundLower on the dayMediumDaysDown 0.66 percent to 359.26. The war hedge is crude
China policyStock tool, not stimulusHighWeeksBuyback rate to 1 percent. Reserve ratio still rises 15 Nov (Sun)
DollarTuesday close onlyLowDays101.405, down 0.34 percent vs Monday's 101.75. Not the signal

Portfolio

Sleeve Stance Rationale
CrudeHold. Do not add. Do not sellThe settle is 1.17 dollars lower, the talks are not a deal, and the strait is shut. The sleeve is the hedge through an unfinished count
Energy equities (XLE)Do not addThe fund fell 0.85 percent yesterday with the settle. That is not a dip to buy before the Senate is called
Oil fund (USO)Hold with the sleeveUp 0.83 percent yesterday. The fund is not the settlement, and it is not a new entry
Long duration (TLT)Underweight. Do not coverYield index at 4.952 percent. Openings were firm. Friday's labor print is not in
Cash and short billsOverweight versus the long endPaid to wait through the count, Friday's labor print, and next Tuesday's inflation print
Semiconductors (SMH)Do not chase. Do not shortTuesday bounced the chips. AMD's extended print is not the cash close. Asia did not buy it
Gold (GLD)No new entryThe fund fell 0.66 percent on the day. The war hedge is crude
Airlines and transportsNoThe settlement is still high, and the strait is not open
China cyclicalsUnderweightA buyback rate cut is not spending. Services slowed. The reserve ratio hike is still ahead
Broad equityDo not addTuesday was a tech bounce with weak breadth. The Senate is not called, and futures are a screen

The next two weeks

Date Event Why it matters
4 Nov (Wed)Treasury quarterly refunding. China buyback relending rate cut takes effectRefunding sizes are not in this note. The rate cut to 1 percent is already announced. It is not a growth package
5 Nov (Thu)Productivity and costs, third quarter preliminary, 8:30 a.m. EasternA cost print, not the labor market
6 Nov (Fri)Employment situation for October, 8:30 a.m. EasternThe print is not in. September was a 29,000 gain, with unemployment at 4.2 percent. A survey looks for 65,000 in October. Do not cover before Friday
10 Nov (Tue)Consumer price index for October, 8:30 a.m. EasternThe inflation print that sits with the labor print in front of December. Not in
10 Nov (Tue) and 11 Nov (Wed)US, Ukraine, and Russia talks in Abu DhabiConfirmed by the Kremlin. A separate war track. Not an Iran deal
13 Nov (Fri)Producer price index for October, 8:30 a.m. EasternFactory gate prices. Not in
15 Nov (Sun)China foreign exchange reserve ratio rises to 6 percent from 4 percentA currency rule, not a spending package. The buyback rate cut does not cancel it

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections. Oxford Economics expects a hike then, and another in March. This note has no fresh futures odds.

Scorecard

49 of 100 sits in CAUTION. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse57Up from 54. The 10 year index closed Tuesday at 4.952 percent. The backup is the pressure. The level is still not easy
CB Elasticity57Up from 43. This is the move inside the score. The 5 year index closed at 4.743 percent. December is still the hike meeting in the economist survey
Flow Pressure50Down from 57. The volatility index closed at 20.83, still above 20, and 0.32 points under Monday. The high yield fund was barely higher
Narrative Coherence24Down from 25. The Dow fell and the Nasdaq rose. Oil settled on talks that are not a deal
Composite49CAUTION

The label did not flip. Yesterday was 46, CAUTION. Today is 49, still CAUTION. RISK-ON is below 30. RISK-OFF is 61 and above. A higher score means more stress. The move was the yield backup, not a volatility spike. Going into an unfinished count at 49 is a hold on the sleeves you have, not a signal to add risk, and not a signal to dump the crude hedge.

Data through the 3 Nov 2026 US close. This is a Wednesday morning note, before the US cash open. Asia is open. Japan has reopened after Tuesday's holiday. There is no Wednesday US settlement in this note.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.