OverWise

Market regime, November 3

Top five drivers, the risk matrix and the book for Tuesday, November 03, 2026.

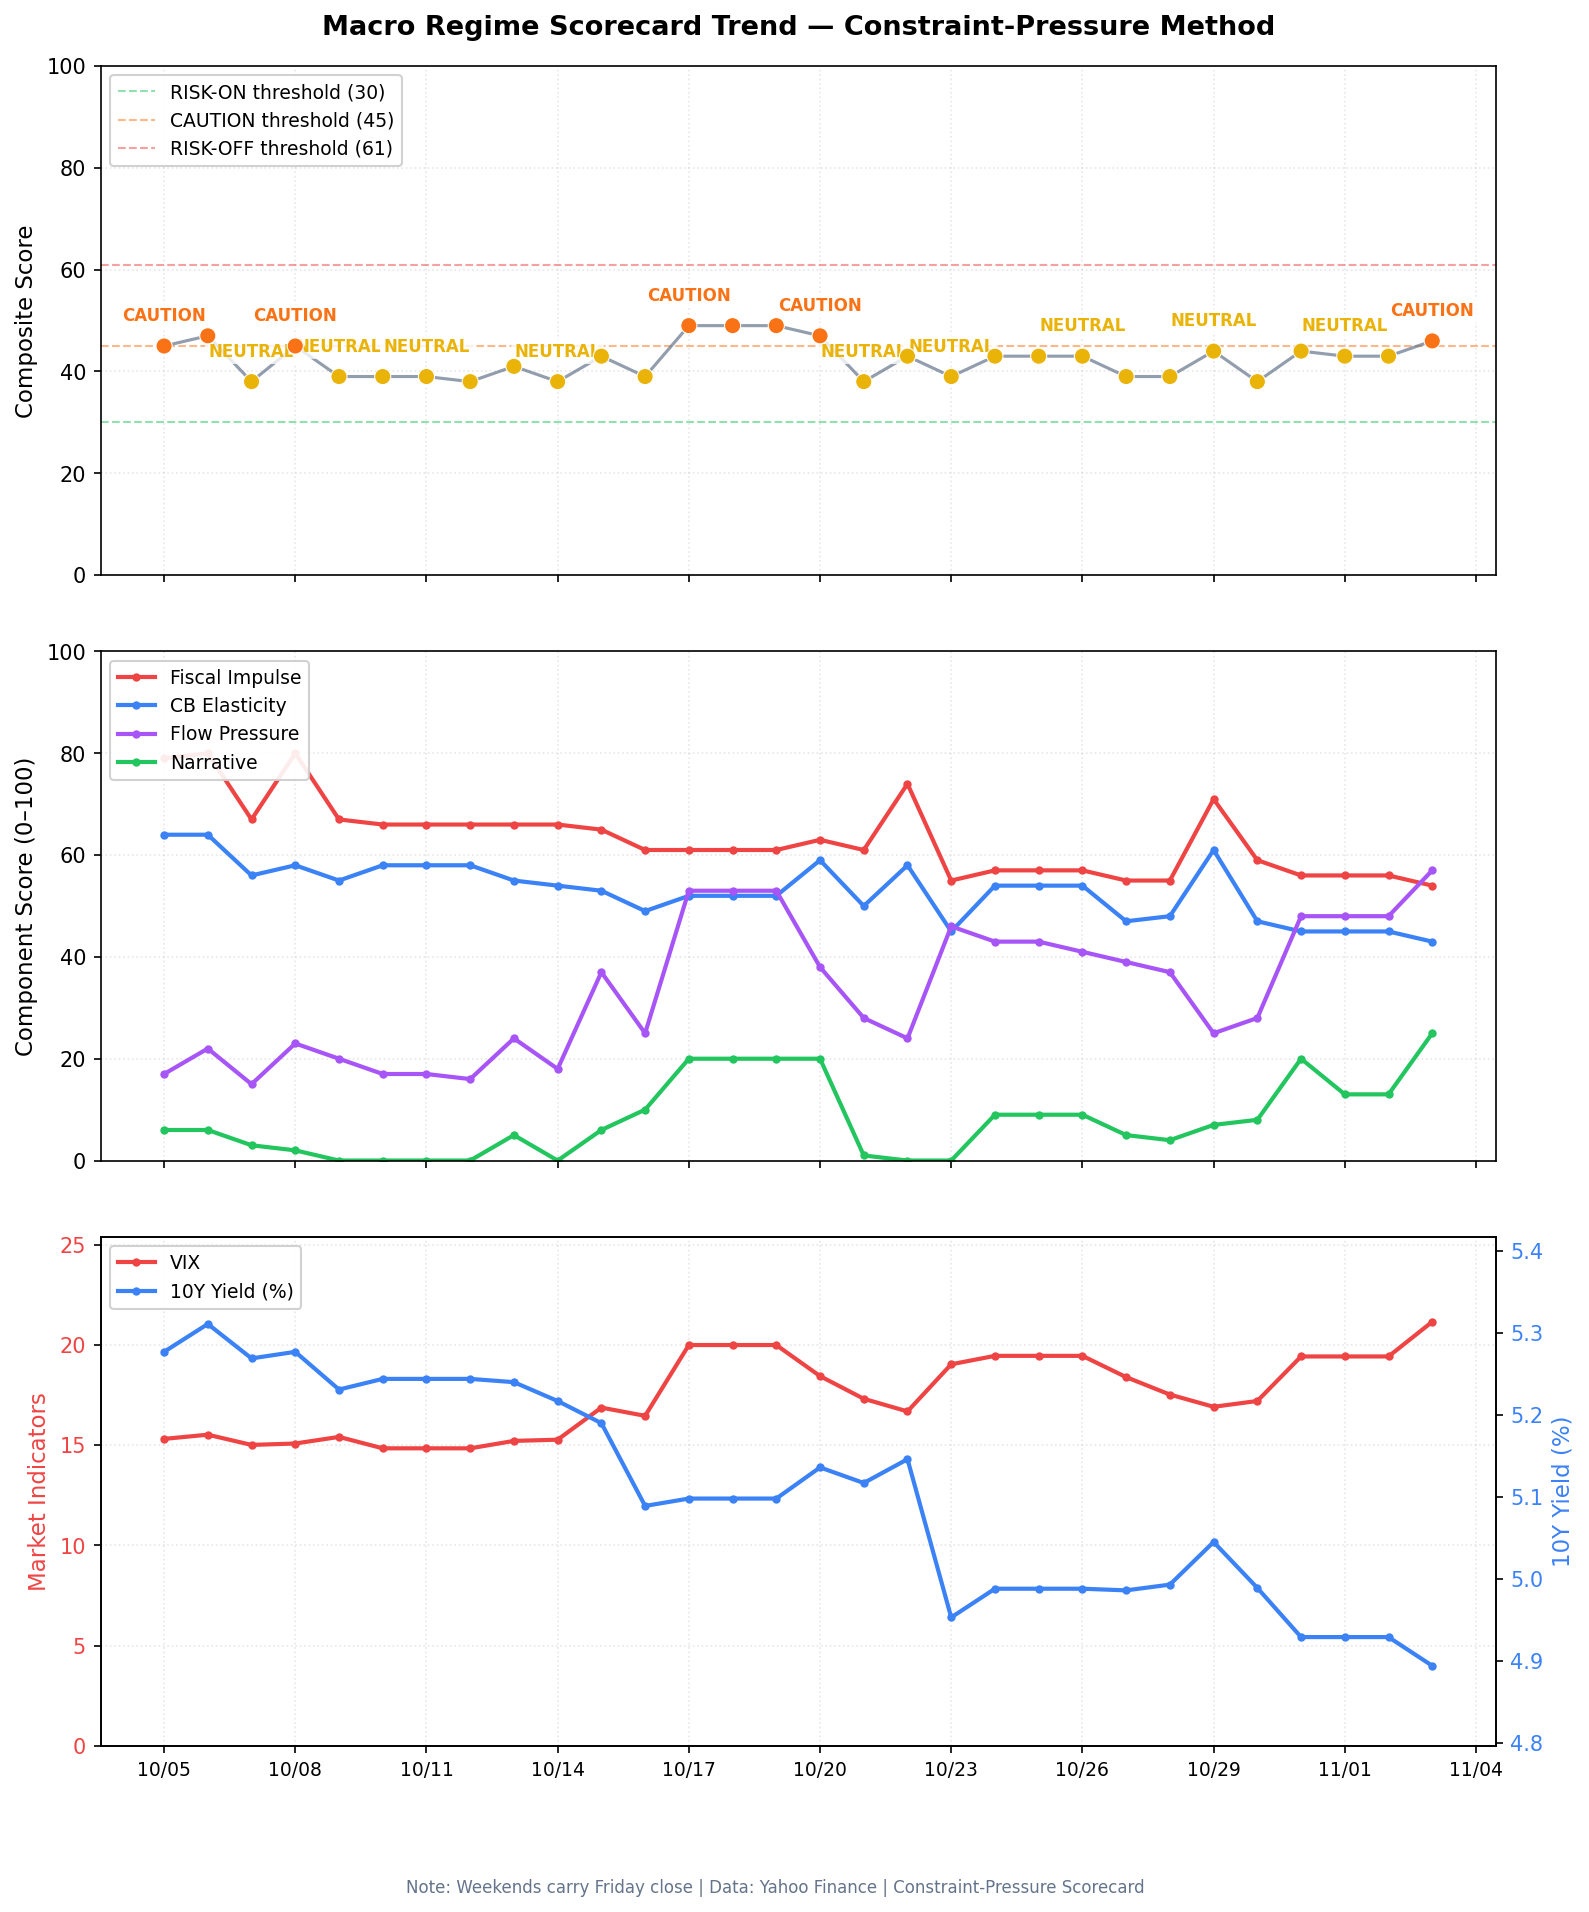
REGIME FLIP. The score is 46 of 100. The label is CAUTION. Yesterday the score was 43, and the label was NEUTRAL. CAUTION starts at 45. The score crossed that line. It did not reach RISK-OFF, which starts at 61. RISK-ON is below 30.

Read the five drivers
Before the US open Next review 4 Nov 2026 (Wed)

Regime score

46of 100

CAUTION

15 under RISK-OFF, 1 over the NEUTRAL line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

BINARY, not a new war. Monday's oil settlement took the war premium out of the price. After that close, US officials said strikes hit Qeshm Island. They called the strikes limited and defensive, and not a return to major combat. Talks ended with no breakthrough. The strait is not open. The vote is today. Do not trade Monday's settle as a peace, and do not trade the strike headline as a new campaign.

Monday's US cash close is in. This note is Tuesday morning, before the US cash open. Asia is open. Japan is closed for a holiday. Equity, yield, dollar, and fund rows are Monday's close. The oil settlement is Monday's. Prints after that close are screens.

The book changes in one place. The label flipped, so this is not yesterday's hold at 43. Hold the crude sleeve. Do not sell it, and do not add it. Do not cover the bond. Do not buy Monday's dip into a vote that has not been counted, or into a chip report that has not printed.

In short

MARKET REGIME, Nov 3 (Tue)

Signal. Caution. Hold energy. Do not chase. Score 46 of 100.

  1. Iran Oil settled lower Monday. A strike came after.
  2. United States Tech fell again yesterday. Do not chase it.
  3. United States The vote is today. A poll is not a seat.
  4. United States Yields eased Monday. Do not cover bonds.
  5. China A China currency rule is not stimulus.

Markets bar

Equity, yield, dollar, and fund rows are Monday's cash close, against Friday. Brent and WTI settlement rows are the oil story's Monday settles. The Asia rows under them are timed screens after that settle. This note does not cite oil or gold volume.

The continuous Brent bar on this series fell from 117.64 dollars on Friday to 104.68 dollars on Monday. That gap is the expired contract rolling off, plus the real settle. The settlement is 104.77 dollars, down 7.63 percent. Do not trade the continuous gap as an 11 percent crash in the active contract.

Asset Level Change
S&P 500 (Mon close)7,541.40Down 38.67 points, or 0.51 percent, vs Friday's 7,580.07
Nasdaq Composite (Mon close)25,164.36Down 272.64 points, or 1.07 percent, vs Friday's 25,437.00
Dow (Mon close)51,983.98Up 213.67 points, or 0.41 percent, vs Friday's 51,770.31
Russell 2000 (Mon close)2,805.88Down 0.21 percent vs Friday's 2,811.84
VIX (Mon close)21.15Up 1.73 points vs Friday's 19.42. The close is above 20. The score uses this close
US 10-year yield index (Mon close)4.894 percentDown 3.5 basis points vs Friday's 4.929. This is the index in the score
5-year yield index (Mon close)4.693 percentDown 2.8 basis points vs Friday's 4.721
30-year yield index (Mon close)5.269 percentDown 4.0 basis points vs Friday's 5.309
3-month yield index (Mon close)3.982 percentUp 0.9 basis points vs Friday's 3.973
Brent Monday settlement104.77 dollarsDown 8.66 dollars, or 7.63 percent, in the oil story. The story's reference is 113.43 dollars
WTI December Monday settlement96.46 dollarsDown 7.36 percent vs Friday's bar of 104.12 on this series. The gap is 7.66 dollars
Brent Asia screen (0104 GMT)105.25 dollarsUp 48 cents, or 0.5 percent, from the settlement, in the oil story. A screen
WTI Asia screen (0104 GMT)96.93 dollarsUp 47 cents, or 0.5 percent, from the settlement, in the oil story. A screen
Brent later Asia screen104.72 dollarsThe later wrap had it 0.1 percent lower. A screen, and not the same print as 105.25
Dollar index (Mon close)101.82Down 0.06 percent vs Friday's 101.88
Gold fund (Mon close)361.65Up 1.65 percent vs Friday's 355.78
Energy fund (Mon close)67.25Down 3.96 percent vs Friday's 70.02
Oil fund (Mon close)156.87Down 7.08 percent vs Friday's 168.83
Semiconductor fund (Mon close)508.31Down 2.71 percent vs Friday's 522.49
Long bond fund (Mon close)81.73Down 0.13 percent vs Friday's 81.84
High yield fund (Mon close)76.89Down 0.70 percent vs Friday's 77.43
Investment grade fund (Mon close)103.71Down 0.54 percent vs Friday's 104.27

Top five drivers

Iran Oil settled lower

The strait did not open.

SignalMonday's settlement is the number. The screens after it are not a second close.

Brent settled 8.66 dollars lower, or 7.63 percent, at 104.77 dollars. Adding that drop back gives 113.43 dollars, the story's reference price, which is the active contract's Friday level. The continuous series printed a Friday bar of 117.64 dollars. That bar is the expired contract. The Monday continuous print of 104.68 dollars is a later last, not a second settlement.

December WTI settled at 96.46 dollars, down 7.36 percent from Friday's bar of 104.12 on this series. The cash gap is 7.66 dollars. The markets story and this series agree on the settle.

The drop was the talks, not new barrels. Iranian negotiators had already left Doha. Tehran said contacts continue, after days with Qatari mediators ended in altered proposals and no breakthrough. A condensed plan could be implemented in two days, in the foreign ministry's words. That plan would still have the United States lift a port blockade before Iran reopens the strait. A two day plan is not an opening. Iran still wants its conditions met before any nuclear talks. Iranian sources in the same story said they thought a new US attack was more likely than a deal.

After the settlement, the wires changed. A US official said strikes hit Qeshm Island, in the Strait of Hormuz. The official called them limited, and not a resumption of major combat. Another official called them defensive, against surface to air missiles fired at US assets. Iranian state media had reported explosions on the island. The command did not comment. By 0104 GMT the oil story had Brent 48 cents higher, at 105.25 dollars, and US crude 47 cents higher, at 96.93 dollars. A later Asia wrap had Brent 0.1 percent lower, at 104.72 dollars. The early bounce and the later screen do not agree. Neither one replaces 104.77 dollars.

The president said a deal could happen, and he raised doubts about a threatened return to strikes. He has also said there would be no new attack before today's vote. A limited strike still happened on Monday. The vice president said he was optimistic about a negotiated settlement, and that kinetic options remain. Optimism is not an opening.

Macro ImpactYesterday the trap was selling the sleeve because the screen was cheaper. Today the cheaper price is a settlement, and the trap is the same trade for a worse reason. A 7.63 percent settle on talks that did not break through is the premium leaving before the strait opens. Selling the sleeve into that settle, on the morning of the vote, gives away the hedge the day the binary is live. Adding because officials confirmed a limited strike is the other trap. They said it was not a new campaign. An open option after the vote is not a lost cargo, and a lost cargo is not what Monday settled.

PositioningHold the crude sleeve. Do not add it, and do not sell it. The energy fund fell 3.96 percent yesterday, and the oil fund fell 7.08 percent. Those closes track the settle. They are not a reason to buy the dip before the vote, and they are not a reason to sell the commodity hedge. No airlines and no transports.

Key SourcesReuters, 3 Nov, https://www.reuters.com/markets/commodities/oil-rises-after-report-us-strike-irans-qeshm-island-2026-11-03/ ; Reuters, 2 Nov, https://www.reuters.com/world/middle-east/us-struck-irans-qeshm-island-wall-street-journal-reports-2026-11-03/ ; Reuters, 2 Nov, https://www.reuters.com/world/middle-east/iranians-have-left-doha-talks-draft-proposal-us-deal-being-circulated-official-2026-11-02/
United States Monday sold tech again

The cash close is in.

SignalThe S&P 500 fell 38.67 points, or 0.51 percent, to 7,541.40. The Nasdaq Composite fell 272.64 points, or 1.07 percent, to 25,164.36. The Dow rose 213.67 points, or 0.41 percent, to 51,983.98. The Russell 2000 fell 0.21 percent, to 2,805.88. Seven of the eleven sectors rose. Advancers led decliners in the S&P 500 by 2.2 to 1. This was a rotation, not a broad liquidation. The index was lower because tech was lower.

The damage sat in the spend. Nvidia fell 1.26 percent, to 202.06. AMD fell 7.52 percent, to 466.84. Intel fell 8.80 percent, to 59.97, after Friday's much larger drop. The semiconductor fund fell 2.71 percent, to 508.31. Oracle fell 8.76 percent, to 119.22, after filings for a 10 billion dollar stock sale and a 10 billion dollar bond sale to fund the buildout. The markets story called that a 20 billion dollar raise. Microsoft fell 2.83 percent. Amazon rose 2.20 percent. Those are Monday's closes. Do not average the chip fund with the chip names.

Apple's cash close was down 1.83 percent, to 338.32, and that close was before the report. After the bell the company beat on the quarter. Earnings were 2.10 dollars a share against a 1.99 dollar estimate. Revenue was 114.48 billion dollars, against 113.39 billion expected, and up 12 percent from 102.5 billion a year earlier. That 12 percent is the year, not the day. The December quarter revenue guide was growth of 7 to 10 percent, against a 6.1 percent estimate. The gross margin guide for that quarter was 45 to 46 percent, against a 46.3 percent estimate. The stock was at 328.81 in after hours trading, down 2.81 percent from the cash close. That after hours print is not Monday's close, and it is not Tuesday's open.

AMD reports later today. The report is not in. A futures screen is not a reason to buy Monday's dip into it. The Asia wrap had S&P futures up 0.1 percent, Korea down as much as 3.8 percent, and Japan closed. Those bars are not US closes.

Macro ImpactThe open question is still whether the spending turns into cash. Monday answered it for that session, the same way Friday did. Oracle paying for the buildout with new stock and new debt is the market's objection in one filing. Apple can beat the quarter and still fall when the next margin is guided down, because the memory cost is in the guide. Buying the semiconductor fund because the Dow rose, or because breadth was fine, is how a sold tape becomes a position you have to defend when AMD prints.

PositioningDo not buy the semiconductor fund, and do not short it. The close already happened. The next large chip report has not. Cash still beats a chase into a report that is not in, on the morning of a vote that is not counted.

Key SourcesReuters, 2 Nov, https://www.reuters.com/business/media-telecom/wall-street-futures-rise-ai-stocks-catch-their-breath-midterms-focus-2026-11-02/ ; CNBC, 2 Nov, https://www.cnbc.com/2026/11/01/stock-market-today-live-updates.html ; CNBC, 2 Nov, https://www.cnbc.com/2026/11/02/apple-aapl-q4-2026-earnings-live-updates.html

United States The vote is today

A poll is not a seat.

SignalTuesday 3 Nov (Tue) is the US midterm election. Voting has not produced a result in this note. Polls favor the Democrats to win the House. The Senate is too close to call in those polls. Prediction markets in the Asia wrap assign around a 75 percent chance that Democrats control the Senate, and a separate note in that story put roughly 70 percent on a Democratic sweep. The same note said those boards can misprice a political tail. A board is not a count.

The president's party holds both chambers going into the vote. The inflation people are voting on is the war, in the manufacturing story. Gasoline is the visible price. Monday's oil settle helps that price only if it lasts. A limited strike after the close is the reason it may not.

This note does not trade a history of midterm years. A past average is not today's open.

Macro ImpactA House that changes hands is a fiscal story, and it is not in the price as a fact until the seats are in. Treating a 75 percent board as a sweep, and buying or selling the tape on it this morning, is a trade on a number that the count can miss. Treating the vote as already lost for the oil sleeve is the same error in the other market. The binary is tonight, not Monday's close.

PositioningDo not add equity risk because a board likes one outcome. Do not cut the crude sleeve because a board likes a deal. Wait for seats, not for odds.

Key SourcesReuters, 3 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-03/ ; Reuters, 2 Nov, https://www.reuters.com/business/media-telecom/wall-street-futures-rise-ai-stocks-catch-their-breath-midterms-focus-2026-11-02/

United States Yields eased

The hike path did not.

SignalThere is no new US rate decision this morning. The October meeting already happened, on 27 Oct (Tue) and 28 Oct (Wed). The Fed left the policy rate in a range of 3.75 to 4.00 percent and said inflation remains elevated. The next meeting is 8 Dec (Tue) and 9 Dec (Wed). It is still the meeting with projections. Economists in the manufacturing story expect a rise then. This note has no fresh futures odds, and it does not carry last week's probability as if it were reprinted.

The yield index in the score closed Monday at 4.894 percent, down 3.5 basis points from 4.929. The 5 year index closed at 4.693 percent, down 2.8 basis points. The 30 year index closed at 5.269 percent, down 4.0 basis points. The 3 month index closed at 3.982 percent, up 0.9 basis points. These are indexes. The Asia wrap had the 10 year screen up 2.1 basis points at 4.913 percent. A screen is not the index in the score. Do not merge 4.913 with 4.894.

The oil settle is why yields fell. A lower oil price, if it lasts, is less inflation. The factory survey says the price pressure is not gone. The manufacturing gauge rose to 55.5 in October, from 54.5 in September. Economists had looked for 54.5. Production rose to 59.0. Prices paid eased to 75.2 from 77.9, and 75.2 is still a high reading. Supplier deliveries have been slowing for 11 months. Memory chips and metals are still short. The personal consumption price index rose 3.6 percent year over year in September. That is the month, not Monday. Third quarter growth was a 3.4 percent annualized rate, in the same story. A strong factory print and a hot price gauge can sit next to a down day in yields. They did.

Australia hiked this morning. The cash rate target rose 25 basis points, to 4.85 percent, from 4.60 percent. Six members voted to raise. Three voted to hold. The bank said inflation is now expected to stay above 3 percent for the coming year, with fuel and the Middle East conflict in the forecast, and with domestic costs still tight. A hike in Sydney is not a Fed decision. It is evidence that the oil shock is still pushing other central banks tighter, on the morning oil is being marked down in New York's last close.

The labor print that sits in front of the December meeting is not in. September payrolls rose 29,000, and unemployment was 4.2 percent. That is the last print, from the Bureau of Labor Statistics. October is due Friday 6 Nov (Fri) at 8:30 a.m. Eastern. Do not trade September as October.

The gold fund rose 1.65 percent, to 361.65. Monday's bounce is not a new war bid. The war hedge is still crude. The long bond fund fell 0.13 percent. That is not a cover signal.

The dollar is not a signal. Monday's close on this series was 101.82, down 0.06 percent from Friday's 101.88. The Asia story had the index near 101.81.

Macro ImpactA flight from the spend, plus a lower oil settle, pulled yields down. It did not pull the hike case out of the calendar. Covering the short because the yield index fell 3.5 basis points is how you buy a bond into a Friday labor print, a Tuesday inflation print, and a December meeting that economists still treat as a hike. Adding to the short because the Asia screen is 4.913 percent is a chase into a number that is not the index in the score.

PositioningStay underweight long duration. Do not cover, and do not add to the short before Friday's labor print. Hold cash and short bills over the long end. Do not buy the gold fund as the war hedge. If you want that hedge, it is the crude sleeve, and that sleeve is not a new trade today.

Key SourcesReuters, 2 Nov, https://www.reuters.com/world/us/us-manufacturing-picks-up-october-input-prices-stay-high-2026-11-02/ ; Institute for Supply Management, October 2026, https://www.ismworld.org/supply-management-news-and-reports/reports/ism-pmi-reports/pmi/october/ ; Reserve Bank of Australia, 3 Nov, https://www.rba.gov.au/media-releases/2026/mr-26-30.html ; Federal Reserve calendar, December 8 to 9, 2026, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm ; Bureau of Labor Statistics, September employment situation, https://www.bls.gov/news.release/empsit.htm

China A currency rule is not a spending package

SignalChina did not announce stimulus overnight. It tightened a currency rule.

The central bank will raise the foreign exchange deposit reserve ratio for financial institutions to 6 percent from 4 percent, starting 15 Nov (Sun). In the Asia wrap, the dollar was 0.3 percent stronger against the offshore yuan, at 6.6645. That rate is a screen in the story, not a US close. A higher reserve ratio drains dollar liquidity onshore. It supports the currency. It does not put money into factories.

The standing factory print is still the one from the end of October. The official manufacturing gauge was 49.3, down from 50.1, and below the 50 line that marks expansion. The non manufacturing gauge was 49.7. This note has no newer official factory figure, and it has no new spending figure.

The equity funds did not price a China bid. The emerging markets fund rose 0.11 percent yesterday, to 61.11. The large cap China fund rose 0.39 percent, to 33.21. Those are small Monday closes, not a policy turn.

Macro ImpactA reserve ratio hike is the opposite of a rescue bid. Keeping the underweight because factories are still contracting is the same call as yesterday, with one new reason not to fade it. Adding China cyclicals because US oil settled lower, or because an Asia bar is open, treats a currency tool as a growth tool.

PositioningStay underweight China cyclicals. Do not add because the gauge is weak, and do not cover the underweight because the currency rule might steady the yuan.

Key SourcesReuters, 3 Nov, https://www.reuters.com/world/asia-pacific/china-raise-forex-deposit-reserve-ratio-6-starting-november-15-2026-11-03/ ; Reuters, 3 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-03/ ; Reuters, 31 Oct, https://www.reuters.com/world/asia-pacific/chinas-october-factory-activity-contracts-fastest-pace-3-months-pmi-survey-shows-2026-10-31/

Risk matrix

The method note is above, in the markets bar. Cells below are the Monday fact, or the wire after it. Asia screens are not in this table.

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreCAUTIONHighDaysFlipped from 43 NEUTRAL to 46. Crossed 45. Did not reach 61
Brent settlementLowerHighDaysSettled at 104.77 dollars, down 7.63 percent. Yesterday this was a screen
WTI DecemberLowerHighDaysSettled at 96.46 dollars, down 7.36 percent vs Friday's 104.12
QeshmLimited strikeHighDaysAfter the oil settle. Officials called it defensive, not a new campaign
TalksNo breakthroughHighDaysContacts continue. A two day plan is not an opening
VoteTodayHighDaysPolls and boards are not seats. The count is not in
Nasdaq cashLowerHighDaysDown 1.07 percent to 25,164.36
S&P 500LowerHighDaysDown 0.51 percent to 7,541.40. The Dow rose 0.41 percent
Fed pathHike still aheadHigh1 to 3 monthsNo new US decision. Australia hiked to 4.85 percent. December is 8 Dec (Tue) and 9 Dec (Wed)
US 10 year indexLowerHigh1 to 3 monthsScore uses 4.894 percent, down 3.5 basis points. The Asia screen was 4.913
ChipsLowerHighDaysFund down 2.71 percent. AMD reports later today. Apple's after hours print is not the close
Factory pricesStill hotHighWeeksGauge 55.5. Prices paid 75.2. Not a reason to cover
Gold fundHigher on the dayMediumDaysUp 1.65 percent to 361.65. The war hedge is crude
China policyTighter FX ruleHighWeeksReserve ratio to 6 percent from 4 percent on 15 Nov (Sun). Not stimulus
DollarMonday close onlyLowDays101.82, down 0.06 percent vs Friday. Not the signal

Portfolio

Sleeve Stance Rationale
CrudeHold. Do not add. Do not sellThe settle is real, the talks are not a deal, and the strike was called limited. The sleeve is the hedge through today's vote
Energy equities (XLE)Do not add. Do not sell the commodity to fade the fundThe fund fell 3.96 percent yesterday with the settle. That is not a dip to buy before the count
Oil fund (USO)Hold with the sleeveDown 7.08 percent yesterday. It tracked the settle. It is not a new entry
Long duration (TLT)Underweight. Do not coverYield index at 4.894 percent. Factory prices are still hot. Australia hiked. Friday's labor print is not in
Cash and short billsOverweight versus the long endPaid to wait through today's vote, Friday's labor print, and next Tuesday's inflation print
Semiconductors (SMH)Do not chase. Do not shortMonday sold the chips again. AMD reports later today. Apple's after hours drop is not the cash close
Gold (GLD)No new entryThe fund rose 1.65 percent on the day. The bounce is not the war hedge. Crude is
Airlines and transportsNoThe settlement is still high, and the strait is not open
China cyclicalsUnderweightA reserve ratio hike is not spending. The factory gauge is still under 50
Broad equityDo not addMonday was a rotation lower in tech. The vote is not counted, and the next chip report is not in

The next two weeks

Date Event Why it matters
3 Nov (Tue)US midterm elections. AMD reports later today. Job openings survey at 10:00 a.m. Eastern, for SeptemberThe vote is not counted. AMD has not printed. The openings survey is not the Friday payrolls
3 Nov (Tue)Australia hiked at 2:30 p.m. SydneyCash rate to 4.85 percent, from 4.60 percent. Six to three. Already in. It is not a Fed decision
4 Nov (Wed)Treasury quarterly refunding announcementThe dealer note on Monday pointed to Wednesday. Sizes are not in this note
5 Nov (Thu)Productivity and costs, third quarter, 8:30 a.m. EasternA cost print, not the labor market
6 Nov (Fri)Employment situation for October, 8:30 a.m. EasternThe print is not in. September was a 29,000 gain, with unemployment at 4.2 percent. Do not cover before Friday
10 Nov (Tue)Consumer price index for October, 8:30 a.m. EasternThe inflation print that sits with the labor print in front of December. Not in
10 Nov (Tue) and 11 Nov (Wed)US, Ukraine, and Russia talks in Abu DhabiA separate war track, in the oil story. Not an Iran deal
13 Nov (Fri)Producer price index for October, 8:30 a.m. EasternFactory gate prices after a 75.2 prices paid reading. Not in
15 Nov (Sun)China foreign exchange reserve ratio rises to 6 percent from 4 percentA currency rule, not a spending package

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed), and it includes projections. Economists in the manufacturing story expect a rise. This note has no fresh futures odds.

Scorecard

46 of 100 sits in CAUTION. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse54Down from 56. The 10 year index closed Monday at 4.894 percent. The level is still not easy
CB Elasticity43Down from 45. The 5 year index closed at 4.693 percent. Australia hiked. December is still the hike meeting
Flow Pressure57Up from 48. This is the flip. The volatility index closed at 21.15, above 20. The high yield fund fell 0.70 percent
Narrative Coherence25Up from 13. The Dow rose and the Nasdaq fell. Oil settled on talks, then a strike hit the wires
Composite46CAUTION

The label flipped. Yesterday was 43, NEUTRAL. CAUTION is 45 to 60. RISK-ON is below 30. RISK-OFF is 61 and above. A higher score means more stress. The move was flow and narrative, not a yield spike. Yields fell. The volatility index rose. Going into today's vote at 46 is a hold on the sleeves you have, not a signal to add risk, and not a signal to dump the crude hedge.

Data through the 2 Nov 2026 US close. This is a Tuesday morning note, before the US cash open. Asia is open. Japan is closed for a holiday. There is no Tuesday US settlement in this note.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.