OverWise

Market regime, November 2

Top five drivers, the risk matrix and the book for Monday, November 02, 2026.

Not a flip. Score 43 of 100. The label is still NEUTRAL, same as yesterday. CAUTION starts at 45, RISK-ON at 30, and RISK-OFF at 61. The score did not move, and it did not cross a line. It sits 2 points under CAUTION.

Read the five drivers
Before the US open Next review 3 Nov 2026 (Tue)

Regime score

43of 100

NEUTRAL

2 under CAUTION, 13 over the RISK-ON line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Monday morning is not a new US cash close. Friday 30 Oct is the last completed US session. Asia is open. There is no Monday settlement in this note. A screen is not a settlement, and a rolled continuous bar is not a crash.

What changed overnight is the wire, not the close. The producer group confirmed December oil targets stay steady. Talks in Doha went to a third day and are not a deal. The president said there will be no new attacks before Tuesday's vote, and he left the door open after it. Oil's early Monday screen is cheaper. That is not a reason to sell the crude sleeve, and the missing attack is not a reason to add it.

The book is the same book as yesterday. Hold the crude sleeve. Do not cover the bond. Do not buy Friday's dip into a report that has not printed.

In short

MARKET REGIME, Nov 2 (Mon)

Signal. Neutral. Hold energy. Do not chase. Score 43 of 100.

  1. Iran Oil eased overnight. Hold the sleeve.
  2. United States Stocks fell Friday. Apple has not reported.
  3. United States A December rate rise is still priced.
  4. China China factories stayed in contraction.
  5. United States The vote is Tuesday. Jobs print Friday.

Markets bar

Equity, yield, dollar, and fund rows are Friday's close. Oil rows split Friday's bar from the timed Monday screen, because those are different prints. This note does not cite oil or gold volume. Thursday and Friday volume on this price series match on those bars, which means the volume figure is a copy.

The markets story said Brent's October rise was 13.6 percent. That is the month, not Friday, and not the Monday screen.

Asset Level Change
S&P 500 (Fri close)7,580.07Down 140.32 points, or 1.82 percent, vs Thursday
Nasdaq Composite (Fri close)25,437.00Down 747.72 points, or 2.86 percent, vs Thursday
Dow (Fri close)51,770.31Down 572.25 points, or 1.09 percent, vs Thursday
Russell 2000 (Fri close)2,811.84Down 1.66 percent vs Thursday's 2,859.22
VIX (Fri close)19.42Up 2.22 points vs Thursday's 17.20. The close is under 20. The score uses this close
US 10-year yield index (Fri close)4.929%Down 6.0 basis points vs Thursday's 4.989. This is the index in the score, not a Monday cash yield
5-year yield index (Fri close)4.721%Down 8.0 basis points vs Thursday's 4.801
30-year yield index (Fri close)5.309%Down 2.0 basis points vs Thursday's 5.329
3-month yield index (Fri close)3.973%Down 2.5 basis points vs Thursday's 3.998
Brent Friday bar117.64 dollarsThe expired December contract. Not the active contract
Brent Monday screen (0011 GMT)111.84 dollarsDown 1.59 dollars, or 1.40 percent, in the story. Reference price 113.43 dollars. A screen, not a settlement
WTI Friday bar104.12 dollarsThe Friday level the Monday story uses as its reference
WTI Monday screen (0011 GMT)102.56 dollarsDown 1.56 dollars, or 1.50 percent, in the story. A screen, not a settlement
Dollar index (Fri close)101.88Down 0.16 percent vs Thursday's 102.04. No fresh cash print
Gold (Fri close)3,898.90 dollarsDown 3.3 percent vs Thursday's 4,031.40. The day is not the month
Gold fund (Fri close)355.78Down 3.47 percent vs Thursday's 368.57
Energy fund (Fri close)70.02Up 1.91 percent vs Thursday's 68.71
Oil fund (Fri close)168.83Up 0.38 percent vs Thursday's 168.19
Semiconductor fund (Fri close)522.49Down 6.98 percent vs Thursday's 561.67. The chip index fell 7.20 percent. Different index
Long bond fund (Fri close)81.84Up 0.43 percent vs Thursday's 81.49
High yield fund (Fri close)77.43Down 0.19 percent vs Thursday's 77.58
Investment grade fund (Fri close)104.27Up 0.05 percent vs Thursday's 104.22

Top five drivers

Iran The oil screen eased

Hold the sleeve.

SignalThe strait did not open overnight. The early oil screen got cheaper. A cheaper screen is not a new settlement, and a confirmed hold on targets is not new barrels.

By 0011 GMT, the oil story had Brent futures 1.59 dollars lower, or 1.40 percent, at 111.84 dollars. Adding that drop back gives 113.43 dollars, the story's reference price, which is the active contract's Friday level. This price series printed a Friday bar of 117.64 dollars. That bar is the expired December contract. Do not trade 117.64 as the active contract, and do not trade 111.84 as a settlement.

The same story had US crude 1.56 dollars lower, or 1.50 percent, at 102.56 dollars by 0011 GMT. Adding that drop back gives 104.12 dollars, which matches Friday's bar on this series. One Friday number. The 102.56 dollars is a screen.

This series also printed a Sunday bar below both of those screens. Two pulls of that Sunday bar did not agree on the cents, and Thursday and Friday volume are identical, so that volume is a copy. The gap down from 117.64 dollars is a roll off the expired contract, plus a screen. It is not a crash in the active contract.

The producer group is no longer a rumour. Seven members kept December targets steady on Sunday. Gulf members are still pumping below their targets because of the war. A layer of cuts of about 2 million barrels a day is still in place through the end of 2026. The earlier rollback, of 1.65 million barrels a day, was already completed in September. A hold is not a new cut, and it is not new barrels. The full group meets on 29 Nov (Sun). That meeting is the 2027 call, not today's. An analyst in the story called Sunday the easy decision.

Talks went to a third day in Doha. The foreign minister said they were ongoing, and that no final conclusion had been reached. He said Tehran is prepared for both defence and diplomacy. A two-day proposal to reopen the strait was discussed. A proposal is not an opening. The president said the United States will not launch new attacks before Tuesday's vote, and that talks have been productive. He did not rule out further military action after the vote. The secretary of state had already said on Saturday that no strike decision had been taken. The Monday oil story does not name a new confirmed ship.

The story's analyst called the screen a technical pullback after last week's gains, with no meaningful military escalation over the weekend. He also said rhetoric could still push prices higher after the vote.

Macro ImpactYesterday the trap was selling the sleeve because mediators met, or adding it because a leader ordered readiness. Today the trap is selling it because the screen eased, or because the continuous bar looks far below 117.64 dollars. Neither print is a close. Adding because action after Tuesday is not ruled out is the other trap. An open option is not a lost cargo.

PositioningHold the crude sleeve. Do not add it, and do not sell it. No airlines and no transports. The energy fund rose 1.91 percent on Friday. That close is not a reason to add the fund into the vote, and the Monday screen is not a reason to sell it.

Key SourcesReuters, 2 Nov, https://www.reuters.com/business/energy/oil-slips-more-than-1-talks-continue-ending-iran-war-2026-11-01/ ; Reuters, 1 Nov, https://www.reuters.com/business/energy/opec-set-keep-oil-output-targets-steady-sources-say-2026-11-01/ ; Reuters, 1 Nov, https://www.reuters.com/world/middle-east/iranian-negotiators-doha-continue-talks-end-us-iran-war-official-says-2026-11-01/
United States Friday sold the chips

Apple has not reported.

SignalThe cash close already happened. A futures bounce is not a new cash close, and an open Asia session is not a US open.

The S&P 500 fell 140.32 points, or 1.82 percent, to 7,580.07. The Nasdaq Composite fell 747.72 points, or 2.86 percent, to 25,437.00. The Dow fell 572.25 points, or 1.09 percent, to 51,770.31. The Russell 2000 fell 1.66 percent, to 2,811.84. The markets story said the Nasdaq lost almost 7 percent in October. That is the month, in the story. This note does not have its own monthly percent.

The damage on Friday sat in chips. Intel fell 28.6 percent, to 65.76. The story said near 29 percent, same session. Nvidia fell 4.2 percent, to 204.64. AMD fell 10.9 percent, to 504.80. The chip index fell 7.20 percent. The semiconductor fund fell 6.98 percent, to 522.49. Those are two indexes. Do not average them.

Apple reports later today. The report is not in. The markets story also names other large reports in the same week. This note does not assign those days. A report that has not printed is not a reason to buy Friday's dip.

The early Sydney wire had share markets lower, Japan's index down 0.5 percent, and Korea down 0.8 percent. It said Korea shed 16 percent last month. That 16 percent is the story's month, not this morning. The latest bars on this series, with Asia still open, are not closes. Japan's bar is down 0.3 percent so far, Korea's bar is up 2.2 percent so far, and Australia's bar is down 0.7 percent so far. Those bars are from the early morning read. The early wire and this series do not agree on Korea. Do not trade either print as a Monday close, and do not use an open Korea bar to buy US chips.

US futures are a screen, not a cash close. The story had S&P futures up 0.4 percent and Nasdaq futures up 0.6 percent. Sunday bars on this series are up 0.44 percent and 0.91 percent. Close on the first, not the same on the second. Do not average them, and do not trade either as Friday's cash close.

The story said hyperscaler spending is expected to almost double to 800 billion dollars this year, and to rise to 1.2 trillion dollars in 2027. It said earnings growth is strong, and no longer accelerating, with growth near 30 percent this year slowing to 18 percent next year. Those are the story's figures, not a cash close. Strong growth and a sold Friday can both be true. The story also said withdrawals followed a theft of billions at a large crypto exchange that came back online on Sunday. This note does not have a verified dollar figure for that theft. It is not a reason to buy Friday's dip, and it is not a reason to sell the crude sleeve.

Macro ImpactThe open question is whether the spending turns into cash. Friday answered it for that session. Monday has not. Buying the chip fund because futures bounced, or because Korea's open bar is higher, is how a sold tape becomes a position you have to defend when the report prints.

PositioningDo not buy the semiconductor fund, and do not short it. The close already happened. The next large report has not. Cash still beats a chase into a report that is not in.

Key SourcesReuters, 2 Nov, Sydney markets wrap, https://live.euronext.com/en/financial-news/asia-shares-bend-under-ai-stress-apple-earnings-loom

United States A December rise is still priced

Do not cover.

SignalThere is no new rate decision this morning.

Futures in the markets story imply a 72 percent chance of a quarter point rise, and 55 basis points of total tightening, against more than 70 basis points a month ago. The odds eased on the month. An increase is still the priced outcome. Do not read 55 basis points as a pause.

The yield index in the score closed Friday at 4.929 percent, down 6.0 basis points from 4.989. The 5 year index closed at 4.721 percent, down 8.0 basis points from 4.801. The 30 year index closed at 5.309 percent, down 2.0 basis points from 5.329. These are indexes, not cash yields. The markets story had the 10 year screen at 4.952 percent, and the 2 year screen at 4.612 percent, with an October peak of 5.3645 percent in that story. A screen is not the index in the score. Do not merge 4.952 with 4.929.

The October meeting already happened, on 27 Oct (Tue) and 28 Oct (Wed). The next one is 8 Dec (Tue) and 9 Dec (Wed). It is still the hike meeting. The labor print that sits in front of it is not in. The markets story's median forecast is a 65,000 rise, with unemployment holding at 4.2 percent, after September's 29,000 gain. That 65,000 is a forecast, not a print. Do not trade September as October, and do not cover before Friday.

Friday's gold close on this series was 3,898.90 dollars, down 3.3 percent from Thursday's 4,031.40. The gold fund fell 3.47 percent, to 355.78. The markets story said gold bounced 0.6 percent to 3,898 dollars, and that it fell 6.8 percent last month, to a one year low in that story. The day and the month are different intervals. The Sunday bar on this series is a little higher than Friday, and two pulls did not agree on the cents. That is not a settlement. Gold's Friday fall was the rate story, not a war bid. The war hedge is still crude.

The dollar is not a signal. Friday's close on this series was 101.88, down 0.16 percent from Thursday's 102.04. This note has no fresh cash print.

Macro ImpactA flight from the spend pulled yields down on Friday. It did not pull the hike case out of the price. Covering the short because the yield index fell 6.0 basis points is how you buy a bond into a December meeting that is still priced as a hike. Adding to the short because the cash screen is 4.952 percent is a chase into a print that is not in. The long bond fund rose 0.43 percent on Friday. That is the close, not a new entry.

PositioningStay underweight long duration. Do not cover, and do not add to the short before Friday's labor print. Hold cash and short bills over the long end. Do not buy the gold dip. A zero weight in gold is fine. If you want the war hedge, it is the crude sleeve, and that sleeve is not a new trade today.

Key SourcesReuters, 2 Nov, Sydney markets wrap, https://live.euronext.com/en/financial-news/asia-shares-bend-under-ai-stress-apple-earnings-loom ; Federal Reserve calendar, December 8 to 9, 2026, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm

China Factories are still contracting

That is not a bid.

SignalChina already printed the number. Monday did not bring a package.

The official manufacturing gauge fell to 49.3 in October, from 50.1 in September. A Reuters poll had looked for 50.0. It is the third contraction in four months. The non manufacturing gauge, which covers services and construction, fell to 49.7 from 50.2. New orders and new export orders stayed in contraction. Production slipped into contraction from expansion. A reading below 50 is contraction. This one missed the line, and it missed the forecast.

Economists in the story asked for more support. The story did not contain a new stimulus figure. The economy is expected to meet a 4.5 to 5.0 percent growth target without extra measures, after third quarter growth of 4.5 percent, up from 4.3 percent in the prior quarter. An expectation of no extra package is not a package. Some high tech manufacturing gauges were at or above 53.0. That is not the headline. The headline is 49.3.

This note does not use a private gauge. A second survey was not in the sources read again. Korea's open bar is not a China bid.

Macro ImpactA factory gauge under 50, with no new policy figure, is a reason to keep the underweight. It is not a reason to add risk on the hope that support will have to come. It has not, in this note.

PositioningStay underweight China cyclicals. Do not add because the gauge missed, and do not cover the underweight because an Asia bar is open.

Key SourcesReuters, 31 Oct, https://www.reuters.com/world/asia-pacific/chinas-october-factory-activity-contracts-fastest-pace-3-months-pmi-survey-shows-2026-10-31/

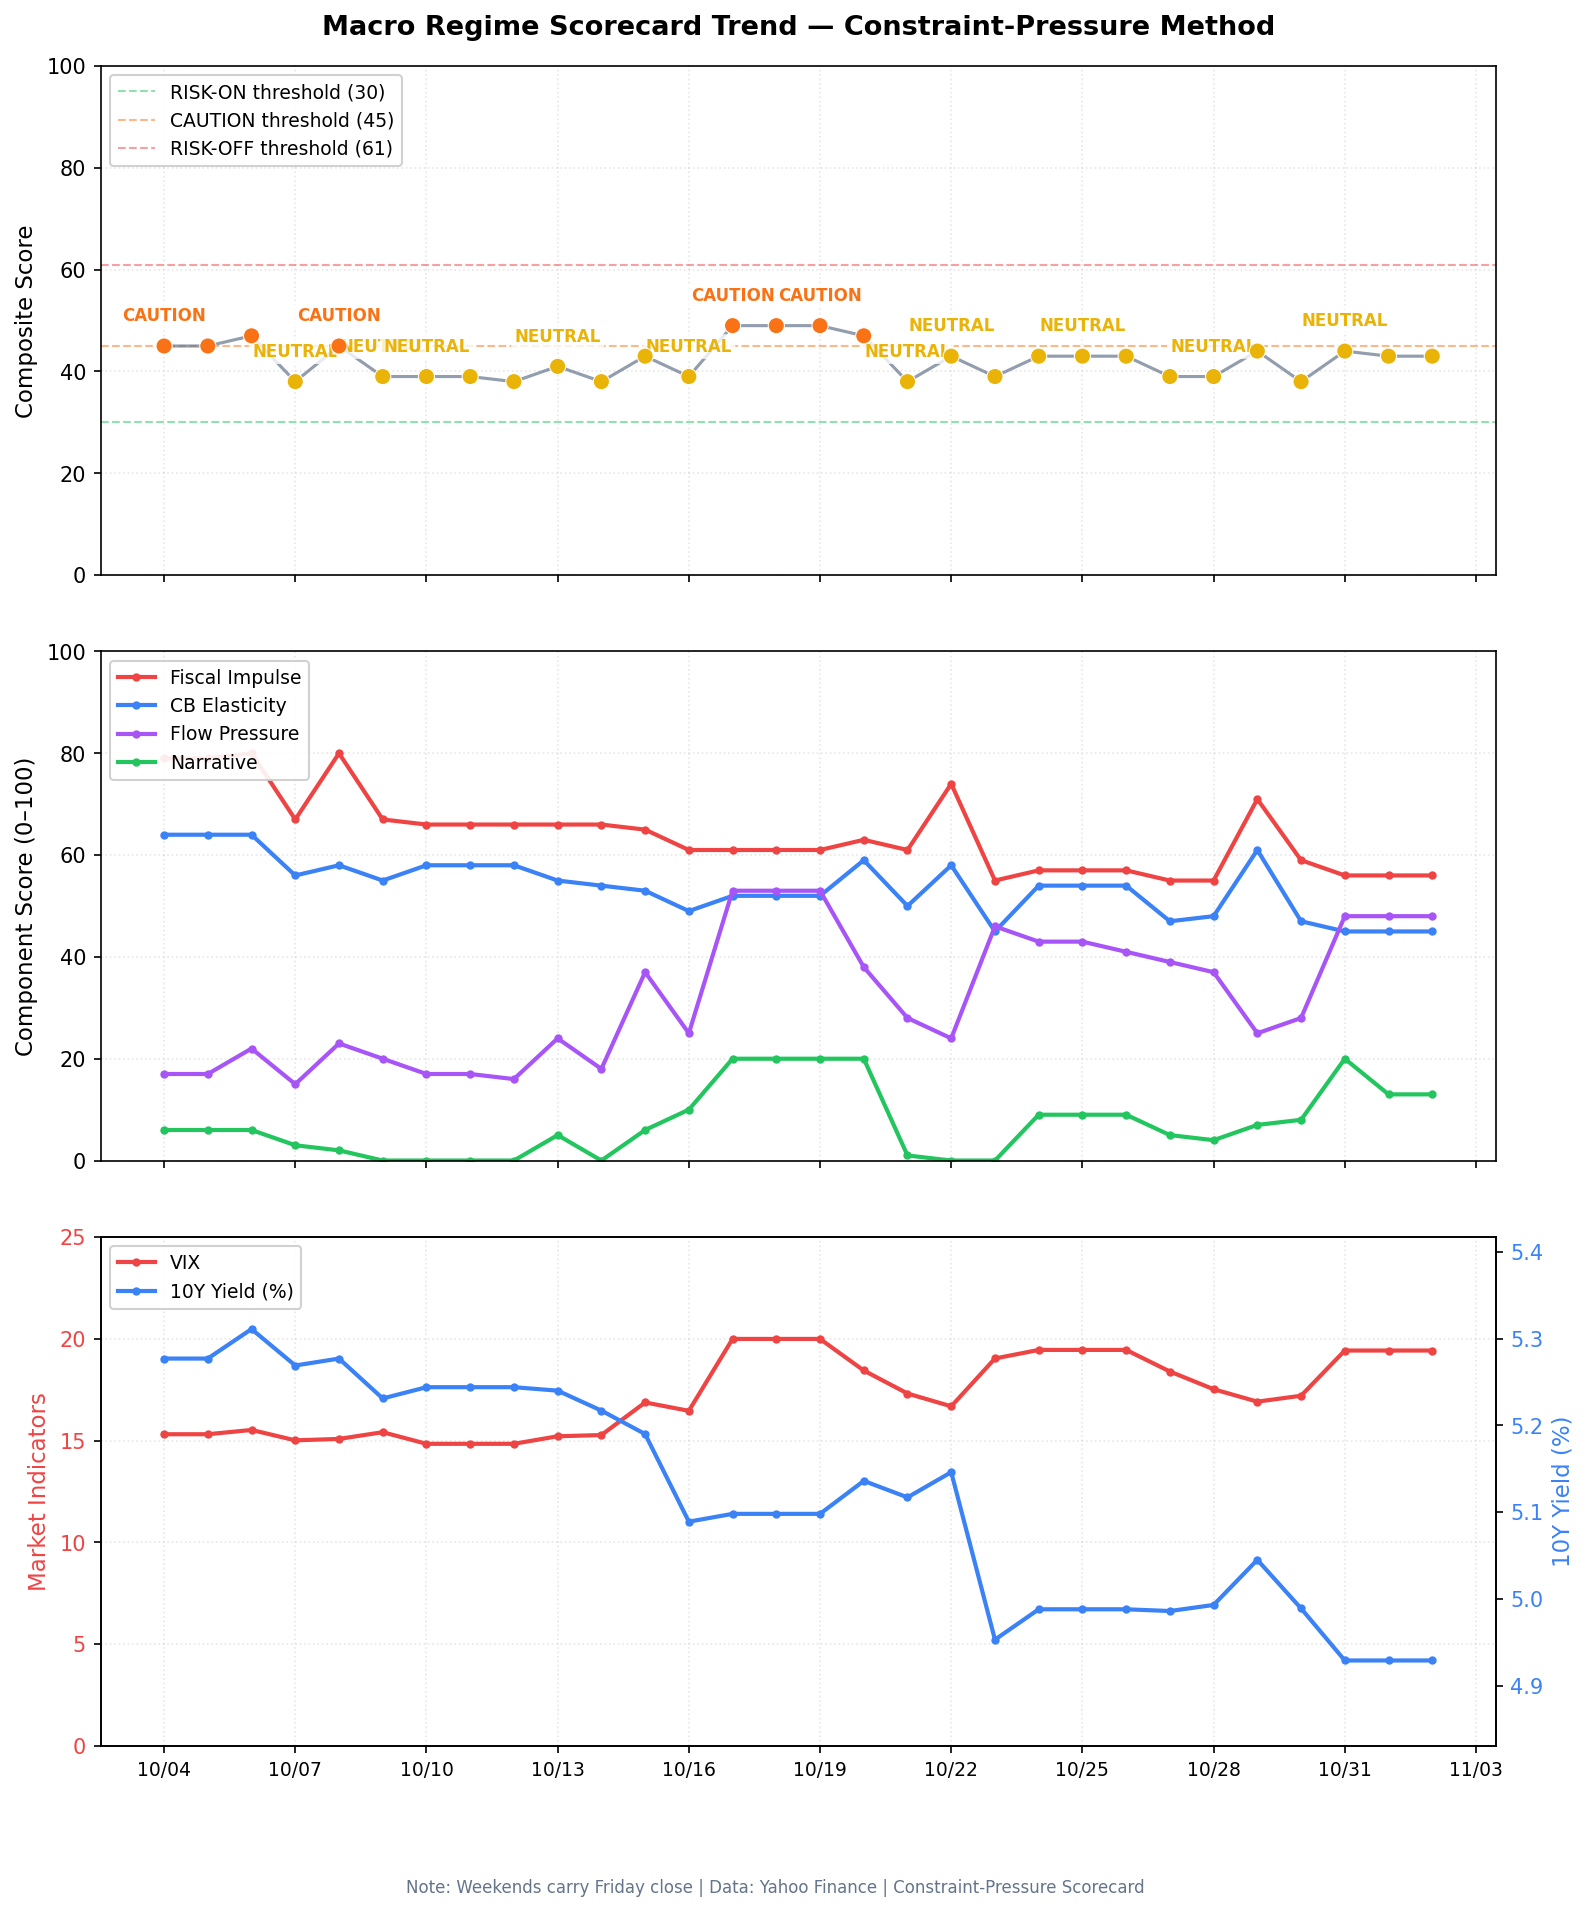
The score is still 43

Tuesday is the vote. Friday is the print.

SignalAn unchanged score on a Monday morning is a hold, not a buy. A volatility index at 19.42 is not a crash, and it is not an all clear.

The score is 43. Yesterday's score was 43. Fiscal pressure is 56, central bank pressure is 45, flow pressure is 48, and narrative stress is 13. All unchanged. The volatility index in the score is Friday's 19.42. The yield index in the score is Friday's 4.929 percent. Prices did not print a Monday cash close.

The high yield fund fell 0.19 percent on Friday. The investment grade fund rose 0.05 percent. Credit softened. It did not crack. That is not a reason to add risk 2 points under the CAUTION line, with a strait that is not open and a vote that has not been held.

Tuesday 3 Nov (Tue) is the US midterm election. The president said no new attacks before that vote. He did not rule out action after it. A line before the vote is not an order, and a poll is not a settlement. Friday 6 Nov (Fri) is the October employment situation. The labor print is not in. The survey of manufacturers is later today. It is not in. Apple reports later today. That report is not in.

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed). It is still the hike meeting. The markets story put a 72 percent chance on a quarter point rise.

Macro ImpactA score that does not move, and stays 2 points under CAUTION, is a hold. Treating 43 as a buy because it is not 45 adds risk into a vote that has not been held. Treating 43 as a flip sells a book whose label has not changed.

PositioningDo not add risk because the label is still NEUTRAL. Do not cut risk because the screen eased. The sleeve you had yesterday is the sleeve you should still have.

Key SourcesReuters, 2 Nov, https://www.reuters.com/business/energy/oil-slips-more-than-1-talks-continue-ending-iran-war-2026-11-01/ ; Reuters, 1 Nov, https://www.reuters.com/world/middle-east/iranian-negotiators-doha-continue-talks-end-us-iran-war-official-says-2026-11-01/ ; Federal Reserve calendar, December 8 to 9, 2026

Risk matrix

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreStill NEUTRALHighDaysUnchanged at 43. Two points under CAUTION. Did not cross 45 or 30
Line before the voteNo new attacks before TuesdayHighDaysThe president said no new attacks before the vote. Action after is not ruled out
TalksThird day, no conclusionHighDaysA two-day strait proposal is not an opening
OPEC+ December targetsConfirmed steadyHighWeeksNow a statement, not a rumour. Not new barrels, and not a new cut
Brent screenLower, not settledHighDays1.59 dollars lower by 0011 GMT, to 111.84 dollars. Reference 113.43
WTI screenLower, not settledHighDays1.56 dollars lower by 0011 GMT, to 102.56 dollars
Continuous barRoll, not a crashHighDaysFriday's 117.64 dollars is the expired contract
Fed pathHike still pricedHigh1 to 3 mo72 percent chance of a quarter point rise. 55 basis points priced
US 10 year indexFriday close in the scoreHigh1 to 3 moScore uses 4.929 percent. Story screen is 4.952 percent. Do not merge
Nasdaq cashLower on FridayHighDaysDown 2.86 percent to 25,437.00
S&P 500Lower on FridayHighDaysDown 1.82 percent to 7,580.07
Asia cashOpenMediumDaysEarly wire and this series disagree on Korea. Neither print is a close
China factoriesStill in contractionHighWeeksManufacturing 49.3. Non manufacturing 49.7. No new stimulus figure
GoldLower on FridayHighDaysClosed at 3,898.90 dollars, down 3.3 percent on the day. The month is a different interval
ChipsLower on FridayHighDaysChip index down 7.20 percent. The fund down 6.98 percent. Do not average
DollarFriday close onlyLowDays101.88, down 0.16 percent vs Thursday. No fresh cash print

Portfolio

Sleeve Stance Rationale
CrudeHold. Do not add. Do not sellTargets are steady, talks are not a deal, and the cheaper screen is not a close. The sleeve is the hedge, not a new trade
Energy equities (XLE)Hold with the sleeve. Do not addThe fund rose 1.91 percent on Friday. That is not a reason to add into the vote, or to sell on the Monday screen
Long duration (TLT)Underweight. Do not coverYield index at 4.929 percent. A December rise is still priced, at 72 percent in the markets story. Do not add to the short before Friday's print
Cash and short billsOverweight versus the long endPaid to wait through Tuesday's vote and Friday's labor print. This note has no fresh cash bill yield
Semiconductors (SMH)Do not chase. Do not shortFriday sold the chips. Apple reports later today. The report is not in
Gold (GLD)No new entryFriday's close is down 3.3 percent on the day. The fall is the rate story. The war hedge is crude
Airlines and transportsNoThe screen is still high, and a third day of talks is not an opening
China cyclicalsUnderweightOfficial factory gauge at 49.3. No new stimulus figure
Broad equityDo not addFriday was a down day. The vote has not been held, the labor print is not in, and Apple has not reported

The next two weeks

Date Event Why it matters
2 Nov (Mon)Apple reports. US manufacturing survey later todayNeither print is in. Do not buy Friday's dip into a report that has not printed
3 Nov (Tue)US midterm electionsNo new attacks before this vote, in the president's words. Action after is not ruled out. Do not trade the polls as a settlement
6 Nov (Fri)October employment situationThe print is not in. The markets story's median forecast is a 65,000 rise, with unemployment holding at 4.2 percent. September was a 29,000 gain. Do not cover before the print

The markets story says investors are wagering on hikes this week from Australia, Britain, and Sweden, and a hold in Norway. This note does not assign those days.

The full producer meeting sits beyond this two week list. It is 29 Nov (Sun). Sunday's hold was the easy call, in the story. The 2027 quotas are not today's trade.

The December policy meeting also sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed). It is still the hike meeting. The markets story put a 72 percent chance on a quarter point rise, with 55 basis points of tightening priced. Do not cover before the labor print that sits in front of it.

Scorecard

43 of 100 sits in NEUTRAL. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse56Unchanged. The yield index closed Friday at 4.929 percent. The level is still not easy
CB Elasticity45Unchanged. The 5 year index closed Friday at 4.721 percent. December is still priced as a hike meeting
Flow Pressure48Unchanged. The volatility index closed Friday at 19.42, under 20. The high yield fund fell 0.19 percent on Friday
Narrative Coherence13Unchanged. The score did not take a new dip
Composite43NEUTRAL

The label did not flip. The score is 43, same as yesterday. CAUTION is 45, RISK-ON is 30, and RISK-OFF is 61. A higher score means more stress. This score is 2 points from CAUTION and 13 points from RISK-ON. There is no ceasefire, the Monday screen is not a settlement, and the vote has not been held. Going into that calendar at 43 is a hold, not a signal.

Data through the 30 Oct 2026 US close. This is a Monday edition before the US cash open. Asia is open. There is no Monday settlement.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.