OverWise

Market regime, October 27

Top five drivers, the risk matrix and the book for Tuesday, October 27, 2026.

Not a flip. Score 39 of 100. The label is NEUTRAL. Yesterday the score was 43. The label was already NEUTRAL. The line for CAUTION is 45. The line for RISK-ON is 30. The line for RISK-OFF is 61. The score fell 4 points. It is 6 points under the CAUTION line. It is 9 points above the RISK-ON line. It did not cross either line.

Read the five drivers
Before the US open Next review 28 Oct 2026 (Wed)

Regime score

39of 100

NEUTRAL

6 under CAUTION, 9 over the RISK-ON line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Monday is the last completed US session. This is a Tuesday edition after that close. The US cash market does not reopen until later today. A screen after the close is not a new settlement.

What changed is the oil settlement, the stock bounce, and the strike clock. Talks in Tehran took oil off Friday's high. The same day, US forces were described as ready for major strikes within 96 hours of an order that has not been given. Stocks rose on a listing filing. None of that changed the label.

The book versus Monday is the same book, with less reason to chase. Hold the crude sleeve. Do not add it on the strike clock. Do not sell it on the talks. Do not buy the technology bounce before the earnings prints. Do not cover the long bond before Wednesday.

Three things still land in the next three sessions. The policy decision is Wednesday. September personal income and outlays, with the first read on third quarter output, is Thursday. Microsoft and Alphabet report Wednesday, Amazon on Thursday. The week is still an event week, not a trend week.

In short

MARKET REGIME, Oct 27 (Tue)

Signal. Neutral. Hold energy. Do not add. Score 39 of 100.

  1. Iran Tehran talks eased oil. No deal. Strike option open.
  2. United States Stocks rose Monday. Anthropic filed to list.
  3. United States Fed decides Wednesday. A hold is the base.
  4. Gold settled higher. It is still a rates trade.
  5. United States Big tech reports Wednesday and Thursday.

Markets bar

Monday is the last completed US session. Equity, yield and fund rows are that close. Oil and gold rows name the settlement, not the last trade on this feed.

This note does not cite oil or gold volume as a settlement volume. Monday's volume on this feed for Brent, crude and gold is far below Friday's volume. That is not the settlement print. A separate screen on this feed shows the Brent continuous contract about six dollars under Monday's settlement of 115.81 dollars. That is a different contract, not a fall in the settled month. Do not trade it, and do not average it with 115.81.

The stock close story printed a US crude figure of 101.57 dollars, down 1.7 percent. The settlement story, in two places, printed 101.76 dollars, down 1.51 dollars, or 1.46 percent. This note uses 101.76. It does not average the two.

Asset Level Change
S&P 500 (Mon close)7,676.77Up 53.09 points, or 0.70 percent, vs Friday's 7,623.68. Close story. This feed agrees. Still under the 21 Oct close of 7,757.17
Nasdaq Composite (Mon close)26,169.38Up 214.04 points, or 0.82 percent, vs Friday's 25,955.34. Close story. This feed agrees. Still under the 21 Oct close of 26,702.86
Dow (Mon close)52,361.58Up 146.42 points, or 0.28 percent, vs Friday's 52,215.16. Close story. This feed matches
VIX (Mon close, this feed)18.39Down 1.06 points vs Friday's 19.45. The close is under 20. The score uses this close
US 10-year yield index (Mon close)4.986%Down 0.2 basis points vs Friday's 4.988. This is the index in the score. Not the cash yield
5-year yield index (Mon close)4.824%Up 1.9 basis points vs Friday's 4.805. Not the cash yield
30-year yield index (Mon close)5.301%Down 1.4 basis points vs Friday's 5.315. Not the cash yield
Cash 10-year (Mon close story)5.00%A cash close story said 5.00 percent, unchanged on the day. Do not average 5.00 and 4.986
Brent (Mon settlement)115.81 dollarsDown 91 cents, or 0.8 percent, from Friday's 116.72. Settlement story. Still near a six month high
WTI (Mon settlement)101.76 dollarsDown 1.51 dollars, or 1.46 percent, from Friday's 103.27. Settlement story. Do not print a second price
December gold (Mon settlement)4,038.40 dollarsUp 0.8 percent vs Friday. Settlement story. Not this feed's last trade
Spot gold (Mon, 14:09 ET)4,020.60 dollarsUp 0.6 percent at that clock time, after a Friday low of 3,975. A spot print is not the futures settlement
Gold fund (Mon close)367.82Up 0.3 percent vs Friday's 366.61. The fund is not the futures settlement
Dollar index (Mon close, this feed)102.05Up from Friday's 101.81. This feed. A gain of about a quarter of a point
Energy sector fund (Mon close)69.64Up 0.4 percent vs Friday's 69.33. The equity did not confirm the crude dip
Oil fund (Mon close, this feed)166.23Down 1.9 percent vs Friday's 169.53. The fund is not the settlement
Semiconductor fund (Mon close)541.62Up 2.7 percent vs Friday's 527.20. Still under the 21 Oct close of 556.70 on this feed
Long bond fund (Mon close)81.68Up 0.4 percent vs Friday's 81.34. Not a cover
Defense fund (Mon close)207.16Up 2.4 percent vs Friday's 202.23. A bounce on the strike clock, not an order
China fund (Mon close)32.51Up 0.6 percent vs Friday's 32.31. No new policy decision

Top five drivers

Iran Tehran Talks Eased the Settlement

The Strike Clock Is Still Running.

SignalBrent settled at 115.81 dollars on Monday, down 91 cents, or 0.8 percent, from Friday's 116.72. US crude settled at 101.76 dollars, down 1.51 dollars, or 1.46 percent, from Friday's 103.27. The settlement story tied the drop to hopes of easing hostilities, and said attacks on Saudi Arabia and on shipping limited the fall. Saudi Arabia's defense minister met Iran's president in Tehran, with Turkey and Pakistan in the room. The four agreed to keep talking. Qatar's mediators had gone to Tehran on Sunday. The same day, CNN reported that US forces are prepared to launch major operations against Iran within 96 hours of an order from the president. The order has not been given. Officials told CNN the president has not decided, appears to lean toward action, and has backed off before. They put the more likely window after the US midterms, not this week.

Macro ImpactA meeting is not a deal, and a readiness clock is not an order. The strait is not open. The settled month is still near a six month high, and the reserve of last resort is thin in a different sense: the Energy Department said the Strategic Petroleum Reserve stood at 282.6 million barrels last week, the lowest since October 1982. Houthis said they struck a Saudi pipeline and Riyadh airport. Saudi Arabia has not confirmed those strikes. The coalition said it destroyed three drones. The market sold a little of the risk premium and kept most of it. The error is to trade the talks as a close, or the 96 hour line as a launch.

PositioningHold the crude sleeve. Do not add it on the strike clock. Do not sell it on the Tehran meeting. No airlines and no transports until there is a ship count or an opening. Keep the energy equity weight. The sector fund rose 0.4 percent while the settlement fell. That is not a reason to add, and it is not a reason to sell.

Key SourcesReuters, 26 Oct, "Oil settles lower on peace hopes, Saudi attacks limit losses"; CNBC, 26 Oct, "Oil ticks lower as Saudi defense minister meets with Iran's president in Tehran"; CNN, 26 Oct, "US has plans for major Iran strikes if Trump chooses".
United States The Fed Meets

A Hold on Wednesday. A December Rise Is Still the Lean.

SignalThe policy meeting runs Tuesday and Wednesday. The decision lands Wednesday. This meeting carries no new projections. The Federal Reserve calendar marks projections for the 8 to 9 Dec meeting, not for this one. Monday's stock close story said fed funds futures implied a 90 percent chance of a hold, with the target range at 3.75 percent to 4 percent. The gold close story said expectations for a December rise were at 80 percent on the CME tool. Coverage puts the statement at 14:00 ET and the press conference at 14:30 ET.

Macro ImpactThe hold itself is priced and should not move much. The risk sits in the statement and the press conference, eight days before the US midterms. A hawkish hold keeps the 10-year index near 5 percent and keeps the duration short paid. A surprise softening is the tail. A cut is not the base in this note. The European Central Bank decision lands Thursday, with the press conference that day. Monday coverage leans to a pause there as well. Two holds in two days is not an easing cycle.

PositioningStay underweight long duration. Do not cover before Wednesday. Do not add to the short either, into a two way event. Hold cash and short bills over the long end. The bill index on this feed closed at 4.025 percent. Cash is paid to wait.

Key SourcesFederal Reserve meeting calendar, October 27 to 28 with no projections, December 8 to 9 with projections; CNBC, 26 Oct, stock close story, 90 percent hold odds and a 3.75 to 4 percent range; CNBC, 26 Oct, gold story, December rise odds at 80 percent; European Central Bank calendar, decision day 29 Oct.

United States Stocks Rose on a Listing Filing

That Is Not an Earnings Print.

SignalThe S&P 500 closed at 7,676.77, up 0.70 percent. The Nasdaq closed at 26,169.38, up 0.82 percent. The Dow closed at 52,361.58, up 0.28 percent. The close story tied the bounce to Anthropic's public listing filing and to the oil dip. Anthropic reported 16.29 billion dollars of revenue for the six months ended 30 June, up from 1.16 billion dollars a year earlier. It also reported a loss of 80.7 billion dollars for that half. About 72 billion dollars of that loss is an accounting charge on convertible notes, not cash leaving the firm. The close story said Nvidia climbed 2.4 percent on Monday. This feed closed at 216.00, from 210.96, which is the same 2.4 percent. The semiconductor fund on this feed rose 2.7 percent, to 541.62. It is still under the 21 Oct close of 556.70. Alphabet fell 1.1 percent on this feed, to 316.80, into its own print.

Macro ImpactThe filing soothed a fear. It did not retire it. Meta said it plans to raise 95 billion dollars for artificial intelligence spending. SpaceX closed a 40 billion dollar debt deal for chips over the weekend. That is more paper, not less spending. The bounce is a one day repair of Friday, not a new high. The S&P 500 is still under the 21 Oct close of 7,757.17. Microsoft and Alphabet report Wednesday after the close. Amazon reports Thursday after the close. Either they confirm the spending, which is more issuance and more pressure at the long end, or they trim it, which is the growth scare. The filing does not answer that.

PositioningKeep semis underweight. Do not buy Monday's bounce before the prints. No new high beta technology. Utilities remain the cleaner way to own the power demand. The utilities fund closed at 42.55, flat on the day.

Key SourcesCNBC, 26 Oct, "Stocks close higher as excitement over Anthropic IPO filing propels tech sector"; WSJ, 26 Oct, same closes; CNBC, 26 Oct, Anthropic listing coverage, revenue of 16.29 billion dollars and a first half loss of 80.7 billion dollars, mostly a convertible note charge.

United States Thursday Is the Inflation Print

Monday's Oil Dip Is Not That Print.

SignalSeptember consumer prices already printed, at 3.7 percent from a year earlier. That print is not new. Thursday at 8:30 ET brings September personal income and outlays, the first read on third quarter output, and the weekly claims print, all on the same morning. The Bureau of Economic Analysis schedule lists the first two for 29 Oct. August core spending inflation was last reported at 3.0 percent. That figure is not Thursday's number.

Macro ImpactMonday's oil settlement helps the fear. It does not replace the print. Monday's Brent settlement of 115.81 dollars is still the energy input, not Friday's 116.72 and not a return to the pre war price. A core spending print at or above 3 keeps the December rise on the table. A softer core is the one domestic number that could take it off. The labor market has not printed a new claims figure since last week's reading near a 57 year low. Thursday is that update. Do not trade last week's claims as if they were this week's.

PositioningNo duration add ahead of Thursday. Own the energy cash flows rather than the consumer. Keep consumer discretionary light. The discretionary fund rose 1.0 percent on Monday, to 114.26. A one day bounce is not a fuel bill falling.

Key SourcesCNBC, 14 Oct, "Consumer prices rose 3.7% annually in September"; Bureau of Economic Analysis release schedule, 29 Oct, personal income and outlays and the third quarter advance estimate, both at 8:30; CNBC, 26 Oct, gold story, spending inflation due Thursday.

Gold Bounced Because Oil Eased

It Is Still a Rates Trade.

SignalDecember gold settled at 4,038.40 dollars on Monday, up 0.8 percent, after Friday's close on this feed at 4,007.90. Spot gold was at 4,020.60 dollars at 14:09 ET, up 0.6 percent, after trading at 3,975 on Friday. The gold fund rose 0.3 percent, to 367.82. The close story tied the bounce to softer oil and to bargain hunting ahead of Wednesday, and said the market would likely sit near 4,000 dollars into the decision.

Macro ImpactThe mechanism from last week did not break. When crude rises, hike odds rise, and gold falls. On Monday crude settled lower, and gold settled higher. That is the same link, run in reverse for one day. It is not a war hedge returning. A book that owns gold for Iran risk was not hedged last week, and a 0.8 percent bounce does not rebuild that hedge. The strike clock is still open. The crude sleeve is still the hedge that is doing the job.

PositioningNo new gold entry. A zero weight is fine. Do not average down into a rate driven market on a one day bounce. If you want the war hedge, it is the crude sleeve, held, not added.

Key SourcesCNBC, 26 Oct, "Gold rises as lower oil prices ease inflation fears ahead of Fed meeting", December gold settled at 4,038.40 dollars, up 0.8 percent; spot gold at 4,020.60 dollars at 14:09 ET.

Risk matrix

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreStill NEUTRALHighDays↘ 39, from 43. Fell 4 points. Did not cross 45. Did not cross 30. CAUTION is 45. RISK-ON is 30. RISK-OFF is 61
Iran talksLive, not a dealHighDays↗ A defense minister meeting in Tehran, with Turkey and Pakistan. They agreed to keep talking. A meeting is not a close
Strike clockOpen, not orderedHighDays↗ Forces described as ready within 96 hours of an order. The order has not been given. The lean in the reporting is after the midterms, and the president has backed off before
HormuzNot openHighDays↔ No ship count, no opening. The status quo was called untenable by one official. A comment is not an opening
Brent settlementLower, still highHighDays↘ Settled at 115.81 dollars, down 0.8 percent from 116.72. A headline is now a settlement. It is not a deal
WTI settlementLower, still highHighDays↘ Settled at 101.76 dollars, down 1.46 percent from 103.27. The stock wrap printed 101.57. This note does not average them
Oil contract rollDo not trade itHighDays↔ This feed's Brent continuous screen is about six dollars under the settlement. A different contract. Not a front month fall
Reserve bufferDrawn downHigh1 to 3 mo↗ Strategic Petroleum Reserve at 282.6 million barrels, the lowest since October 1982. A buffer fact, not a price target
S&P 500Monday bounce, not a highHighDays↗ Up 0.70 percent, to 7,676.77. Still under the 21 Oct close of 7,757.17. Do not buy the bounce into the prints
NasdaqBounce, not a repairHighDays↗ Up 0.82 percent, to 26,169.38. Still under the 21 Oct close of 26,702.86
SemisBounce, still under the midweek highHighDays↗ This feed's fund rose 2.7 percent, to 541.62, and is still under 556.70. Do not average in
Fed pathHold Wednesday, rise risk in DecemberHigh1 to 3 mo↔ 90 percent priced for a hold. December rise odds at 80 percent in the gold close story. A cut is not the base
US 10-year indexFlatHigh1 to 3 mo↔ Closed at 4.986 percent, down 0.2 basis points. Cash story said 5.00 percent, unchanged. Do not average
5-year indexA little higherMedium1 to 3 mo↗ Closed at 4.824 percent, up 1.9 basis points. The front end did not ease
30-year indexA little lowerMedium1 to 3 mo↘ Closed at 5.301 percent, down 1.4 basis points. Not a bond buy
US inflationAlready printed, new number ThursdayHigh1 to 3 mo↔ September consumer prices at 3.7 percent are not new. Thursday is personal income and outlays, with the first read on output
US laborNo new print yetHigh1 to 3 mo↔ Last week's claims were near a 57 year low. Thursday is the next print. Do not trade last week as this week
GoldOne day bounce, still a rates tradeMedium3 to 12 mo↗ December settled at 4,038.40 dollars, up 0.8 percent. The fund rose 0.3 percent. Not a new war hedge
DollarFirmer by a littleLow1 to 4 wk↗ This feed closed at 102.05, up from 101.81. Not a trend
Energy equitiesHeld upMediumDays↔ Sector fund up 0.4 percent while the settlement fell. Own the cash flow. Do not chase either print
ChinaNo new decisionMedium1 to 3 mo↔ China fund up 0.6 percent. The broad emerging fund fell 0.3 percent. No new policy. Do not chase
MidtermsSeven days outMediumDays↔ 3 Nov. The strike lean in the reporting is after the vote. Headlines, not a position
ECBThursday, with the US printMediumDays↗ Decision day is 29 Oct. Monday coverage leans to a pause. A pause is not a cut

Portfolio

Position Weight Rationale
Overweight
Crude / energy (USO, XOM, CVX)+2%Hold it. Brent settled at 115.81 dollars and US crude settled at 101.76. The strait is not open. The reserve buffer is at a 1982 low. The strike clock is why you do not sell. The Tehran meeting is why you do not add. Neither is a settlement of the war
Power / utilities (XLU)+1%Hold the starter. It is the cleaner way to own the power demand behind the technology spending. The fund closed at 42.55, flat. That is not a reason to add
Energy equity cash flows+1%The sector fund rose 0.4 percent while crude settled lower. Own the cash flow, not the crude print. Do not chase, and do not sell the sleeve because the settlement dipped
Cash / short billsHighThe yield index closed at 4.986 percent. The bill index closed at 4.025 percent. The score is 39. Cash is paid to wait through Wednesday and Thursday
Underweight
Long duration (TLT, IEF)−5%The yield index is 4.986 percent. The long bond fund rose 0.4 percent. Do not cover before Wednesday's statement. Do not add to the short either
Semis / high beta tech (SMH)−2%The fund rose 2.7 percent on Monday and is still under the 21 Oct high on this feed. A listing filing is not an earnings print. Do not buy the bounce
Airlines / transport (DAL, AAL)−2%No opening, no ship count. A meeting in Tehran is not a fuel bill falling. Wait for the waterway, not the headline
China cyclicals (FXI, EEM)−2%The China fund rose 0.6 percent. The broad emerging fund fell 0.3 percent. No new policy decision. Do not chase the dip
Consumer discretionary (XLY)−1%The fund rose 1.0 percent. The fuel bill is still the story until Thursday says otherwise. A one day bounce is not a tax cut
Defense (ITA, LMT)0%The fund rose 2.4 percent. That is the strike clock being priced, not an order. Do not add on the readiness line
Gold (GLD)0%December settled up 0.8 percent. The fund rose 0.3 percent. The crude sleeve is the war hedge. No new entry
Financials (XLF)0%The fund rose 0.2 percent, to 56.02. A hawkish hold helps net interest margin and hurts credit. Those offset. Keep it small
Hedges
Long volatility into Wednesday and ThursdaySmallVIX closed at 18.39, under 20, into a policy decision and the large technology prints. Cheaper than Friday. Sized as insurance, not as a position

Cash stays high. A 39 score says the CAUTION label is further off than it was yesterday, and the dip bid is still off. It does not say buy duration, sell energy, or buy chips. Trade 39 as a 4.986 percent yield index, a Brent settlement of 115.81 dollars, a US crude settlement of 101.76 dollars, a strait that is not open, and a gold market that bounced because oil eased. The talks are a reason to hold the crude sleeve. They are not a reason to sell it. The strike clock is a reason to hold it. It is not a reason to add it.

The next two weeks

Date Event Importance
27 Oct (Tue)US policy meeting, first day. No projections at this meeting. Israel votes. That is a headline, not a US positionHigh
28 Oct (Wed)US policy decision. Coverage puts the statement at 14:00 ET and the press conference at 14:30 ET. Microsoft and Alphabet report after the close. The calendar feed stamps both at 16:00 ET. That stamp is the feed, not a company release clockHigh
29 Oct (Thu)September personal income and outlays, and the first read on third quarter output, both at 8:30 ET. Weekly claims the same morning. European Central Bank decision and press conference. Amazon reports after the close. The calendar feed stamps Intel after the close and Eli Lilly at 08:00 ETHigh
30 Oct (Fri)Month end. The calendar feed stamps Exxon and Chevron at 08:00 ET. A month end rebalance can move the long end without newsMedium
2 Nov (Mon)Apple reports. The calendar feed stamps 15:00 ET. Outside this weekMedium
3 Nov (Tue)US midterms. The strike lean in the reporting is after this vote. Headlines, not a positionMedium
4 Nov (Wed)September trade in goods and services at 8:30 ET. The edge of this windowLow
17 Nov (Tue)Next Nvidia date. The calendar feed stamps 15:00 ET. Outside this window. The prior quarter has already been reported. Do not treat 17 Nov as this weekMedium
8 to 9 Dec (Tue to Wed)Following US policy meeting, with projections. Outside this window. Monday coverage leans to a rise. A cut is not the base case in this noteHigh

Weekdays above match the calendar. September consumer prices already printed. September payrolls already printed. Meta already reported on 21 Oct. Do not treat any of those as a new release. The tanker damage count from the strait is older than this note and is not overnight news.

Scorecard

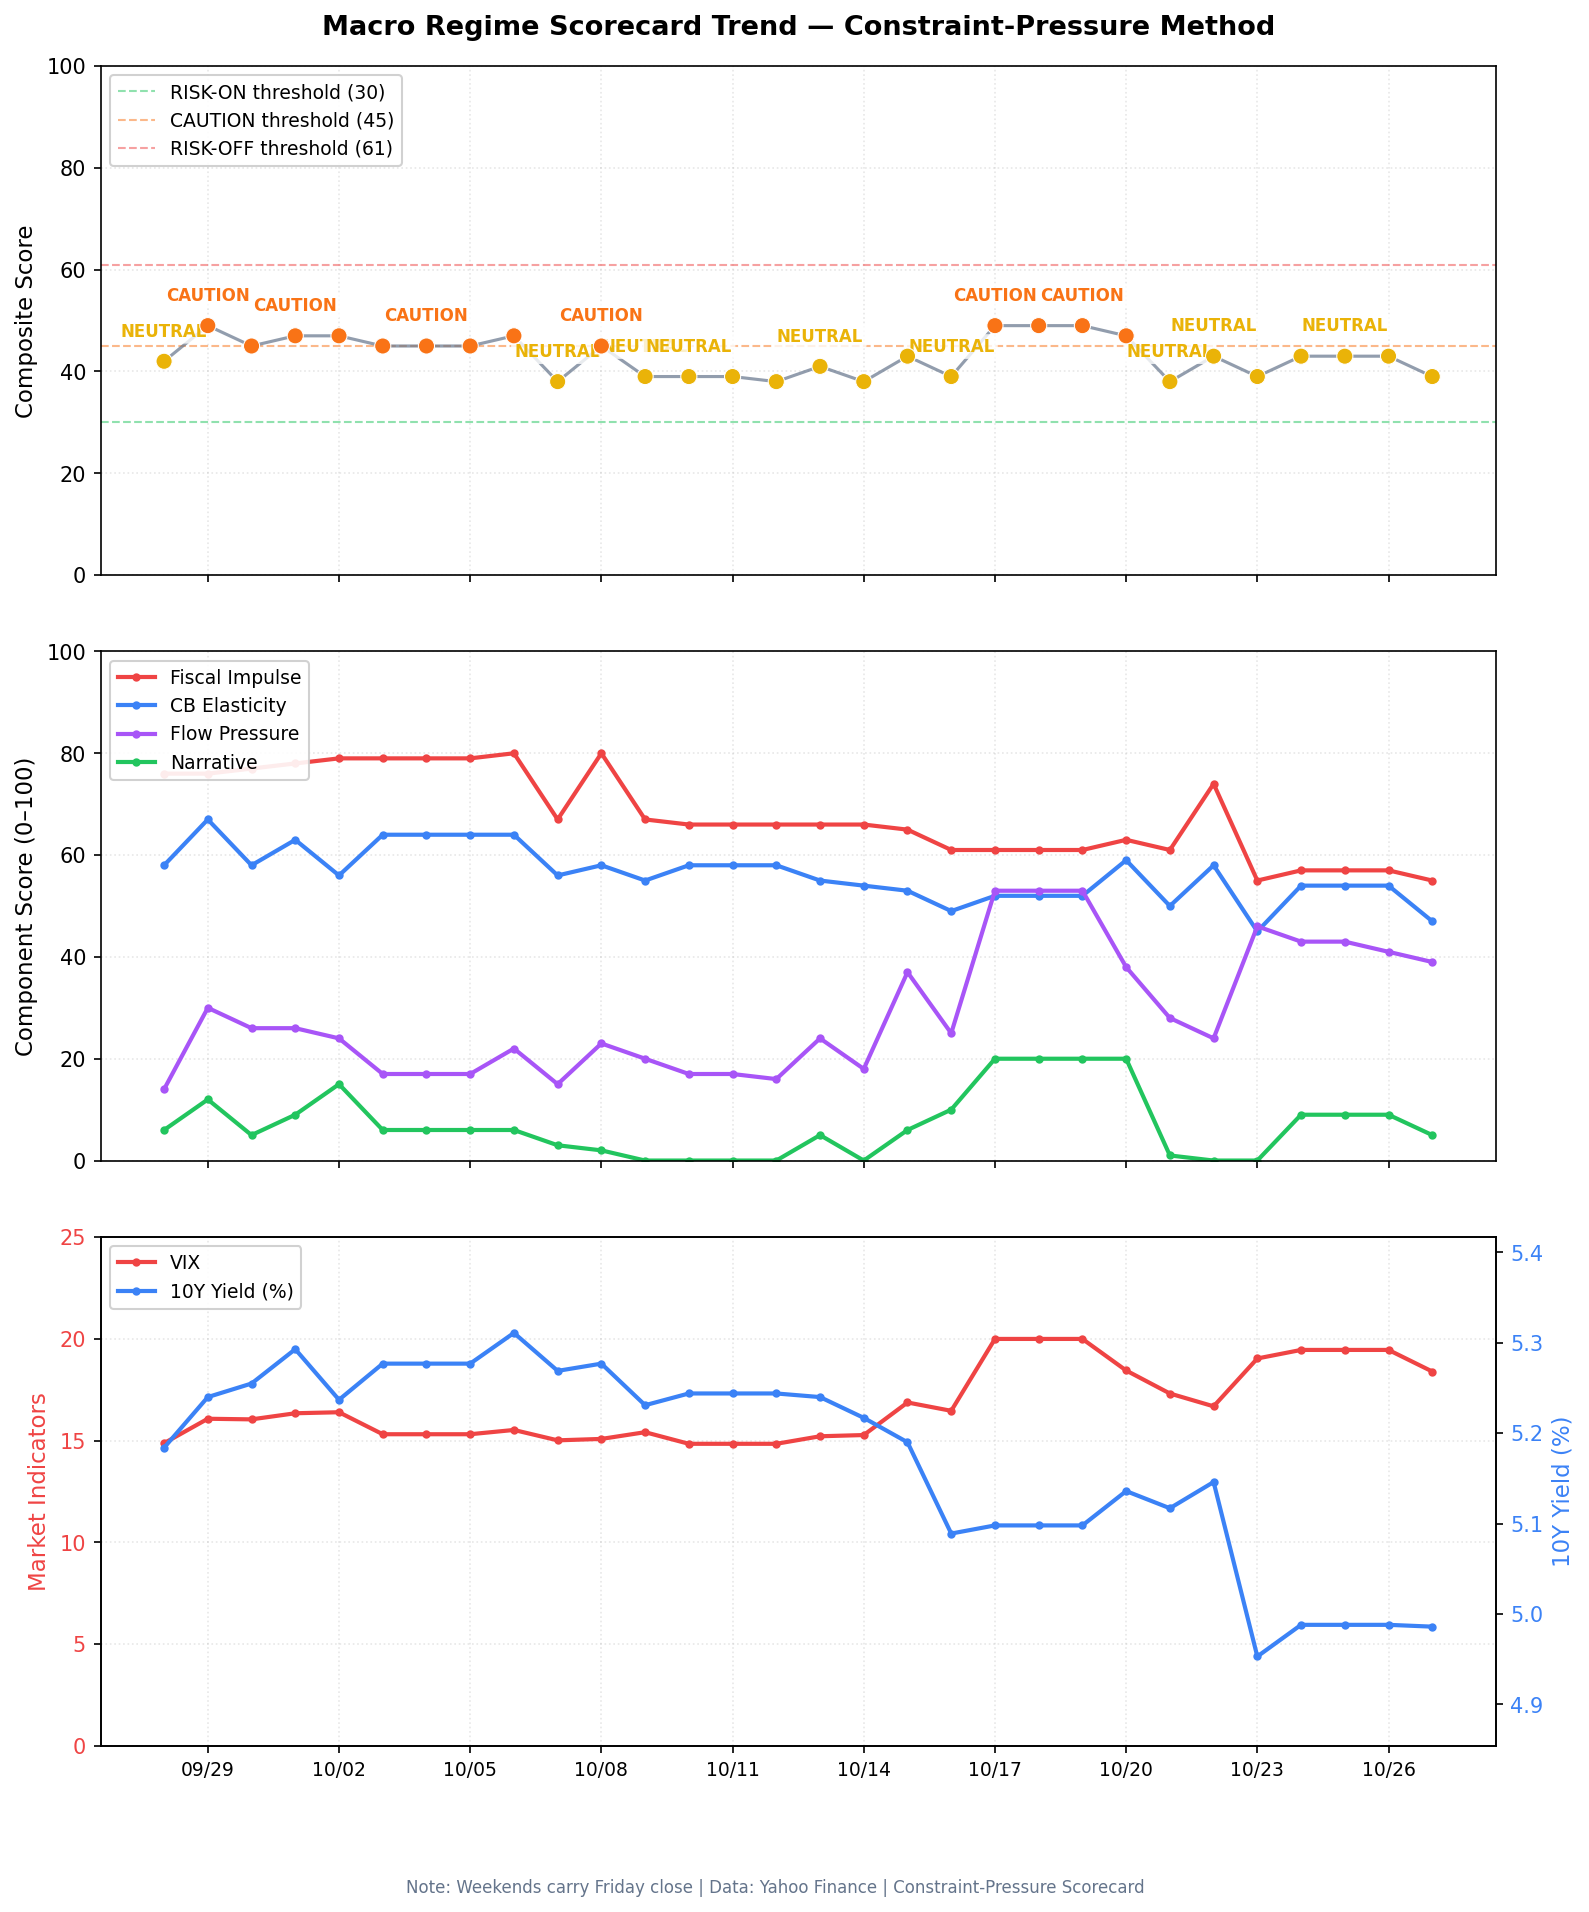
39 of 100 sits in NEUTRAL. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse55Down 2 points from 57. The yield index closed at 4.986 percent, down 0.2 basis points. The level near 5 percent is still the constraint. The day was not. Still not a bond bid
CB Elasticity47Down 7 points from 54. The largest move in the score. A hold on Wednesday is the priced base. The 5-year index rose 1.9 basis points, so the front end did not ease. The score eased because the 10-year did not jump. Do not read 47 as a cut
Flow Pressure39Down 2 points from 41. VIX closed at 18.39, down 1.06 points, under 20. Credit was quiet. The high yield fund and the investment grade fund each rose about 0.2 percent. Not a stress day
Narrative Coherence5Down 4 points from 9. One story was traded. Oil settled lower, stocks rose, gold rose, the yield index was flat. A coherent story scores low because there is nothing to arbitrage between narratives. Low is not a buy signal
Composite39NEUTRAL

The label did not flip. The score is 39. Yesterday it was 43. The line for CAUTION is 45. The line for RISK-ON is 30. The line for RISK-OFF is 61. A higher score means more stress. This score fell 4 points. It did not cross 45. It did not cross 30. It is 6 points from CAUTION and 9 points from RISK-ON, with a policy decision, an inflation print and the large technology earnings inside the next three sessions. A 39 going into that calendar is a hold, not a signal.

Data through the 26 Oct 2026 US close. This is a Tuesday edition after that close. The US cash market for Tuesday has not opened. A later screen is not a new settlement.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.