🌍 Market Regime — September 02, 2026
September 02, 2026 · Top 5 regime drivers, risk matrix, positioning
 US hit Iran again. Oil jumped 6 percent yesterday.
 Stocks fell. The 10 year yield hit 4.80 percent. A September hike is still in play into Friday jobs.
Wednesday edition — US cash, oil, gold and the dollar are through the 1 Sep 2026 close. Asia is a live Wednesday morning tape.
TAPE FLIP toward caution. Tuesday was the first true risk-off session of this Hormuz round. The scorecard is still NEUTRAL at 42. It is closer to caution than it was on Monday.
📊 Markets Bar
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,631.47 | -0.71% (Tue) |
| VIX | 16.34 | +9.52% (Tue) |
| US 10Y Yield | 4.80% | +3.8 bp (Tue) |
| US 5Y Yield | 4.56% | +5.0 bp (Tue) |
| Brent Crude | $95.62 | +5.67% (Tue) |
| WTI Crude | $90.95 | +6.05% (Tue) |
| Gold | $4,350 | -1.83% (Tue) |
| Dollar Index (DXY) | 99.77 | +0.34% (Tue) |
Nasdaq fell 1.03 percent yesterday. The Dow fell 0.79 percent. Gold sold off even as oil jumped. Real yields beat the war bid.
Top 5 Regime Drivers
1. ESCALATION. Fresh US Strikes. Oil Jumped About 6 Percent.
Signal. US Central Command said American forces began striking IRGC targets in Iran at noon ET yesterday, after projectiles hit tankers in the Strait of Hormuz and Iran fired at US bases (Reuters, CENTCOM, 1 Sep). WTI futures closed at $90.95 yesterday, up 6.05 percent. Brent closed at $95.62, up 5.67 percent. That is a five-week high on the futures tape. Iran warned it would keep restricting Hormuz traffic. Treasury Secretary Scott Bessent said Washington will add bank sanctions to squeeze Tehran (AP, Reuters, 1 Sep). Early Wednesday, Brent extended toward $95.50 in Asia.
Macro Impact. Energy is again the inflation swing factor into a live September hike debate. A wider Hormuz break would reprice oil, shipping, defense, and the FOMC in the same session. This is still not a full strait shutdown. Gulf barrels are still moving, often dark. Size for a binary week, not a new crude bull market.
Positioning. Overweight energy (XLE, USO, XOM, CVX). Small defense sleeve (ITA, LMT). Long Brent call spreads as a tail. Do not re-lever airlines. Gold failed as a hedge yesterday. Keep only a small GLD sleeve.
Key Sources. Reuters 1 Sep “Oil prices settle up more than $4 a barrel on renewed US-Iran fighting”; Reuters 1 Sep “Wall Street ends lower as higher yields, rising oil prices mark shaky start to September”; AP 30 to 31 Aug Bessent sanctions; CENTCOM 1 Sep.
2. Global Bonds Sold Off. A September Hike Is Still Live.
Signal. The US 10-year yield closed at 4.80 percent yesterday, the highest since January 2025. The 5-year yield closed at 4.56 percent. Japan’s 10-year yield touched 3 percent for the first time since 1996 (WSJ, AMWatch, 1 Sep). Fed funds futures still implied around a 66 percent chance of a September hike (Quartz, 1 Sep). Chair Kevin Warsh’s Jackson Hole warning is four days old. Dearer oil is what kept it alive.
Macro Impact. Sticky energy plus a hawkish chair is higher for longer, not cuts. Equities had not fully voted until yesterday. They did. A confirmed hike into a soft labor market is still a policy-error risk. The dollar closed at 99.77. Front-end yields stay bid until payrolls contradict the oil tape.
Positioning. Overweight financials (XLF, JPM) on a higher curve. Underweight long duration (TLT) and rate-sensitive small caps (IWM). Long dollar versus yen. Do not full-price a hike before Friday’s jobs report.
Key Sources. Reuters 1 Sep close; WSJ 1 Sep Japan 10-year at 3 percent; Quartz 1 Sep on hike odds; NY Post 1 Sep 10-year at 4.796 percent.
3. 📉 September Opened Weak. VIX Finally Moved.
Signal. The S&P 500 fell 0.71 percent yesterday to 7,631.47. Nasdaq fell 1.03 percent. The VIX jumped 9.52 percent to 16.34. That is the tell. Monday’s report still called vol asleep near 15. It is not. South Korea’s Kospi fell as much as 3 percent at the Wednesday open. Japan’s Nikkei sank more than 2 percent (Reuters, Yonhap, 2 Sep). Nvidia fell 1.51 percent yesterday. The semiconductor ETF (SMH) fell 2.05 percent.
Macro Impact. Three overlapping risks sit on the same tape. Hormuz. A live hike debate. September seasonality. Vol is no longer free, but it is not expensive either. Breadth was poor. High-beta lost more than low-vol. Sell strength into Friday. Do not chase the August high.
Positioning. Long cheap tails (put spreads on the S&P, not naked shorts). Tactical equity, not structural. Reduce into any bounce ahead of payrolls. Quality (SPHQ) over cyclicals.
Key Sources. Reuters 1 Sep “Indexes down: Dow 0.79%, S&P 500 0.71%, Nasdaq 1.03%”; Reuters 2 Sep “Asian markets tumble as US-Iran fighting lifts oil and bond yields”; yfinance 1 Sep closes.
4. JOLTS Was Soft-Ish. Friday Payrolls Still Decide.
Signal. July JOLTS openings printed at 7.27 million, just under the 7.30 million forecast, after a sharp downward revision to the prior month (Reuters, FXStreet, 1 Sep). ISM manufacturing fell to 54.6 in August from 55.6, below the 55.2 consensus. Factories still expanded for an eighth month. The prices-paid index held at 71.1 (ISM, Reuters, 1 Sep). ADP and the Beige Book print today. August nonfarm payrolls print Friday. Consensus is around a 53,000 gain after July’s 23,000 job loss. Unemployment is expected to stay at 4.1 percent (WSJ survey, 1 Sep).
Macro Impact. Soft labor versus hot factory prices, now with $91 oil, is the Fed’s bind. Warsh called the labor market consistent with full employment. The data still look softer than that. A second down payrolls month would knock September hike odds back. A hot print plus dearer oil would push the scorecard into caution.
Positioning. Neutral duration into Friday. Keep quality over cyclicals that need a tight labor market. Watch IWM and high-yield (HYG) as risk canaries. Do not fade the dollar before the print.
Key Sources. Reuters and FXStreet 1 Sep JOLTS; ISM 1 Sep Manufacturing PMI; Reuters 1 Sep factory activity; WSJ 1 Sep data-week survey.
5. 🤖 AI Capex Is Intact. Chips Paid Again. Broadcom Reports Tonight.
Signal. The AI build-out is not the broken story. The tape still de-rates the stocks when yields and oil jump together. Nvidia fell 1.51 percent yesterday. AMD fell 2.36 percent. SMH fell 2.05 percent. Korea’s chip names led the Kospi lower this morning.
Broadcom is due after the US close today. That print is the near-term check on AI demand, not a rerun of Nvidia’s 26 Aug numbers.
Macro Impact. Power, cooling, and data centers remain the slower way to stay long the cycle. A Broadcom miss would hit the whole semiconductor complex into payrolls. A beat would not erase $91 oil or a 4.80 percent 10-year. Treat chips as a dip-buy cycle, not a September momentum long.
Positioning. Buy NVDA, AMD, and AVGO on dips, not into strength. Overweight DLR, EQIX, XLU, NEE. Wait for Broadcom before adding size. Do not read yesterday’s chip drop as a broken capex cycle.
Key Sources. yfinance 1 Sep closes; Broadcom 2 Sep earnings date; Reuters 2 Sep Asia open.
Summary Risk Matrix
| Factor | Direction | Conviction | Horizon | Δ vs yesterday |
|---|---|---|---|---|
| Geopolitics | Escalating (binary) | High | Days to 1 mo | ↗️ Tuesday CENTCOM barrage after the weekend exchange |
| Oil | Higher near term | High | 1-4 wk | ↗️ WTI closed at $90.95, Brent at $95.62 |
| US Rates | Higher for longer | High | 1-3 mo | ↗️ 10-year at 4.80%. Japan 10-year touched 3% |
| US Equities | Risk-off, still rich | Medium | 1-4 wk | ↗️ FLIP. VIX 16.34, not 15 |
| US Growth | Softening | High | 3-6 mo | → JOLTS 7.27 million. NFP Friday |
| Inflation | Sticky, oil risk up | High | 6-12 mo | ↗️ ISM prices 71.1 plus $91 oil |
| AI Capex | Intact, tape noisy | High | 12+ mo | ↘️ Chips sold with yields. Broadcom tonight |
| Gold | Real-rate headwind | Medium | 3-12 mo | ↘️ Fell 1.83 percent yesterday despite strikes |
| USD | Bid | Medium | 1-3 mo | ↗️ DXY 99.77 |
Portfolio Construction
| Position | Weight | Rationale |
|---|---|---|
| Overweight | ||
| Energy (XLE, USO, XOM, CVX) | +4% | Hormuz premium is live. WTI closed at $90.95 yesterday |
| Financials (XLF, JPM) | +4% | Higher curve. Hike talk supports net interest |
| Defense (ITA, LMT) | +2% | Sustained war footing, not a ceasefire |
| Data Centers (DLR, EQIX) | +3% | Multi-year power and rack demand |
| Utilities (XLU, NEE) | +2% | AI load plus defensive yield |
| Quality (SPHQ) | +3% | Soft growth, split Fed, keep balance sheets clean |
| Underweight | ||
| Long duration (TLT) | -4% | 10-year at 4.80%. Fiscal score 65 |
| Small Caps (IWM) | -3% | Rate sensitive. Need a tight labor market they do not have |
| Airlines / XLY | -3% | Fuel plus September seasonality |
| Semis into strength (SMH) | -2% | Hold the dip-buy. Wait for Broadcom |
| China cyclicals (FCX, VALE) | -2% | Still no reflation impulse from Asia demand |
Gold is a small hedge, not a momentum long. It fell 1.83 percent yesterday while oil jumped.
Key Events / Watchlist (Next 2 Weeks)
| Date | Event | Importance |
|---|---|---|
| 2 Sep (Wed) | ADP Payrolls (Aug), Beige Book, Broadcom earnings after the close | High |
| 3 Sep (Thu) | ISM Services PMI, jobless claims, productivity | High |
| 4 Sep (Fri) | US Nonfarm Payrolls (Aug) | Critical |
| 7 Sep (Mon) | US Labor Day. Markets closed | Low |
| 10 Sep (Thu) | ECB rate decision | High |
| 11 Sep (Fri) | US CPI (Aug) | Critical |
| 15 Sep (Tue) | FOMC meeting starts | High |
| 16 Sep (Wed) | FOMC decision and dot plot | Critical |
Regime Scorecard (Live — 1 Sep Close)
| Variable | Score | Interpretation |
|---|---|---|
| Fiscal Impulse | 65 | 10Y at 4.80% — moderately restrictive |
| CB Elasticity | 52 | 5Y at 4.53% — below neutral, Fed constrained by inflation above target |
| Flow Pressure | 33 | VIX 16.3 — lowest reading in weeks, low fear despite Iran/oil |
| Narrative Coherence | 6 | SPY -0.6%/5d | QQQ-SPY breadth +1 |
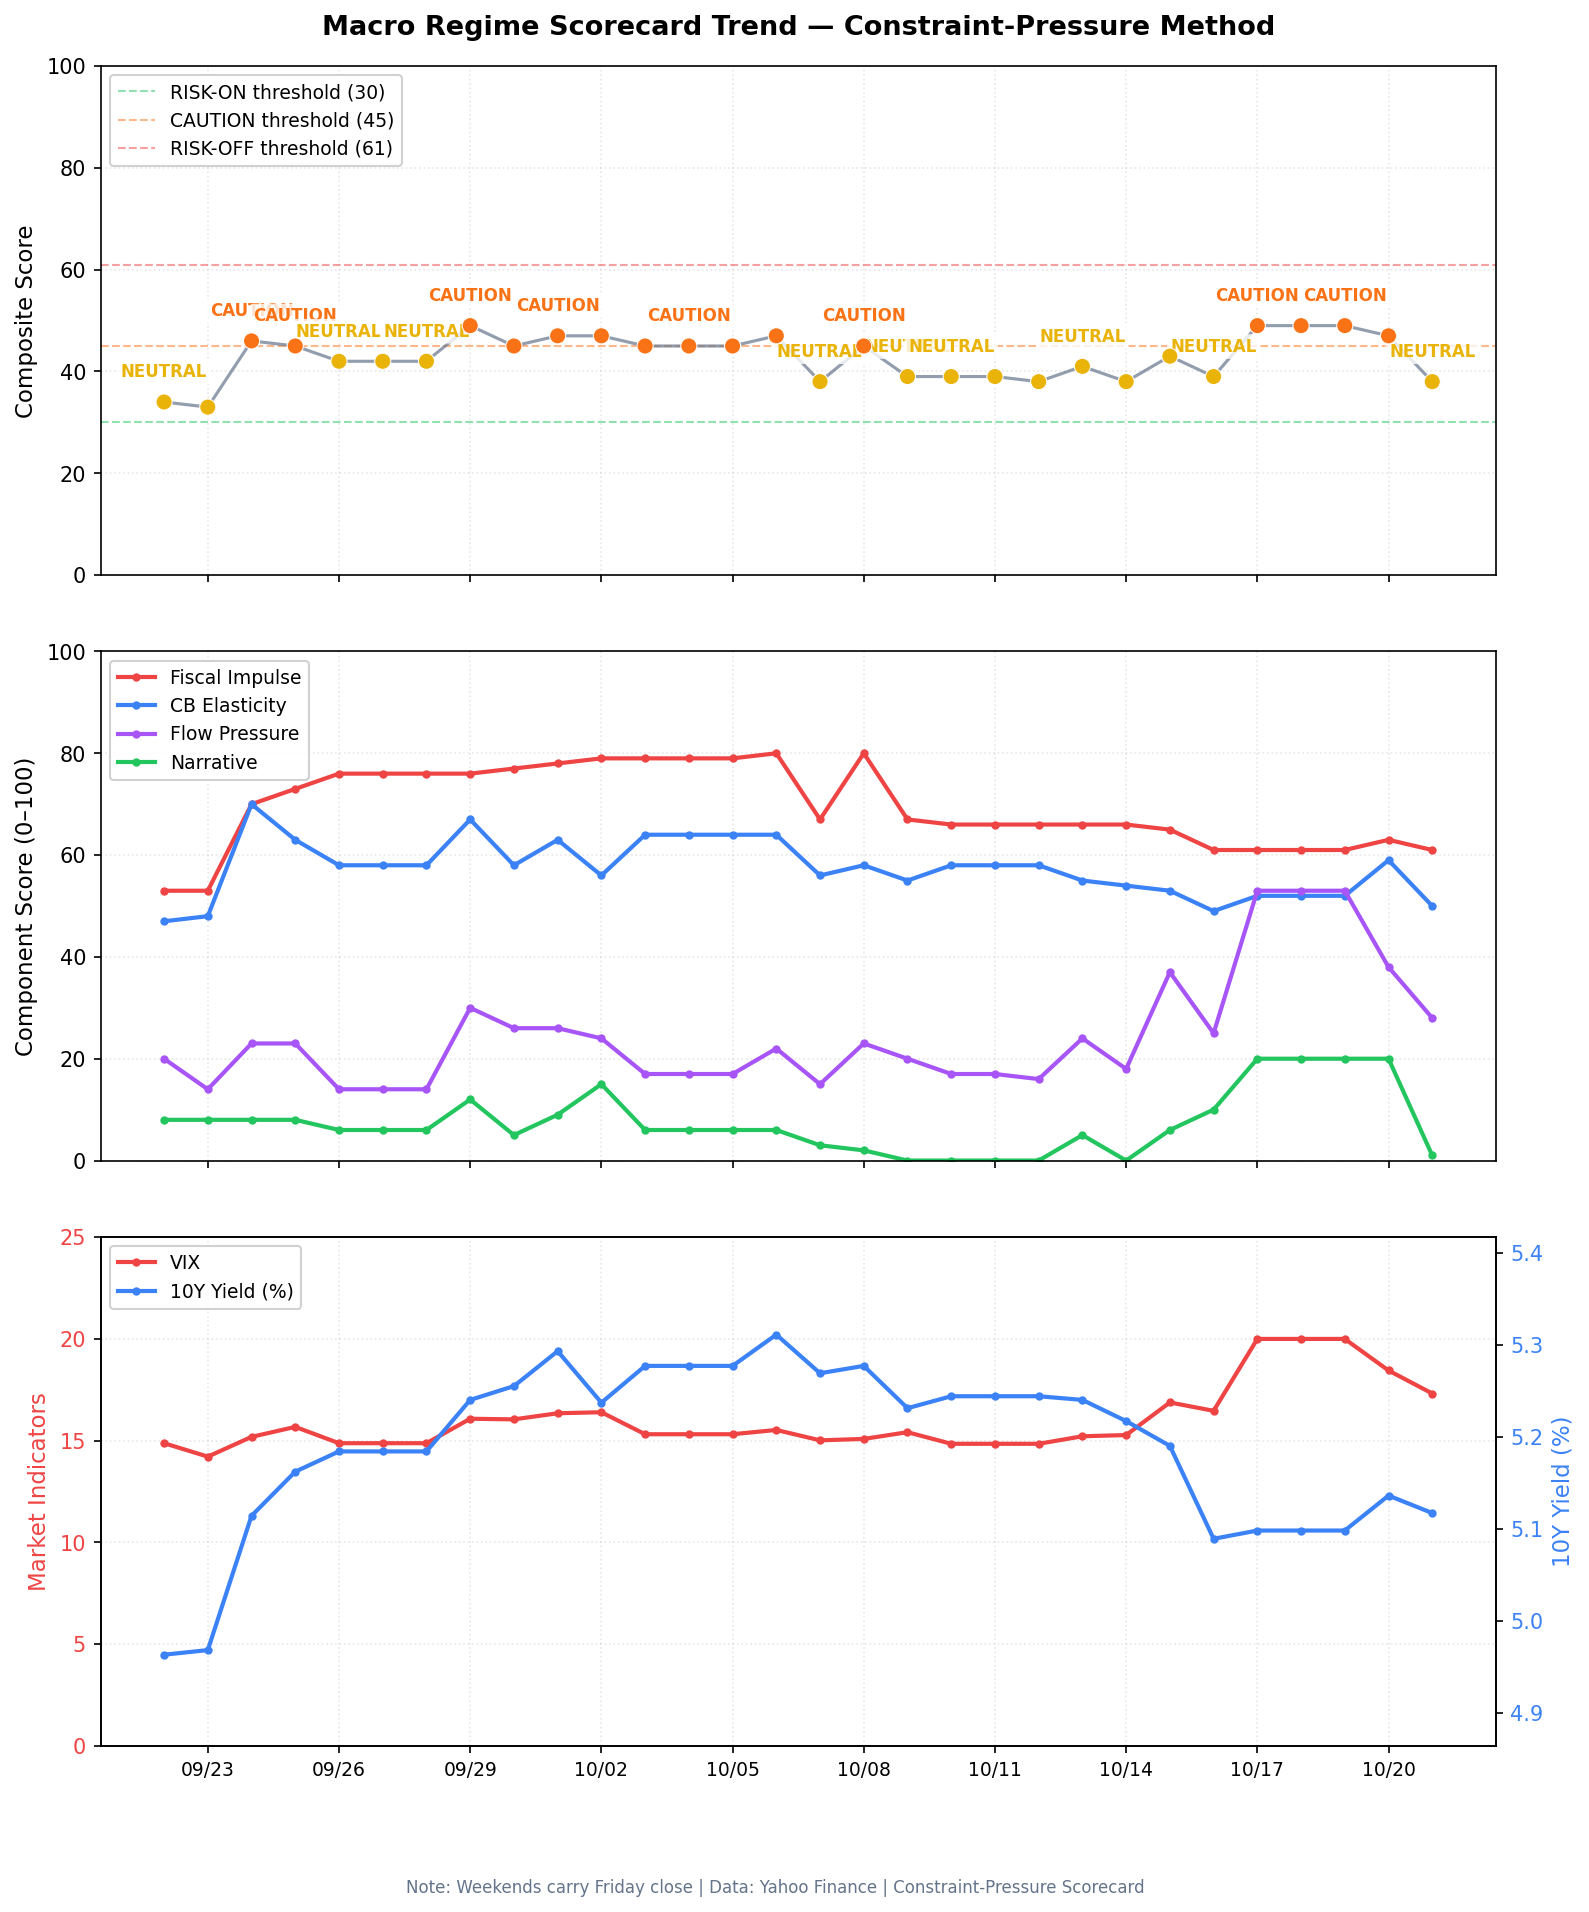
| Composite | 42 | NEUTRAL |
Regime thresholds: <30 RISK-ON | 30-44 NEUTRAL | 45-60 FÖRSIKTIGHET | ≥61 RISK-OFF
The scorecard registers NEUTRAL — VIX at 16.34, 10Y at 4.80%. Stress is moderate. A VIX spike or a 10Y jump would push toward FÖRSIKTIGHET.
No scorecard regime flip versus Monday (37 to 42). Both days are NEUTRAL. Flow pressure rose from 18 to 33 as VIX woke up. The live overlay is caution. A hot payrolls print plus $91 oil would likely push the composite through 45. A weak print would knock it back.
2 Sep 2026, 04:50 CEST | Next review: 3 Sep 2026 (Thu)
Score Trend (30 days)
September 02, 2026 08:10 CEST (live scorecard update) | Next full review: Monday 07 Sep 2026