🌍 Market Regime — September 01, 2026
September 01, 2026 · Top 5 regime drivers, risk matrix, positioning
 US and Iran traded fire. WTI jumped 3.8 percent.
 Warsh kept a September hike in play. The S&P 500 fell 0.3 percent yesterday. Friday jobs data is the next Fed test.
Tuesday edition — US cash data through 31 Aug 2026 close. Asia includes 1 Sep prints.
No scorecard regime flip. Monday priced Sunday’s Iran strikes without a panic. Oil is bid. Equities only slipped. Payrolls on Friday still decide the hike call.
📊 Markets Bar
| Asset | Level | Change |
|---|---|---|
| S&P 500 | 7,686.14 | -0.3% (Mon) |
| VIX | 14.92 | still calm |
| US 10Y Yield | 4.76% | +4 bp (Mon) |
| US 5Y Yield | 4.51% | higher with the curve |
| Brent Crude | $88.89 | -0.5% (Mon vs Fri) |
| WTI Crude | $86.56 | +3.8% (Mon vs Fri) |
| Gold (GLD) | $408.42 | -0.1% (Mon) |
| Dollar Index (DXY) | 99.47 | +0.3% (Mon) |
The S&P 500 fell 0.3 percent yesterday to 7,686.14. The Dow fell 0.7 percent. The Nasdaq slipped 0.1 percent. Energy was the exception. XLE rose 2.0 percent yesterday. Japan’s Nikkei fell 0.26 percent this morning. Korea’s Kospi fell 0.18 percent. VIX at 14.92 still says this is not a risk-off tape.
Top 5 Regime Drivers
1. Fire Traded Again. WTI Jumped. The Strait Stayed the Story.
Signal. US forces struck two Iranian launchers on Larak Island on Sunday, the first American hits in about a month. Iran fired missiles at US bases in Jordan. Jordan said it intercepted them. The UAE said on Monday it downed an Iranian drone over its waters. President Trump said Iran would be hit “hard” if the firing continued (PBS, AP, NBC, 31 Aug to 1 Sep).
Macro Impact. WTI jumped 3.8 percent yesterday. USO rose 3.1 percent. XLE rose 2.0 percent. Front-month Brent on the cash tape slipped 0.5 percent, so the complex is not a clean melt-up. Gasoline already had its most expensive August on record. Dearer crude feeds the inflation case Chair Warsh just revived. A wider exchange would reprice energy, defense, and the September Fed path in the same session.
Positioning. Keep energy overweight (XLE, USO). Hold a small defense sleeve (ITA). Gold (GLD) barely moved yesterday after Friday’s washout, so use it as a tail hedge, not a momentum long. Size for a binary week. This is not yet a full Hormuz shutdown trade.
Key Sources. PBS 31 Aug “U.S. and Iran trade strikes for first time in weeks”; AP 31 Aug “Oil prices rise and stocks fall”; NBC 31 Aug “Trump threatens to hit Iran hard”.
2. Warsh Kept the Hike Live. Barclays Joined the Hawk Camp.
Signal. Fed Chair Kevin Warsh told Jackson Hole on Friday that inflation has not improved enough and that the Fed may have work to do. Barclays on Monday switched to two 25 bp hikes, September and December. It had been on hold for the rest of the year. CME FedWatch put September hike odds near 60 percent (Reuters, 31 Aug).
Macro Impact. The 10-year yield rose to 4.76 percent yesterday. The 5-year yield rose to 4.51 percent. The dollar held near 99.47. Sticky energy plus a hawkish chair is the path to caution, not to a melt-up. The funds rate is still 3.50 to 3.75 percent. Soft labor data this week can still knock the hike odds back.
Positioning. Stay overweight financials (XLF) on a higher curve. Stay underweight long duration (TLT) and rate-sensitive small caps (IWM). Long dollar versus yen is cleaner than shorting the S&P into payrolls.
Key Sources. Reuters 31 Aug “Barclays sees two more Fed rate hikes this year after Warsh speech”; CME FedWatch via Reuters 31 Aug.
3. Monday Voted. It Did Not Panic.
Signal. The S&P 500 fell 0.3 percent yesterday. The Dow fell 0.7 percent. The Nasdaq slipped 0.1 percent. Almost every sector finished red. Energy was the exception. Nvidia rose 1.5 percent yesterday. AMD rose 1.1 percent. The VIX closed at 14.92 (AP, 31 Aug).
Macro Impact. Sunday’s strikes and Friday’s hawkish speech produced a down day, not a crash. August still finished higher for the S&P and the Nasdaq. Flow pressure on the scorecard remains low because implied vol never left the teens. That calm can fade fast if payrolls or a wider Iran exchange land this week.
Positioning. Do not chase a crash hedge at VIX 15. Keep quality (SPHQ) over cyclicals. Fade 10-year spikes rather than short the whole index into Friday.
Key Sources. AP 31 Aug “How major US stock indexes fared Monday 8/31/2026”; yfinance 31 Aug closes.
4. Soft Jobs Still Argue the Other Way. Friday Is the Test.
Signal. ISM manufacturing and July JOLTS print today. ADP and the Beige Book land tomorrow. August nonfarm payrolls print on 4 Sep (Fri). July payrolls were a 23,000 job loss. Unemployment is 4.1 percent. BLS said last week that payrolls through March were overstated by 79,000 (BLS calendar; CNBC 7 Aug; NYT 28 Aug).
Macro Impact. Soft labor versus sticky prices, now with a fresh oil spike, is the Fed’s bind. Warsh called the labor market consistent with full employment. The data look softer than that. A weak payrolls print would knock September hike odds back. A hot one plus dearer oil would push the scorecard toward caution.
Positioning. Do not full-price a September hike before Friday. Keep quality over cyclicals that need a tight labor market. Fade 10-year spikes rather than short the whole curve.
Key Sources. BLS September 2026 release schedule; CNBC 7 Aug “U.S. economy unexpectedly lost 23,000 jobs in July”; NYT 28 Aug jobs revision.
5. 🤖 AI Capex Holds. Broadcom Reports Tomorrow.
Signal. Nvidia rose 1.5 percent yesterday after Friday’s 4.57 percent drop. AMD rose 1.1 percent. Broadcom reports after the close on 2 Sep (Wed). China’s official factory PMI stayed at 49.8 in August, still under 50. The private RatingDog factory PMI printed 51.5 this morning, above the 50.9 forecast (yfinance 31 Aug; NBS 31 Aug; investingLive 1 Sep).
Macro Impact. The capex cycle is intact. The tape can still de-rate the stocks when yields and oil jump together. A China PMI still under 50 on the official gauge does not restart commodity demand. Power, cooling, and data centers remain the slower way to stay long the build-out.
Positioning. Buy NVDA, AMD, AVGO on dips, not into strength. Overweight DLR, EQIX, XLU, NEE. Wait for Broadcom before adding size. Stay underweight FCX and VALE until the official PMI holds above 50.
Key Sources. yfinance 31 Aug closes; Broadcom earnings date 2 Sep; NBS 31 Aug PMI; investingLive 1 Sep RatingDog PMI.
Summary Risk Matrix
| Factor | Direction | Conviction | Horizon | Δ vs yesterday |
|---|---|---|---|---|
| Geopolitics | Escalating (binary) | High | Days to 1 mo | → Fire continued. UAE intercept. No ceasefire |
| Oil | Higher near term (WTI) | Medium | 1-4 wk | ↗️ WTI jumped 3.8 percent yesterday |
| US Rates | Higher for longer | Medium | 1-3 mo | ↗️ 10Y at 4.76%. Barclays now two hikes |
| US Growth | Softening | High | 3-6 mo | → Payrolls week is live |
| Inflation | Sticky, oil risk up | Medium | 6-12 mo | → Energy is still the swing factor |
| China Growth | Weak, slight bounce | Medium | 6-12 mo | → Official PMI 49.8. Private PMI 51.5 |
| AI Capex | Accelerating | High | 12+ mo | ↗️ Nvidia bounced 1.5 percent yesterday |
Portfolio Construction
| Position | Weight | Rationale |
|---|---|---|
| Overweight | ||
| Energy (XLE, USO) | +4% | Monday confirmed the Hormuz premium in WTI |
| Financials (XLF) | +4% | Higher curve and hike talk support net interest |
| Defense (ITA) | +2% | Fire is still live. Keep a small sleeve, do not chase |
| Data Centers (DLR, EQIX) | +3% | Multi-year power and rack demand |
| Utilities (XLU, NEE) | +2% | AI load plus defensive yield. Skip the broken California names |
| Quality (SPHQ) | +3% | Soft growth, split Fed, keep balance sheets clean |
| Underweight | ||
| Long duration (TLT) | -4% | 10-year at 4.76%. Fiscal score 64 |
| Small Caps (IWM) | -3% | Rate sensitive. Need a tight labor market they do not have |
| China cyclicals (FCX, VALE) | -3% | Official PMI still under 50 |
| Semis into strength (SOXX) | -2% | Hold the dip-buy. Wait for Broadcom |
Gold is a small rebuilt hedge, not a short and not a momentum long. Friday’s washout did not reverse yesterday.
Key Events / Watchlist (Next 2 Weeks)
| Date | Event | Importance |
|---|---|---|
| 1 Sep (Tue) | ISM Manufacturing PMI, JOLTS (Jul) | High |
| 2 Sep (Wed) | ADP Payrolls (Aug), Beige Book, Broadcom earnings after close | High |
| 3 Sep (Thu) | ISM Services PMI, Productivity and Costs | High |
| 4 Sep (Fri) | US Nonfarm Payrolls (Aug) | Critical |
| 7 Sep (Mon) | US Labor Day. Markets closed | Low |
| 10 Sep (Thu) | ECB rate decision | High |
| 11 Sep (Fri) | US CPI (Aug) | Critical |
| 15 Sep (Tue) | FOMC meeting starts | High |
| 16 Sep (Wed) | FOMC decision and dot plot | Critical |
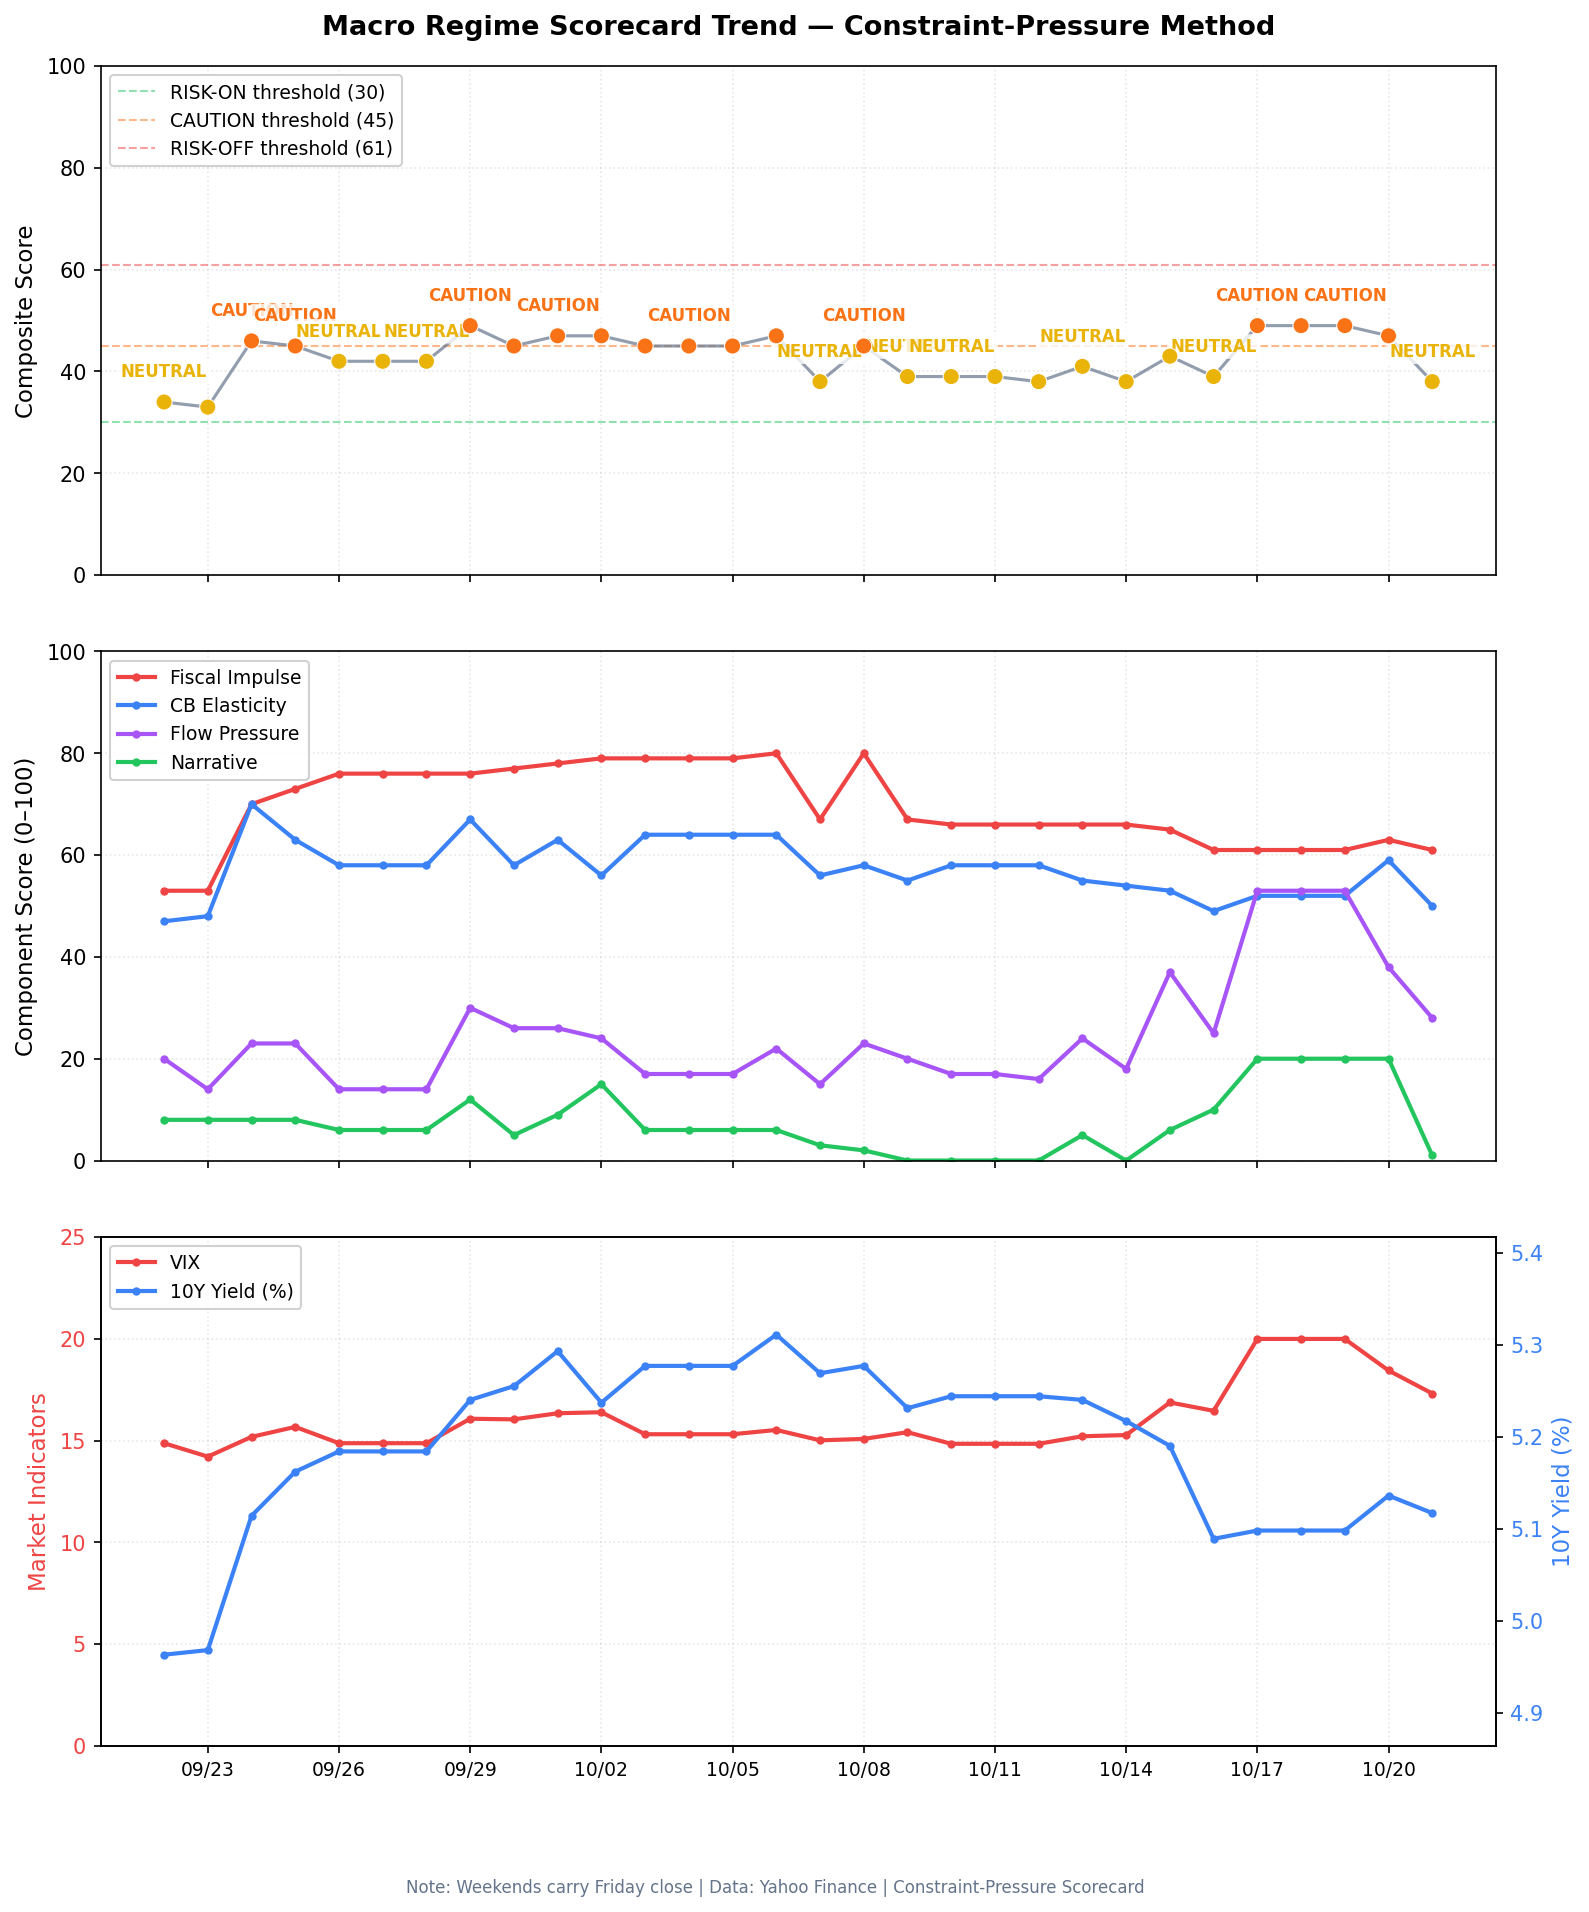
Regime Scorecard (Live — 31 Aug Close)
| Variable | Score | Interpretation |
|---|---|---|
| Fiscal Impulse | 64 | 10Y at 4.76% — moderately restrictive |
| CB Elasticity | 51 | 5Y at 4.49% — below neutral, Fed constrained by inflation above target |
| Flow Pressure | 18 | VIX 14.9 — lowest reading in weeks, low fear despite Iran/oil |
| Narrative Coherence | 4 | SPY +0.1%/5d | QQQ-SPY breadth +15 |
| Composite | 37 | NEUTRAL |
Regime thresholds: <30 RISK-ON | 30-44 NEUTRAL | 45-60 FÖRSIKTIGHET | ≥61 RISK-OFF
The scorecard registers NEUTRAL — VIX at 14.92, 10Y at 4.76%. Stress is moderate. A VIX spike or a 10Y jump would push toward FÖRSIKTIGHET.
No scorecard regime flip versus Monday (35 to 37). Flow pressure ticked up because the VIX rose. It is still low. Friday’s 29 (risk-on) is gone. Payrolls on 4 Sep can knock this back to risk-on or push it into caution.
1 Sep 2026, 04:50 CEST | Next review: 2 Sep 2026 (Wed)
Score Trend (30 days)
September 01, 2026 08:10 CEST (live scorecard update) | Next full review: Monday 07 Sep 2026