🌍 Market Regime — August 30, 2026
August 30, 2026 · Top 5 regime drivers, risk matrix, positioning
 Warsh left the door open for a September hike. Payrolls were revised down 79 thousand through March.
 Oil fell about 5 percent this week on Hormuz talk.
 China 119 billion stimulus is still slow to land.
Weekend edition — data through 28 Aug 2026 US close. Markets are closed Sunday.
📊 Markets Bar (28 Aug Close)
| Asset | Level | Daily Change |
|---|---|---|
| S&P 500 | 7,711.76 | -0.25% |
| VIX | 14.43 | -0.55% |
| US 10Y Yield | 4.72% | +4.8 bp |
| US 5Y Yield | 4.48% | +8.5 bp |
| Brent Crude | $89.31 | -0.43% |
| WTI Crude | $83.40 | -0.16% |
| Gold (GLD) | $408.89 | -3.24% |
| Dollar Index (DXY) | 99.70 | +0.54% |
S&P 500 still finished the week up 0.5%. VIX stayed low. The move was a recalibration, not a rout.
Top 5 Regime Drivers
1. Warsh Keeps a September Hike on the Table
Signal. Fed Chair Kevin Warsh told Jackson Hole that inflation has not improved enough, and that the Fed has "work to do" if prices are not moving clearly toward 2%. PCE inflation is 3.7% over the past year. Futures put a September hike near a coin flip, around 55 percent, up from about 35 percent before the speech (Reuters, CNBC, WSJ, 28 Aug).
Macro Impact. The 10-year yield ended Friday at 4.72%. The 5-year yield rose to 4.48%. The dollar firmed. Equities only slipped 0.25%. VIX at 14.43 says the tape still treats this as talk, not a committed tightening cycle. The July hold at 3.50 to 3.75 percent had three hikes as dissents, so the committee is already split.
Positioning. Overweight financials (XLF) on a higher curve. Underweight long duration (TLT) and rate-sensitive small caps (IWM). Long dollar vs yen remains the cleaner expression than shorting the S&P.
Key Sources. Reuters 28 Aug "Warsh signals Fed may need to hike"; CNBC 28 Aug "September Fed decision now a coin flip"; WSJ 28 Aug "Warsh Speaks and Rate-Hike Odds Rise".
2. Jobs Data Argue the Other Way
Signal. BLS said Friday that payrolls through March 2026 were overstated by 79,000. That is a small 0.1 percent benchmark revision, but it sits on top of July's 23,000 job loss and a 103,000 downward revision to May and June (NYT, Quartz, BLS, 28 Aug; jobs report 7 Aug). Unemployment is 4.1 percent, helped by people leaving the labor force.
Macro Impact. Soft labor vs sticky inflation is the live Fed dilemma. Warsh called the labor market consistent with full employment. The data look softer than that. August payrolls on 4 Sep (Fri) are the next real test of the hike call.
Positioning. Do not chase a full hawkish reprice before the 4 Sep payrolls print. Keep quality (SPHQ) over cyclicals that need a tight labor market. Fade 10-year spikes rather than short the whole curve.
Key Sources. NYT 28 Aug "Smaller Revision Points to More Accurate Jobs Numbers"; Quartz 28 Aug "BLS revises U.S. job growth down 79,000"; CNBC 7 Aug "U.S. economy unexpectedly lost 23,000 jobs in July".
3. Oil Risk Premium Faded This Week
Signal. Brent settled Friday at $89.31, down 0.43% on the day and about 5.4% on the week. WTI settled at $83.40, down 0.16% Friday and about 4.2% on the week. Hormuz talks and a firmer dollar both weighed. Flows through the strait remain choppy (EnergyNow, Reuters, RTE, 28 Aug).
Macro Impact. Cheaper oil helps the disinflation case and undercuts the energy equity bid. The geopolitical tail is still binary. Talks can fail. A re-tightening of Hormuz would reprice Brent fast.
Positioning. Stay underweight energy (XLE) while talks progress. Keep a small tail hedge rather than a large long. Defense (ITA) is not a crowded panic bid this weekend.
Key Sources. EnergyNow 28 Aug Friday settlement report; Reuters 28 Aug "Oil settles lower on clues about Fed policy, rumors of Hormuz deal"; RTE 28 Aug "Oil dips as Hormuz flows balance slow progress in talks".
4. China Stimulus Is Open, Not Flowing
Signal. Beijing opened applications for an 800 billion yuan (119 billion dollar) policy financing tool this week. Local projects must still clear review. Caitong said disbursement takes at least another month. Q2 GDP grew 4.3%. Fixed-asset investment fell 6.7% in the first seven months (Reuters, 24 Aug).
Macro Impact. The impulse is real but late. Commodity demand from China stays capped near term. Australia, Brazil, and copper names remain the cleanest underweights until money actually hits projects.
Positioning. Underweight FCX and VALE. KWEB is a policy-hope trade, not a growth trade. Watch AUD as the China proxy, not the CSI as a lead.
Key Sources. Reuters 24 Aug "China's $119 billion policy financing tool begins project applications, faces roll-out lag".
5. 🤖 AI Capex Holds. Chips Gave Back Friday.
Signal. Nvidia reported Q2 FY2027 results on 26 Aug. Revenue was 96.2 billion dollars, up 106% from a year ago. Data center revenue was 89.0 billion. Guidance for the current quarter is 108 billion dollars. Shares still fell 4.57% on Friday as the post-report bounce faded with Warsh (NVIDIA 26 Aug; Reuters 28 Aug). AMD fell 2.33% Friday.
Macro Impact. The capex cycle is intact. The tape can still de-rate the stocks when rates reprice. Power, cooling, and data centers remain the slower, less crowded way to stay long the build-out.
Positioning. Buy NVDA, AMD, AVGO on dips, not into strength. Overweight DLR, EQIX, XLU, NEE. Do not treat Friday's chip drop as a broken AI cycle.
Key Sources. NVIDIA Newsroom 26 Aug Q2 FY2027 results; Reuters 28 Aug "Wall Street ends lower" (chip pullback after Nvidia-driven Thursday).
Summary Risk Matrix
| Factor | Direction | Conviction | Horizon | Δ vs yesterday |
|---|---|---|---|---|
| US Rates | Higher for longer | Medium | 1-3 mo | ↗️ 10Y at 4.72%, fiscal score 62 |
| US Growth | Softening | High | 3-6 mo | → Friday revision confirmed |
| Inflation | Sticky (PCE 3.7%) | Medium | 6-12 mo | → Warsh unchanged |
| Geopolitics | De-escalating, binary | Low | 1-3 mo | ↘️ Oil down ~5% this week |
| China Growth | Weak, policy lag | Medium | 6-12 mo | → No new flow |
| AI Capex | Accelerating | High | 12+ mo | ↘️ NVDA -4.57% Friday |
Portfolio Construction
| Position | Weight | Rationale |
|---|---|---|
| Overweight | ||
| Financials (XLF) | +5% | Higher curve, hike talk supports net interest |
| Semis (SOXX, NVDA, AMD) | +3% | Structural capex. Friday was a rate fade, not a demand break |
| Data Centers (DLR, EQIX) | +3% | Multi-year power and rack demand |
| Utilities (XLU, NEE) | +2% | AI load plus defensive yield |
| Quality (SPHQ) | +3% | Soft growth, split Fed, keep balance sheets clean |
| Underweight | ||
| Long duration (TLT) | -4% | 10-year backing up. Fiscal score jumped to 62 |
| Small Caps (IWM) | -3% | Rate sensitive. Need a tight labor market they do not have |
| Energy (XLE) | -3% | Weekly oil drop as Hormuz premium faded |
| China cyclicals (FCX, VALE) | -3% | Stimulus still in the application queue |
| Gold (GLD) | -2% | Real yields up. GLD fell 3.2% Friday |
Key Events / Watchlist (Next 2 Weeks)
| Date | Event | Importance |
|---|---|---|
| 1 Sep (Tue) | ISM Manufacturing PMI, JOLTS (Jul) | High |
| 2 Sep (Wed) | ADP Payrolls (Aug), Beige Book | High |
| 3 Sep (Thu) | ISM Services PMI, Productivity and Costs | High |
| 4 Sep (Fri) | US Nonfarm Payrolls (Aug) | Critical |
| 7 Sep (Mon) | US Labor Day — markets closed | Low |
| 10 Sep (Thu) | ECB rate decision, US PPI (Aug) | High |
| 11 Sep (Fri) | US CPI (Aug) | Critical |
| 15 Sep (Tue) | FOMC meeting starts (SEP meeting) | High |
| 16 Sep (Wed) | FOMC decision and dot plot, US Retail Sales | Critical |
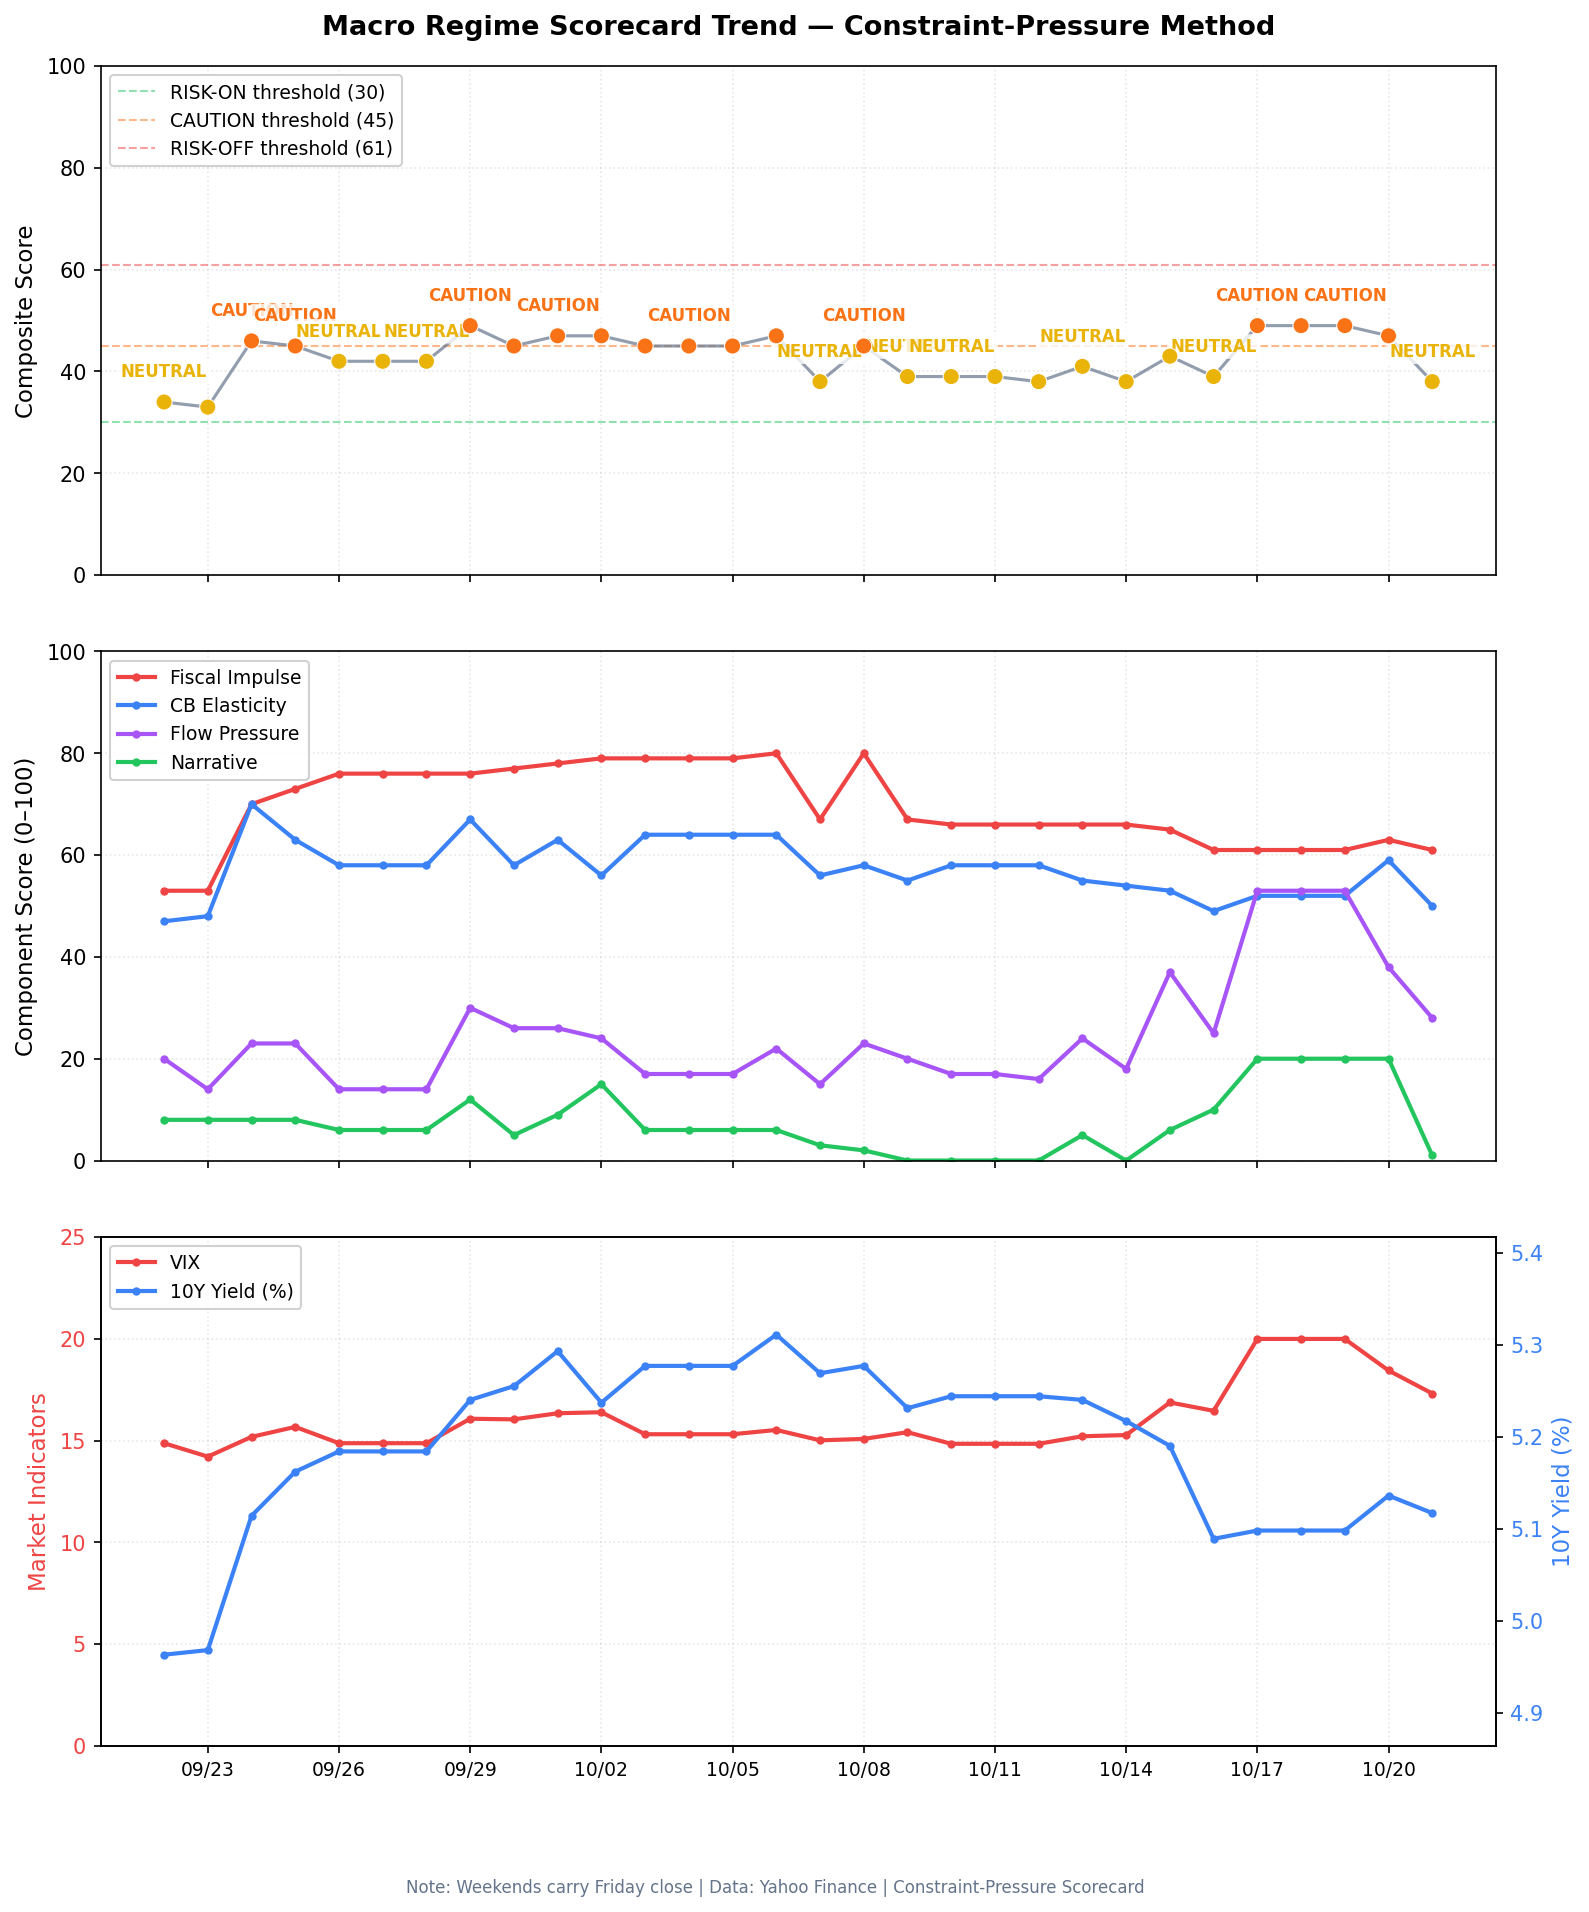
Regime Scorecard (Live — 28 Aug Close)
| Variable | Score | Interpretation |
|---|---|---|
| Fiscal Impulse | 62 | 10Y at 4.72% — moderately restrictive |
| CB Elasticity | 52 | 5Y at 4.45% — below neutral, Fed constrained by inflation above target |
| Flow Pressure | 20 | VIX 14.4 — lowest reading in weeks, low fear despite Iran/oil |
| Narrative Coherence | 3 | SPY +0.8%/5d | QQQ-SPY breadth +13 |
| Composite | 37 | NEUTRAL |
Regime thresholds: <30 RISK-ON | 30-44 NEUTRAL | 45-60 FÖRSIKTIGHET | ≥61 RISK-OFF
The scorecard registers NEUTRAL — VIX at 14.43, 10Y at 4.72%. Stress is moderate. A VIX spike or a 10Y jump would push toward FÖRSIKTIGHET.
No regime flip versus Saturday. Stress rose from 34 to 37 as the fiscal score jumped. Friday had been 29 (risk-on). The 4 Sep payrolls print can still knock this back or push it into caution.
30 Aug 2026, 04:45 CEST | Next review: 31 Aug 2026 (Mon)
Score Trend (30 days)
August 30, 2026 08:10 CEST (live scorecard update) | Next full review: Monday 31 Aug 2026