🌍 Market Regime — August 29, 2026
August 29, 2026 · Top 5 regime drivers, risk matrix, positioning
 Fed Chair Warsh warned inflation is too high at Jackson Hole. September rate hike odds jumped to near fifty-fifty. US payrolls revised down 79 thousand through March. July lost 23 thousand jobs. Labor market softening.
 US Navy blockade cuts Iran oil exports. Qatar-Iran talks on Hormuz reopening. Brent fell to 88 dollars.
 China 119 billion dollar stimulus starts project applications. IMF cuts growth to 4.4 percent. Rollout lag persists.
Weekend edition — data through 28 Aug 2026 US close (08:10 CEST live scorecard update)
📊 Markets Bar (28 Aug Close)
| Asset | Level | Daily Change |
|---|---|---|
| S&P 500 (SPY) | 769.35 | -0.2% |
| VIX | 14.43 | -0.6% |
| US 10Y Yield | 4.72% | +1.0 bp |
| US 5Y Yield | 4.48% | +1.9 bp |
| Brent Crude | $88.29 | -1.6% |
| WTI Crude | $83.44 | -0.1% |
| Gold (GLD) | $408.89 | -3.2% |
| Dollar Index (DXY) | 99.68 | +0.5% |
Top 5 Regime Drivers
1. Fed Hike Narrative Re-Emerges at Jackson Hole
Signal. Fed Chair Kevin Warsh said inflation remains concerning and the Fed may have work to do, sparking a repricing of September hike odds to near coin-flip (CNBC, Reuters, Politico, 28 Aug).
Macro Impact. Terminal rate expectations shift up. Two-year yields rose. Dollar strengthened. Equity risk premium compressed — but VIX stayed low at 14.4, suggesting markets see this as talk not action yet.
Positioning. Short 2Y futures. Long dollar vs yen. Underweight rate-sensitive growth. Overweight financials (XLF) on steeper curve.
Key Sources. CNBC 28 Aug "Warsh expresses concern about inflation", Reuters 28 Aug "Rate-hike expectations rise on Warsh speech", Politico 28 Aug "Warsh signals Fed may need to raise rates".
2. US Labor Market Shows Cracks — Payrolls Revised Down
Signal. BLS benchmark revision cut 79,000 jobs through March 2026. July payrolls fell 23,000, unemployment rate dipped (Reuters, Bloomberg, CNBC, 28 Aug).
Macro Impact. Softening labor data argues against hikes. The revision is backward-looking but the July print is fresh weakness. Fed now has conflicting signals: Warsh hawkish rhetoric vs softening jobs.
Positioning. Long duration (TLT) on any yield spike. Underweight small caps (IWM) — they need tight labor. Overweight quality defensives (SPHQ).
Key Sources. Reuters 28 Aug "US employment growth only modestly lower in BLS revision", Bloomberg 28 Aug "US Employers Unexpectedly Shed Jobs", CNBC 28 Aug "U.S. economy unexpectedly lost 23,000 jobs in July".
3. Iran Oil Exports Slashed — Hormuz Talks Underway
Signal. US Navy blockade cuts Iran exports. Qatar-Iran talks on Hormuz reopening progress. Brent slipped to $88, WTI to $83 (Reuters, CNBC, DW, 28 Aug).
Macro Impact. Supply risk premium fading. Oil down 1.6% on the day. Lower energy prices help disinflation narrative but hurt energy equities. Geopolitical tail risk remains — talks can collapse.
Positioning. Underweight XLE, ITA. Long puts on Brent $85 strike for tail hedge. Overweight renewables (ICLN) as energy transition narrative strengthens with lower oil.
Key Sources. Reuters 28 Aug "Oil settles lower on clues about Fed policy, rumors of Hormuz deal", CNBC 28 Aug "Oil prices fall as U.S. rolls out global sanctions focused on Iran", DW 28 Aug "Gulf states scramble for Strait of Hormuz alternatives".
4. China Stimulus Rolls Out — But With Lag
Signal. $119B policy financing tool begins project applications. IMF cuts 2026 growth to 4.4%. Consumption and output losing steam (Reuters, IMF, 28 Aug).
Macro Impact. Stimulus is real but slow. Property sector still drags. Commodity demand support limited near-term. Australia, Brazil, Chile exposed.
Positioning. Underweight copper (FCX), iron ore (VALE). Long China internet (KWEB) on policy hope. Watch AUD/JPY for China proxy.
Key Sources. Reuters 28 Aug "China's $119 billion policy financing tool begins project applications", IMF 28 Aug "IMF cuts China 2026 economic growth forecast to 4.4%", Reuters 28 Aug "China's recovery sputters as consumption, output lose steam".
5. 🤖 AI Capex Boom Intact — Hyperscaler Build-Out Accelerates
Signal. Hyperscalers spending 102% of cloud revenue on capex. Nvidia Blackwell ramp, Rubin GPU orders at $8B scale (Yahoo Finance, Data Center Knowledge, Business Standard, 28 Aug). Nvidia reported Q2 FY2027 earnings Aug 26 — revenue $96.2B, up 106% YoY.
Macro Impact. Structural demand for compute, power, cooling. Supports semis, data centers, power infrastructure. Hyperscaler capex cycle multi-year.
Positioning. Overweight NVDA, AMD, AVGO on dips. Long DLR, EQIX for data center exposure. Long XLU, NEE for power demand.
Key Sources. Yahoo Finance 28 Aug "AI's Absurd Spending Boom? Hyperscalers Are Spending 102% of Cloud Revenue on Capex", Data Center Knowledge 28 Aug "AI Infrastructure Pushes Data Center Capex Forecast Above $3 Trillion", Business Standard 28 Aug "AMI orders 9,000 NVIDIA Rubin GPUs, plans $8 bn capex".
Summary Risk Matrix
| Factor | Direction | Conviction | Horizon | Δ vs Yesterday |
|---|---|---|---|---|
| US Rates | Higher for longer | Medium | 1-3 mo | ↗️ Warsh hawkish shift |
| US Growth | Softening | High | 3-6 mo | ↗️ Payrolls revision |
| Inflation | Sticky services | Medium | 6-12 mo | → CPI 3.4% |
| Geopolitics | De-escalating | Low | 1-3 mo | ↘️ Hormuz talks |
| China Growth | Stabilizing slow | Medium | 6-12 mo | → Stimulus lag |
| AI Capex | Accelerating | High | 12+ mo | → 102% cloud rev |
Portfolio Construction
| Position | Weight | Rationale |
|---|---|---|
| Overweight | ||
| Financials (XLF) | +5% | Steeper curve, higher rates help NIM |
| Semis (SOXX) | +3% | AI capex structural, hyperscaler build-out |
| Data Centers (DLR, EQIX) | +3% | 102% cloud rev to capex, power demand |
| Utilities (XLU) | +2% | AI power demand, defensive yield |
| Quality Factor (SPHQ) | +3% | Strong balance sheets for uncertain growth |
| Underweight | ||
| Energy (XLE, ITA) | -4% | Oil supply risk fading, Hormuz talks |
| Small Caps (IWM) | -3% | Need tight labor, rate sensitive |
| China Cyclicals (FCX, VALE) | -3% | Stimulus lag, property drag |
| Rate-Sensitive Growth | -3% | Hike risk repricing |
| Gold (GLD) | -2% | Real yields rising, dollar strong |
Key Events / Watchlist (Next 2 Weeks)
| Date | Event | Importance |
|---|---|---|
| 1 Sep (Tue) | US Labor Day — markets closed | Low |
| 2 Sep (Wed) | ISM Manufacturing PMI | High |
| 3 Sep (Thu) | JOLTS Job Openings | High |
| 4 Sep (Fri) | ISM Services PMI, ADP Payrolls | High |
| 5 Sep (Sat) | US Nonfarm Payrolls (Aug) | Critical |
| 8 Sep (Tue) | China CPI/PPI | Medium |
| 9 Sep (Wed) | — | — |
| 10 Sep (Thu) | US CPI (Jul) | Critical |
| 11 Sep (Fri) | ECB Rate Decision | High |
| 12 Sep (Sat) | UMich Consumer Sentiment | Medium |
| 15 Sep (Tue) | FOMC Blackout Begins | Medium |
| 16 Sep (Wed) | US Retail Sales | High |
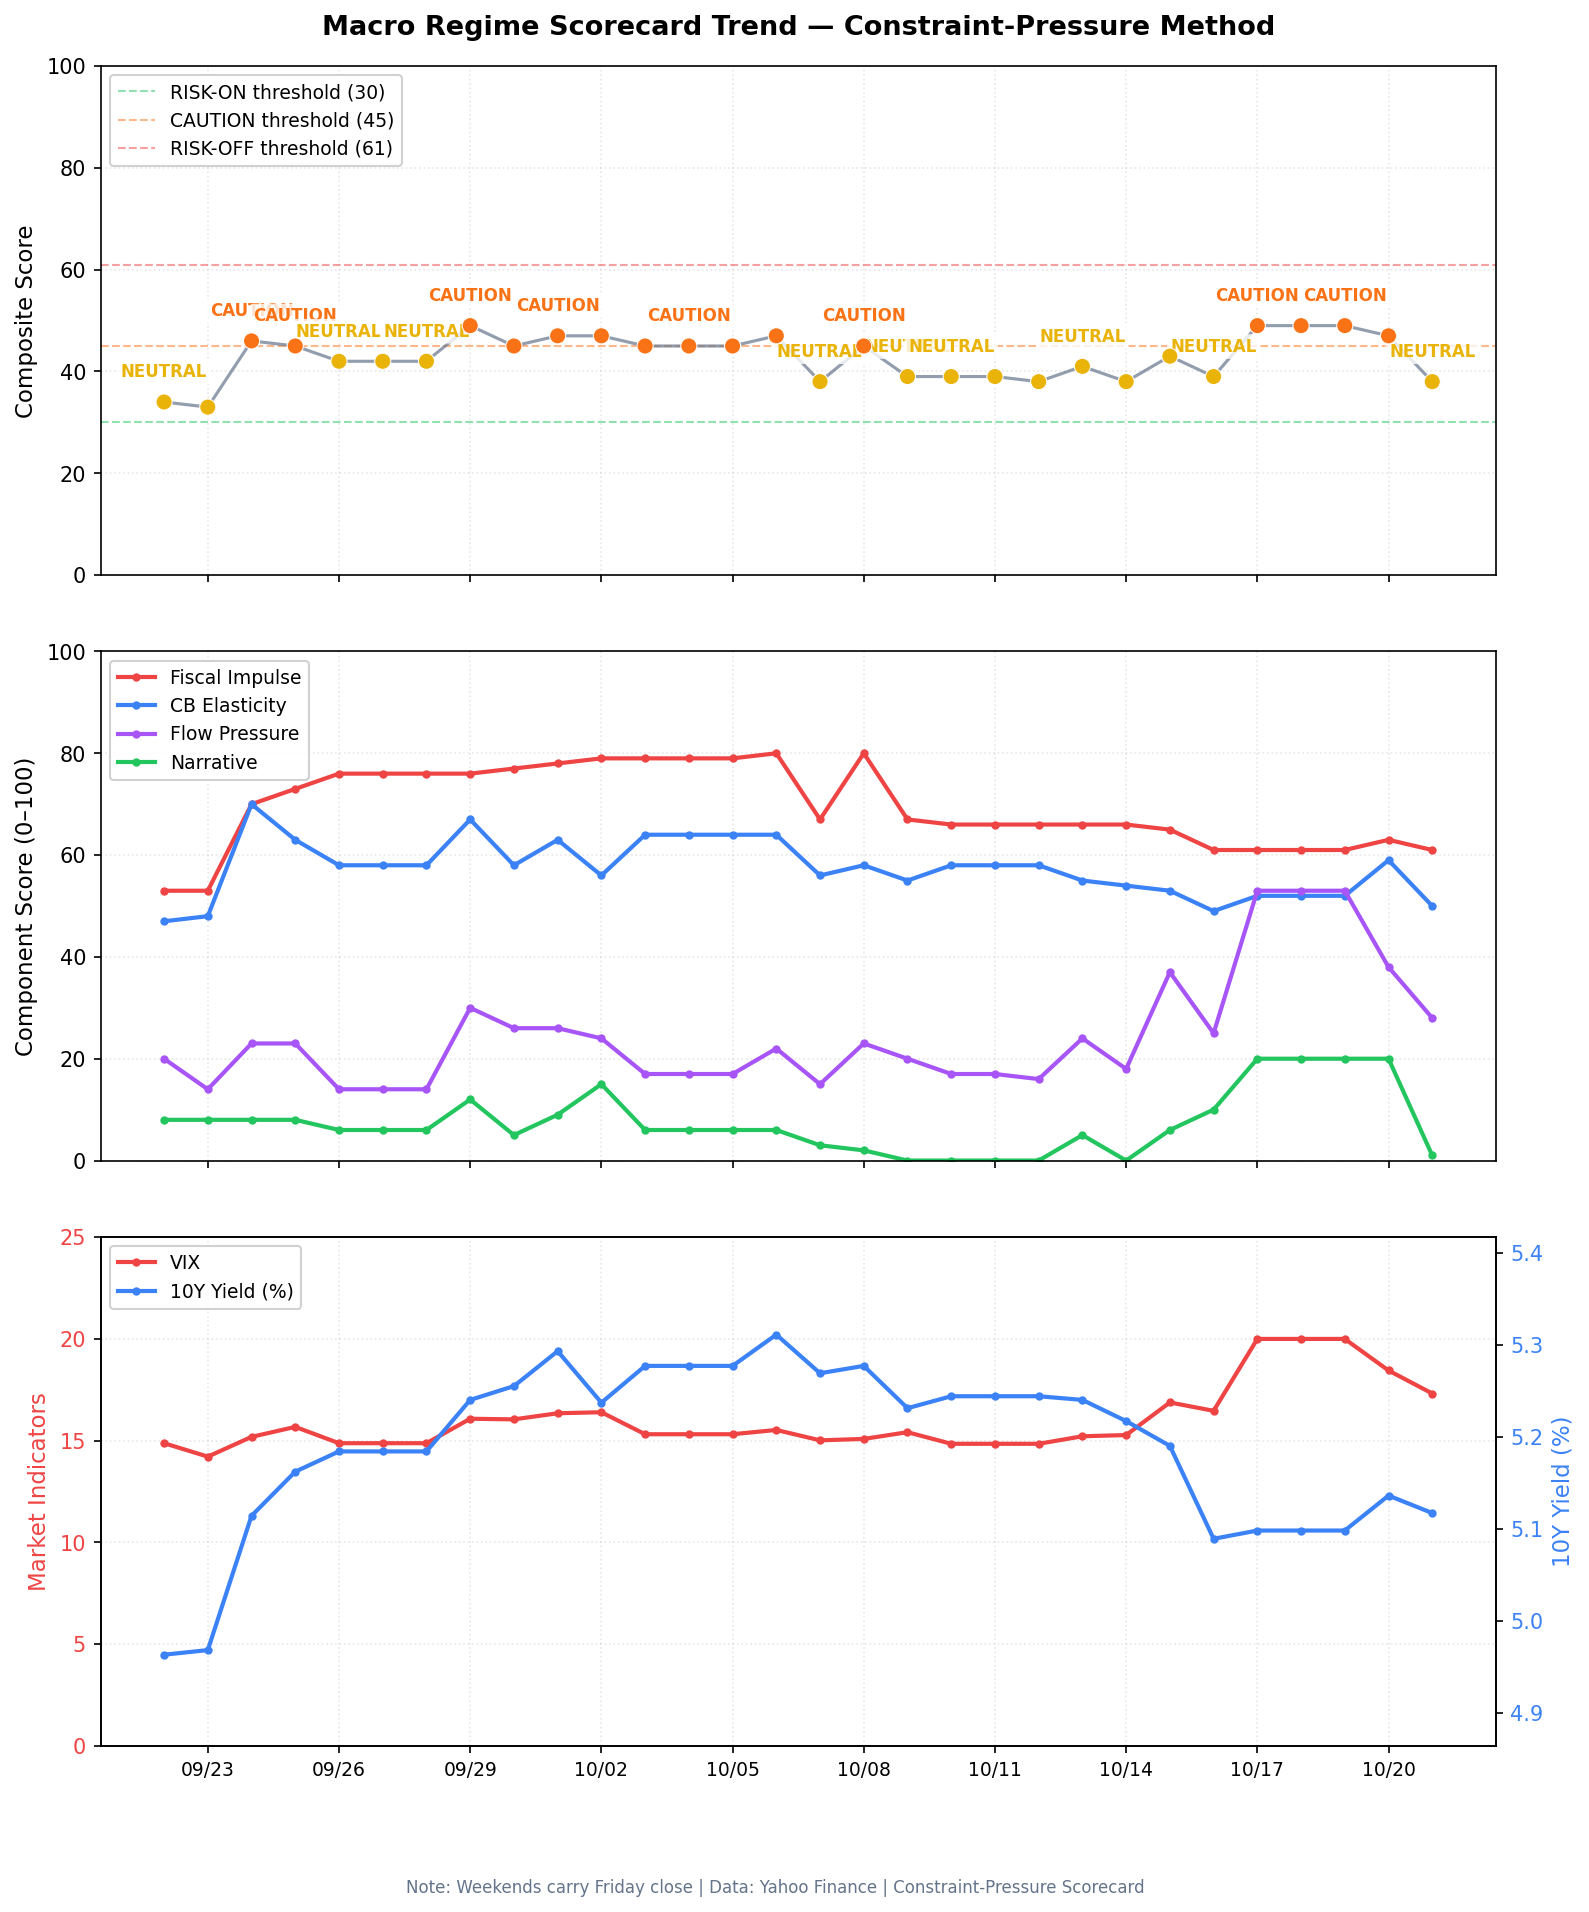
Regime Scorecard (Live — 28 Aug Close)
| Variable | Score | Interpretation |
|---|---|---|
| Fiscal Impulse | 50 | 10Y at 4.72% — moderately restrictive |
| CB Elasticity | 54 | 5Y at 4.45% — below neutral, Fed constrained by inflation above target |
| Flow Pressure | 20 | VIX 14.4 — lowest reading in weeks, low fear despite Iran/oil |
| Narrative Coherence | 5 | SPY +1.0%/5d | QQQ-SPY breadth +21 |
| Composite | 34 | NEUTRAL |
Regime thresholds: <30 RISK-ON | 30-44 NEUTRAL | 45-60 FÖRSIKTIGHET | ≥61 RISK-OFF
The scorecard registers NEUTRAL — VIX at 14.43, 10Y at 4.72%. Stress is moderate. A VIX spike or a 10Y jump would push toward FÖRSIKTIGHET.
Score Trend (30 days)
August 29, 2026 08:10 CEST (live scorecard update) | Next full review: Monday 31 Aug 2026