OverWise

Market regime, November 18

Top five drivers, the risk matrix and the book for Wednesday, November 18, 2026.

The label held. The score is 59 of 100, up from 54 in yesterday's note. CAUTION runs from 45 to 60. NEUTRAL runs from 30 to 44. RISK-ON is below 30. RISK-OFF starts at 61. A higher score means more stress. Five points inside the same band is not a flip. It leaves the book two points from the line.

Read the five drivers
Before the US open Next review 19 Nov 2026 (Thu)

Regime score

59of 100

CAUTION

2 under RISK-OFF, 14 over the NEUTRAL line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Tuesday was another down cash close, the fourth in a row. The volatility index closed at 25.46, up 2.55 points from Monday's 22.91. That is why the score rose. Yields eased again. Oil settled higher, on strikes, and a Wednesday morning screen is already lower. Neither one is a new policy decision, and the morning screen is not a new settlement.

The chip company reported after the US cash close. The cash close is still the book. An after hours print is not a third settlement, and it is not Wednesday's open.

The 10 year index the score uses closed at 5.103 percent on Tuesday, down 1.8 basis points from Monday's 5.121. A cash yield in a Wednesday markets wrap, 5.123 percent, is a different series. Do not blend them.

In short

MARKET REGIME, Nov 18 (Wed)

Signal. Caution. Do not add oil or the open. Score 59 of 100.

  1. United States Stocks closed lower. Volatility closed at 25.46.
  2. United States The chip result is out. The cash close is not.
  3. Iran Brent settled higher Tuesday, at 93.14 dollars.
  4. United States The 10 year index eased to 5.103 percent.
  5. United States A December rate hike is still the base.

Markets bar

Equity, fund, and volatility rows are Tuesday's cash close, against Monday. Yield index rows are Tuesday's close on this feed. Brent and WTI rows are Tuesday's exchange settlement, from the settlement story, against Monday's settlement. The continuous contract on this feed did not print that settlement. The dollar index row is this series' Tuesday close. A Reuters index was higher on Wednesday morning. That screen is not in the table. The gold row is the fund.

Wednesday morning oil screens are not settlements. At 01:49 GMT Reuters had Brent down 16 cents, or 0.17 percent, to 92.98 dollars, and WTI down 56 cents, or 0.65 percent, to 85.45 dollars. An earlier Asia note had Brent 0.2 percent lower, at 93.00 dollars. Use Tuesday's settlement until the exchange prints a new one.

The same split shows up in the dollar and in gold. Reuters on Wednesday had its dollar index up 0.05 percent to 103.66, after an overnight peak of 103.78, the highest since 2 April 2025. This series closed Tuesday at 103.61. A markets column had gold around a one year low near 3,950 dollars. A later headline had the metal more than 1 percent lower on Wednesday. Those are screens. The gold line in the table is the fund.

A markets wrap had the cash 10 year yield up 2.2 basis points to 5.123 percent on Wednesday morning. That is not the index in the table.

Asia was higher into the morning, after four down days. Reuters had the regional index outside Japan up 0.9 percent, Korea up as much as 3.3 percent, the Nikkei up 0.6 percent, and S&P 500 futures up 0.5 percent. Those are screens.

Asset Level Change
S&P 500 (Tue close)7,340.53Down 76.06 points, or 1.03 percent, vs Monday's 7,416.59. Down 0.49 percent from the 6 Nov close on this feed. Lowest close on this series since 29 July, when it closed at 7,316.15
Nasdaq Composite (Tue close)24,328.38Down 181.38 points, or 0.74 percent, vs Monday's 24,509.76
Dow (Tue close)50,759.42Down 848.75 points, or 1.64 percent, vs Monday's 51,608.17
VIX (Tue close)25.46Up 2.55 points, or 11.13 percent, vs Monday's 22.91. Still below the 6 Nov close of 25.64 on this feed. The score uses Tuesday's close
US 10 year yield index (Tue close)5.103 percentDown 1.8 basis points vs Monday's 5.121. The score uses this close
5 year yield index (Tue close)4.900 percentDown 3.5 basis points vs Monday's 4.935
30 year yield index (Tue close)5.458 percentDown 0.9 basis points vs Monday's 5.467
3 month yield index (Tue close)4.138 percentUp 1.3 basis points vs Monday's 4.125
Brent settlement (Tue)93.14 dollarsUp 70 cents, or 0.76 percent, from Monday's 92.44
WTI settlement (Tue)86.01 dollarsUp 29 cents, or 0.34 percent, from Monday's 85.72
Dollar index (Tue close)103.61Up from Monday's 103.55 on this series. The rise was less than a tenth of a percent
Gold fund (Tue close)352.48Down 0.13 percent vs Monday's 352.93. Down 4.57 percent over the five sessions ended Tuesday on this feed
Energy fund (Tue close)63.36Down 0.52 percent vs Monday's 63.69. Up 2.82 percent from the 6 Nov close on this feed
Oil fund (Tue close)140.24Up 0.15 percent vs Monday's 140.03
Semiconductor fund (Tue close)460.10Down 0.39 percent vs Monday's 461.90. Down 4.87 percent over the five sessions ended Tuesday on this feed
Semiconductor index (Tue close)9,642.88Up 0.34 percent vs Monday's 9,610.65. Not the same series as the fund
Nvidia (Tue close)155.46Down 0.44 percent vs Monday's 156.14. Down 16.7 percent from the 6 Nov close on this feed. CNBC rounded Tuesday's decline at 0.5 percent
Broadcom (Tue close)341.60Up 2.46 percent vs Monday's 333.40
Long bond fund (Tue close)79.55Up 17 cents, or 0.21 percent, vs Monday's 79.38
High yield fund (Tue close)76.63Down 0.13 percent vs Monday's 76.73
Investment grade fund (Tue close)102.74Down 6 cents vs Monday's 102.80
Large cap China fund (Tue close)32.88Down 1.32 percent vs Monday's 33.32
Emerging markets fund (Tue close)58.27Down 1.05 percent vs Monday's 58.89
S&P 500 fund (Tue close)732.44Down 1.01 percent vs Monday's 739.95
Nasdaq 100 fund (Tue close)656.95Down 0.73 percent vs Monday's 661.75

Top five drivers

United States The label held

Tuesday was the second down close of the week.

SignalThere is a new US cash close, and it was lower again. The S&P 500 closed at 7,340.53, down 76.06 points, or 1.03 percent, from Monday's 7,416.59. That is the fourth straight lower close. On this series it is the lowest close since 29 July, when the index closed at 7,316.15. CNBC called it the lowest close since late July. The Nasdaq composite closed at 24,328.38, down 0.74 percent. The Dow closed at 50,759.42, down 848.75 points, or 1.64 percent. A Reuters markets note said all 11 S&P sectors closed lower, and that Europe and the UK each closed down 1.8 percent, their worst day since March.

The volatility index closed at 25.46, up 2.55 points, or 11.13 percent, from Monday's 22.91. CNBC had an intraday high of 27.73, which it called the highest since 6 Nov. That high is not the close. On this feed the close is still below the 6 Nov close of 25.64. The score uses Tuesday's close. Flow is 72, from 67 yesterday. That is the composite move.

The score this morning is 59. Yesterday's note had 54. Fiscal is 74, unchanged. The central bank score is 48, from 50, because the 5 year index eased. Narrative is 32, from 15. The label stayed CAUTION. A futures bounce in Asia does not repair the cash close. From the 6 Nov close, the S&P 500 is down 0.49 percent on this feed. At Monday's close that same comparison was still up.

High yield closed at 76.63, down 0.13 percent. Investment grade was down 6 cents, at 102.74. Credit did not confirm a stress day. Volatility did.

The afternoon had an extra headline. CNN reported that a classified network used by the National Security Agency had gone down, and its sources said there was no evidence of a cyberattack. The agency later said the degradation was temporary, during scheduled maintenance, and that mission critical capabilities remained operational. CNBC said the averages reached their lows of the day after that report. It is part of the tape. It is not a new close, and it does not explain the three down sessions before Tuesday.

Macro ImpactAdding equity because the score is still inside CAUTION, or because futures bounced in Asia, treats a five point rise toward the RISK-OFF line as a calm day. The next cash close is the one that can cross 61. Covering the long bond because yields eased again buys duration into a 10 year index that is still at 5.103 percent.

PositioningDo not add broad equity. The down day is the book until today's cash close. Cash and short bills still pay more than the long end through December.

Key SourcesCNBC, 17 Nov, https://www.cnbc.com/2026/11/16/stock-market-today-live-updates.html ; Reuters markets note, 17 Nov, https://www.reuters.com/commentary/reuters-open-interest/global-markets-trading-day-graphic-2026-11-17/ ; Reuters, 18 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-18/ ; Tuesday closes on this series.
United States The result is out

The cash close is not a new one.

SignalNvidia closed at 155.46, down 0.44 percent from Monday's 156.14, and down 16.7 percent from the 6 Nov close on this feed. CNBC rounded Tuesday's decline at 0.5 percent. The semiconductor fund closed at 460.10, down 0.39 percent. The semiconductor index on this feed closed at 9,642.88, up 0.34 percent. Those two series did not move together. Broadcom closed at 341.60, up 2.46 percent. The fund is the sleeve. The single name is not.

The company reported after the cash close. Its own release put third quarter revenue at 115.8 billion dollars, up 20 percent from the prior quarter and up 103 percent from a year earlier. Data center revenue was 107.6 billion dollars, up 110 percent from a year earlier. The fourth quarter outlook is 130.0 billion dollars, plus or minus 3 percent, and it assumes no data center compute revenue from China. CNBC, citing LSEG, had the revenue figure at 115.84 billion dollars against a 109.10 billion dollar forecast, and adjusted earnings of 2.68 dollars a share against a 2.48 dollar forecast. The same account said the company lifted its growth outlook for the year ending January 2028 to 75 percent, from 70 percent. The quarter and the outlook are the company's. The comparison with the forecast is CNBC's.

The after hours prints do not agree, and none of them is a close. Reuters had the shares 4.7 percent higher after the cash close. CNBC had a gain of more than 3 percent, and later nearly 4 percent. Use the cash close of 155.46 until Wednesday's session prints a new one.

The governance story is still unresolved. On the call, the board chair said the board does not intend to bring the former chief back, CNBC reported. Earlier on Tuesday he said he would be honored to return, Reuters reported. Reuters also said the Wall Street Journal reported that the securities regulator is probing the company. That is a report, not a filing this note has read. Monday's export rule is still the policy fact. The outlook already assumes no China data center compute revenue.

A listing is still on the week. Reuters said the company prices later today and debuts on Thursday, and that it has guided the price to the top of the range or above. The same note said the debut could value the company at as much as 1.4 trillion dollars. That figure is not a price until it prints.

Macro ImpactBuying the shares because the result was above the forecast treats an after hours screen, a governance story, and a license rule as a finished cash close. Shorting the semiconductor fund because it closed 0.39 percent lower sells a fund into a result the company has already published. Adding broad equity because S&P futures were up 0.5 percent in Asia does the same thing with a screen.

PositioningNo new chip position. Do not buy the open on the after hours print. Do not short the semiconductor fund into a result that was above the forecast. Do not trade the listing date as a completed price.

Key SourcesCompany release, 17 Nov, https://investor.nvidia.com/news/press-release-details/2026/NVIDIA-Announces-Financial-Results-for-Third-Quarter-Fiscal-2027/default.aspx ; CNBC, 17 Nov, https://www.cnbc.com/2026/11/17/nvidia-nvda-earnings-report-q3-2027.html ; Reuters, 18 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-18/ ; Tuesday closes on this series.

Iran Tuesday's settlement rose

The morning screen is not a new one.

SignalMonday's settlement is no longer the book. Reuters said Brent crude futures settled 70 cents, or 0.76 percent, higher at 93.14 dollars. WTI gained 29 cents, or 0.34 percent, to 86.01 dollars. Monday's settlements were 92.44 and 85.72. The arithmetic matches.

The reason in the settlement story is the strikes, not a new surplus print. Iranian drones attacked a US military radar system in Bahrain on Tuesday, and the US struck a missile launch site on Qeshm Island. A ship in the Strait of Hormuz was hit twice, and the crew was unaccounted for. The president said the US is taking seriously the possibility that Iran could be planning an attack with a so called dirty bomb in Washington. That is his statement. It is not a verified plot. Yemen's Houthis said they launched five drones toward two pumping stations on the Saudi East West pipeline. That is their claim.

The surplus is still the other side of the same story. Friday's International Energy Agency call, a fourth quarter surplus as Gulf exports recover, was already in the tape. Reuters said Brent is down 20 percent this month and WTI is down 16 percent. A broker in the settlement story called the market a range, with supply on one side and disruption on the other. One house view is not a quota.

Wednesday's screen is the new conflict, and it is not a settlement. At 01:49 GMT Reuters had the Brent screen 16 cents under the settlement, at 92.98 dollars, and the WTI screen 56 cents under, at 85.45 dollars, on an industry stock report. Market sources, citing the American Petroleum Institute, said crude stocks rose 5.28 million barrels in the week ended 13 Nov, gasoline rose 5.12 million barrels, and distillate rose 351,000 barrels. Tuesday's settlement story had expected a crude drop, from a Reuters poll. The official inventory print is later today. An industry report is not that print. Bahrain's defence force said on Wednesday that it had intercepted Iranian aerial attacks. That escalation is in the Wednesday story. It has not produced a new settlement.

The oil fund closed at 140.24, up 0.15 percent. The energy equity fund fell 0.52 percent, to 63.36, and is still up 2.82 percent from the 6 Nov close on this feed. The fund and the barrel are not the same position.

Macro ImpactAdding the residual because the settlement rose 70 cents, or because the strikes intensified, rebuilds a sleeve the same story says is capped by a surplus and by a month in which Reuters has Brent down 20 percent. Selling the last of it because a Wednesday screen is 16 cents under the settlement sells a position on a print that is not a settlement, before today's official inventory number.

PositioningKeep the smaller residual. Do not add it. Tuesday's settlement is the book. The morning screen is not a reason to sell the last of the sleeve, and it is not a reason to put the position back on.

Key SourcesReuters settlement, 17 Nov, https://www.reuters.com/business/energy/oil-slips-supply-surplus-outlook-despite-gulf-tensions-2026-11-17/ ; Reuters, 18 Nov, https://www.reuters.com/business/energy/oil-prices-fall-higher-us-crude-stocks-temper-supply-risks-2026-11-18/ ; Tuesday closes on this series.

United States Yields eased

The hike is still the expected move.

SignalThe 10 year index the score uses closed at 5.103 percent, down 1.8 basis points from Monday's 5.121. The 5 year index closed at 4.900 percent, down 3.5 basis points. The 30 year index closed at 5.458 percent, down 0.9 basis points. The 3 month index rose 1.3 basis points, to 4.138 percent. The long bond fund closed at 79.55, up 17 cents. The yield dip did produce a small fund gain. It did not change the level.

A markets wrap had the cash 10 year up 2.2 basis points to 5.123 percent on Wednesday morning. That is a later screen, on a different series. The score uses Tuesday's index.

The central bank score fell from 50 to 48 because the 5 year index eased. That is a yield dip inside the model. It is not a decision, and it is not an easier policy path.

October retail sales rose 0.2 percent, in line with the forecast, after an unrevised 0.8 percent gain in September, the Census Bureau report as carried by Reuters. The core measure that tracks goods spending in GDP rose 0.6 percent, against a 0.4 percent forecast, and September was revised up to 0.5 percent from 0.1 percent. Import prices rose 1.1 percent in October, against a 0.7 percent forecast. Reuters, citing the futures tool, said markets have priced a quarter point hike in December and have anticipated another increase in January. The current target range is 3.75 to 4 percent. The October meeting left it there.

New York Fed president John Williams said on Tuesday that the central bank will likely need to raise rates again to lean against inflation, and that there is not a need for dramatic action. He said the economy remains resilient, the jobs market is solid, and inflation is not moving in the right direction. St. Louis Fed president Alberto Musalem, who is not a voter this year, said the economy will likely require several rate increases before the spring of 2027, and that the current rate is as much as a full percentage point below where it needs to be. Inflation, he said, is running above 3 percent. Those are two officials. They are not a vote.

Minutes of the 27 Oct and 28 Oct meeting are the open item. The Fed's own rule is three weeks after the policy decision. The decision date was 28 Oct, which puts the release on 18 Nov (Wed). The calendar page has not yet attached the file. A dollar note on Wednesday said the minutes come on Thursday. This note does not pick the clock, and it does not have a text. The next meeting on the official calendar is 8 Dec (Tue) and 9 Dec (Wed), with projections.

Macro ImpactCovering the long bond because the index eased 1.8 basis points, or because the fund gained 17 cents, buys a small rally into a hike the futures tool still treats as the December move. Adding equity because yields eased treats a small bond bid as a repair of a fourth straight lower close.

PositioningStay underweight long duration. Do not cover. Do not add to the short because of one dip. Cash and short bills still pay more than the long end through 8 Dec (Tue) and 9 Dec (Wed).

Key SourcesReuters, 17 Nov, https://www.reuters.com/world/us/us-retail-sales-increase-moderately-october-2026-11-17/ ; Reuters, 17 Nov, https://www.reuters.com/business/feds-williams-still-favors-tighter-monetary-policy-says-now-is-not-time-dramatic-2026-11-17/ ; Reuters, 17 Nov, https://www.reuters.com/business/feds-musalem-us-likely-needs-several-rate-hikes-by-spring-control-inflation-2026-11-17/ ; Reuters, 18 Nov, https://www.reuters.com/world/middle-east/dollar-holds-near-19-month-high-data-supports-case-us-rate-hikes-2026-11-18/ ; Federal Reserve calendar, read 18 Nov, https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm ; Tuesday closes on this series.

United States The dollar is the firm leg

Gold is not the substitute.

SignalReuters on Wednesday had its dollar index at 103.66, up 0.05 percent, after an overnight peak of 103.78, the highest since 2 April 2025. The euro was at 1.0984. The yen was at 159.46. This series closed Tuesday at 103.61, from Monday's 103.55. The Wednesday screen and the Tuesday close are different prints. The score does not use the Wednesday screen.

The gold fund closed at 352.48, down 0.13 percent on the day and down 4.57 percent over the five sessions ended Tuesday. A markets column had spot gold around a one year low near 3,950 dollars. A Wednesday headline had the metal more than 1 percent lower. The fund did not rally with the equity decline. It was not the hedge.

The emerging markets fund fell 1.05 percent, to 58.27. The large cap China fund fell 1.32 percent, to 32.88. CNBC reported that Xi called for removing trade and investment barriers ahead of a meeting with Trump and Putin. Yesterday's note had that meeting on 19 Nov (Thu) in Shenzhen. Today's wires still have it ahead. A speech is not a deal, and it is not a waiver of Monday's chip rule.

Japan is the side note, not a new regime. Exports rose 20.5 percent in October from a year earlier, the 14th straight monthly gain, against a 20 percent forecast. The yen still softened. The Bank of Japan governor said the central bank should keep raising rates. That is a domestic line. It did not weaken the dollar.

Macro ImpactSwapping the crude residual for the gold fund buys a metal that has not worked as a hedge, with a hike still the expected December move. Selling the dollar because this series only inched up on Tuesday sells the leg that Reuters has at a 19 month high on a different index. Buying the China fund because leaders are due in the same city treats a confirmed meeting as a completed policy change.

PositioningNo new gold entry. Do not replace the oil residual with the gold fund. Do not fade the dollar on this series' small Tuesday rise. Stay underweight China cyclicals. Do not buy the fund into the meeting.

Key SourcesReuters, 18 Nov, https://www.reuters.com/world/middle-east/dollar-holds-near-19-month-high-data-supports-case-us-rate-hikes-2026-11-18/ ; Reuters, 18 Nov, https://www.reuters.com/world/china/global-markets-wrapup-1-2026-11-18/ ; Reuters, 18 Nov, https://www.reuters.com/markets/asia/japan-exports-set-record-october-strong-chip-related-demand-2026-11-18/ ; Tuesday closes on this series.

Risk matrix

The method note is above, in the markets bar. Cells below are Tuesday's close or Tuesday's settlement, unless the cell says otherwise.

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreCAUTIONHighDays59, from 54. The label held. Two points from 61. Not a flip
US equitiesLower on TuesdayHighDaysS&P 500 down 1.03 percent to 7,340.53. Fourth straight lower close
VolatilityHigher on TuesdayHighDays25.46, from 22.91. Flow score 72, from 67
Brent settlementHigher on TuesdayHighDays93.14 dollars, from 92.44. Up 0.76 percent
WTI settlementHigher on TuesdayHighDays86.01 dollars, from 85.72. Up 0.34 percent
StraitStrikes intensifiedMediumDaysSettlement rose. Wednesday screen is lower. Fire and drone claims are in the wire
US 10 yearSlightly lower, still through 5 percentHighDaysIndex 5.103 percent, from 5.121
Fed pathQuarter point is the expected December moveHighWeeksWilliams against a dramatic shift. Musalem wants several hikes by spring 2027. Next meeting 8 Dec (Tue) and 9 Dec (Wed)
ChipsCash close slightly lowerHighDaysCash close 155.46, off 0.44 percent. The result is out. After hours is not a close
DollarFirmerHighDaysThis series 103.61. Reuters index 103.66, overnight peak 103.78
GoldSlightly lower on TuesdayHighDaysFund 352.48, down 0.13 percent. Down 4.57 percent over five sessions
China fundLower on TuesdayMediumWeeksFund 32.88, down 1.32 percent. Meeting still ahead
Emerging markets fundLower on TuesdayHighDaysFund 58.27, down 1.05 percent
High yieldSlightly lowerMediumDays76.73 to 76.63. Not a credit stress day
Long bond fundSlightly higherHighDays79.55, from 79.38. A 17 cent gain is not a cover

Portfolio

Sleeve Stance Rationale
CrudeKeep the smaller residual. Do not addTuesday's Brent settlement was 93.14 dollars, up 70 cents. The Wednesday screen is not a new settlement
Energy equities (XLE)Do not addThe fund fell 0.52 percent, to 63.36, and is still up 2.82 percent from the 6 Nov close. That is not an open strait
Oil fund (USO)Hold with the smaller sleeveUp 0.15 percent, to 140.24. The fund is not the settlement
Long duration (TLT)Underweight. Do not coverThe fund gained 17 cents, to 79.55. The 10 year index closed at 5.103 percent
Cash and short billsOverweight versus the long endPaid to wait for 8 Dec (Tue) and 9 Dec (Wed). The label is CAUTION
Semiconductors (SMH)No new position. Do not buy the open. Do not short the fundThe fund fell 0.39 percent. The result is out. The after hours print is not a close
Gold (GLD)No new entryThe fund fell 0.13 percent, to 352.48, and 4.57 percent over five sessions. It does not replace the oil residual
Airlines and transportsNoThe settlement rose on strikes. The route is not clean, and the inventory print is still ahead
China cyclicalsUnderweightThe fund fell 1.32 percent, to 32.88. The meeting is still ahead, not a policy print
Broad equityDo not addThe S&P 500 fell 1.03 percent. A futures bounce is not a close

The next two weeks

Date Event Why it matters
18 Nov (Wed)Minutes of the 27 Oct and 28 Oct meetingThree weeks after the 28 Oct decision, which is the Fed's own rule. The calendar page has not yet attached the file. One dollar note said Thursday
18 Nov (Wed)Official weekly oil inventoriesReuters. The industry report is already in the tape. It is not this print
18 Nov (Wed)October housing startsReuters has the release today. This note does not have a number
18 Nov (Wed)Listing price, as reportedReuters. Later today. Not a finished price
18 Nov (Wed)UK October inflationListed for today in a Reuters markets note. This note does not have a number
19 Nov (Thu)First trade of that listing, as reportedReuters still has Thursday. Not a cash close until it prints
19 Nov (Thu)Leaders' meeting still aheadYesterday's note had Thursday in Shenzhen. Today's wires still have the meeting ahead. A speech is not a deal
25 Nov (Wed)Last full US equity session before the holidayThe cash market is scheduled to be open
26 Nov (Thu)Thanksgiving. The equity market is scheduled to be closedNo cash close that day
29 Nov (Sun)Wider producer group on 2027 outputReuters, carried in yesterday's note. A Sunday meeting, not a cash session. Not a quota until it prints
8 Dec (Tue) and 9 Dec (Wed)Policy meeting, with projectionsOutside this two week list. Official calendar. A quarter point is the expected move going in

The January meeting on the official 2027 calendar is 26 Jan (Tue) and 27 Jan (Wed). It sits outside this list.

Scorecard

59 of 100 sits in CAUTION. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse74Unchanged from yesterday. The 10 year index closed at 5.103 percent, down 1.8 basis points from Monday. The level is still not easy
CB Elasticity48Down from 50 yesterday. The 5 year index closed at 4.900 percent, down 3.5 basis points. That is a yield dip in the model, not a policy decision
Flow Pressure72Up from 67 yesterday. The volatility index closed at 25.46, from 22.91. This is the line that lifted the score
Narrative Coherence32Up from 15 yesterday. Tuesday was the fourth straight lower close. The gold fund was not a refuge. The after hours chip print is not in this number
Composite59CAUTION

The label held. Yesterday's score was 54, CAUTION. Today's score is 59, CAUTION. RISK-ON is below 30. RISK-OFF is 61 and above. A higher score means more stress. Five points is not a flip. It is not a reason to cover duration, or to add equity because futures bounced, or to add the crude residual because the settlement rose 70 cents.

Data through the 17 Nov 2026 US close. This is a Wednesday morning note. The score uses Tuesday's volatility index of 25.46 and Tuesday's 10 year index of 5.103 percent.

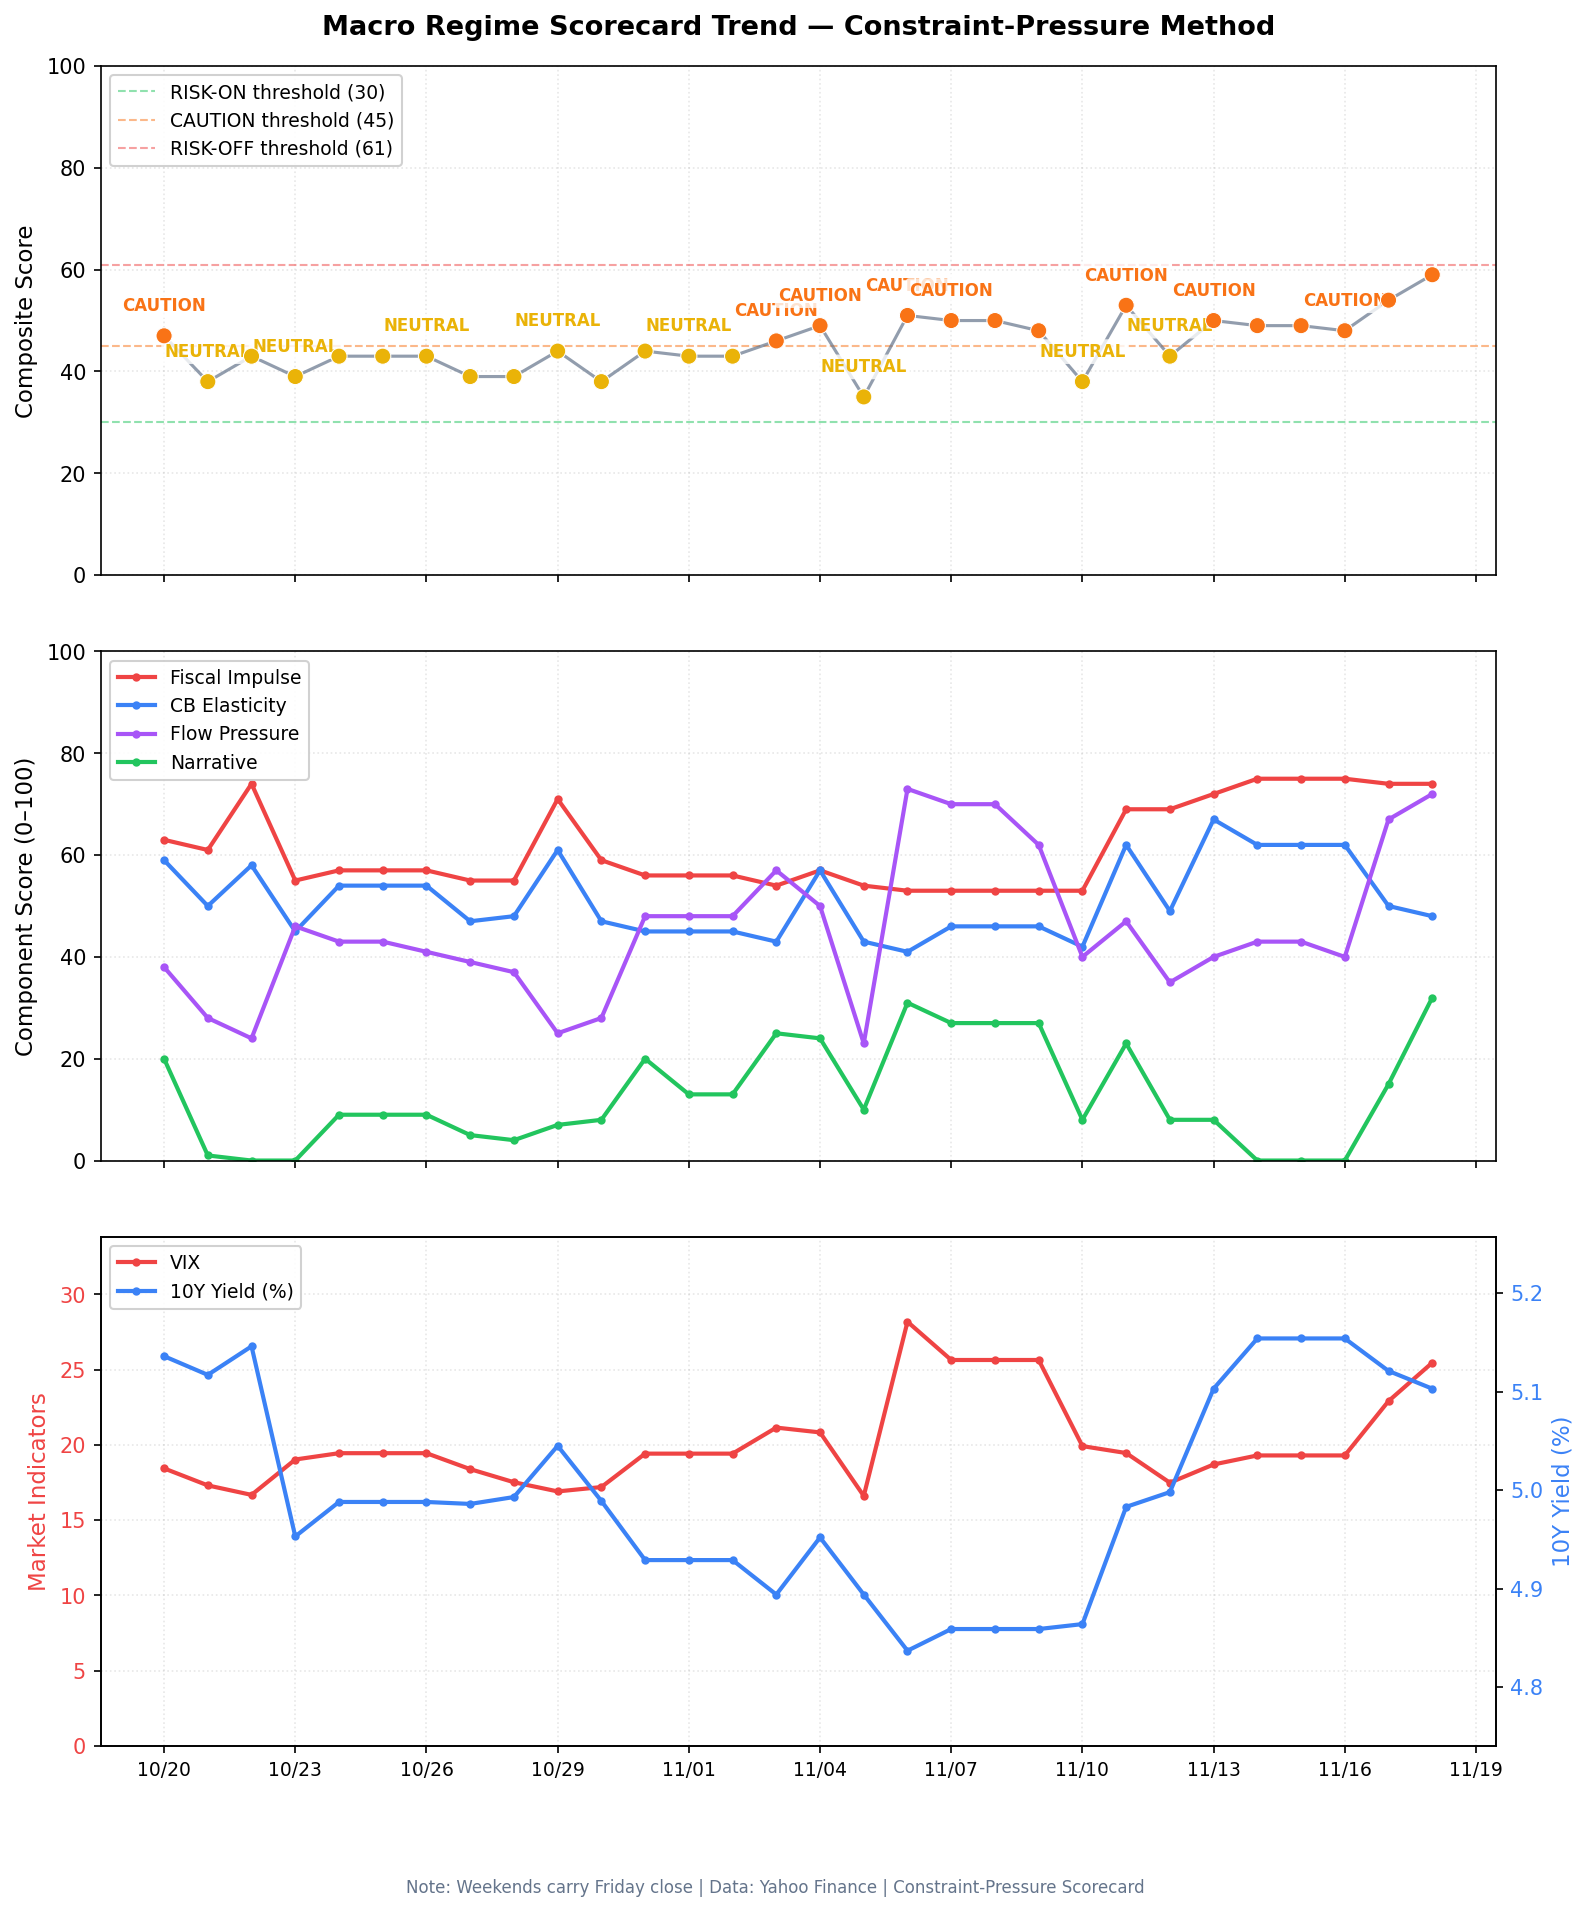
Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.