OverWise

Market regime, October 31

Top five drivers, the risk matrix and the book for Saturday, October 31, 2026.

Not a label flip. The cash close sold the spend. The oil settlement rose. The cheap bar is a roll. Score 44 of 100. The label is NEUTRAL. Yesterday the score was 38. The label was already NEUTRAL. The line for CAUTION is 45. The line for RISK-ON is 30. The line for RISK-OFF is 61. The score rose 6 points. It did not cross 45. It did not cross 30. It is 1 point under the CAUTION line. It is 14 points above the RISK-ON line.

Read the five drivers
Before the US open Next review 1 Nov 2026 (Sun)

Regime score

44of 100

NEUTRAL

1 under CAUTION, 14 over the RISK-ON line

0 to 29 risk-on · 30 to 44 neutral · 45 to 60 caution · 61 and up risk-off

Friday is the last completed US session. This is a Saturday edition after that close. Cash markets are closed. Asia is closed. There is no Saturday settlement. A screen this note does not have is not a close.

What changed is the cash close, and the oil settlement. Thursday was a concentration day, and the open had not happened. Friday was a broader down day. Chips led. More stocks fell than rose. Crude settled at a six month high, on one confirmed strike and an election that has not been held. The continuous bar did not rise. That bar is a different contract. Yields fell again. The hike case did not. Gold's settlement fell. Do not buy the dip. Do not cover the bond. Do not add the crude sleeve. Do not sell it on the roll.

The book versus yesterday is the same book, with a tighter reason to keep it. Hold the crude sleeve. Do not add it because the settlement rose. Do not sell it because a rolled bar is lower. Do not cover duration because yields fell next to a hot rate story. Do not buy chips into a close that already happened, and a weekend that is not a new entry.

In short

MARKET REGIME, Oct 31 (Sat)

Signal. Neutral. Hold energy. Do not chase. Score 44 of 100.

  1. United States Stocks sold off. The spend is the problem.
  2. Iran Oil settled higher. Hold the sleeve.
  3. United States Yields fell. Do not cover the bond.
  4. Gold fell. That dip is not a buy.
  5. United States Tuesday is the vote. Friday is the jobs print.

Markets bar

Friday is the last completed US session. Equity rows are the close story. Yield index rows are that close on this feed. Cash yield rows are the benchmark in the close wrap. Oil rows name the settlement, then the continuous bar. A rolled bar is not a fall in the settlement. A last trade is not a settlement. Gold rows name the December settlement, then the spot prints, then this feed. Those spot prints do not agree. Do not average them.

This note does not cite oil or gold volume as a settlement volume.

For the month, the settlement story has Brent up 13.6 percent and US crude up 15.2 percent. That is October. It is not Friday. Do not trade the month as the day.

Asset Level Change
S&P 500 (Fri close)7,580.07Down 140.32 points, or 1.82 percent, vs Thursday's 7,720.39. Close story. This feed agrees. Do not print a second close
Nasdaq Composite (Fri close)25,437.00Down 747.73 points, or 2.86 percent, vs Thursday's 26,184.72. Close story. This feed agrees. Largest one day drop since 5 June. Do not print a second close
Dow (Fri close)51,770.31Down 572.25 points, or 1.09 percent, vs Thursday's 52,342.56. Close story. This feed agrees
Russell 2000 (Fri close, this feed)2,811.84Down 1.7 percent vs Thursday's 2,859.22. This note has no separate wire print. Do not invent one
VIX (Fri close, this feed)19.42Up 2.22 points vs Thursday's 17.20. The close is under 20. A daytime headline above 20 is not this close. The score uses this close
US 10-year yield index (Fri close)4.929%Down 6.0 basis points vs Thursday's 4.989. This is the index in the score. Not a cash yield
US 10-year benchmark (Fri close)4.931%Down 5.8 basis points, on the close wrap. Not the index. Do not average 4.931 with 4.929
5-year yield index (Fri close)4.721%Down 8.0 basis points vs Thursday's 4.801. Not a cash yield. This note has no Friday cash 5 year
30-year yield index (Fri close)5.309%Down 2.0 basis points vs Thursday's 5.329. Not a cash yield
30-year benchmark (Fri close)5.3093%Down 1.97 basis points, on the close wrap. Do not average with the index
2-year benchmark (Fri close)4.59%Down 6.64 basis points, on the close wrap. This note has no separate Friday cash curve print. Do not invent one
3-month yield index (Fri close)3.973%Down 2.5 basis points vs Thursday's 3.998. Not a cash bill. This note has no Friday cash bill yield
Brent December settlement117.64 dollarsUp 2.76 dollars, or 2.4 percent, from Thursday's 114.88. The December contract expired Friday. Settlement story. One wrap printed 117.63. Do not average. Do not print a second settlement
Brent January settlement113.43 dollarsUp 2.63 dollars on the day. The active contract after expiry. Not 117.64. Not the continuous bar
WTI settlement104.12 dollarsUp 2.12 dollars, or 2.08 percent, from Thursday's 102. The close wrap agrees. One settlement
Brent continuous bar (this feed)112.33 dollarsDown 2.22 percent vs Thursday's 114.88 on this feed. A roll. Not a fall in 117.64. Not January's 113.43. Do not trade it
WTI continuous bar (this feed)102.95 dollarsUp 0.93 percent vs Thursday's 102 on this feed. A last trade. Not the settlement of 104.12. Do not trade it
Dollar index (wire)101.92Up 0.04 percent, on the close wrap. Not this feed
Dollar index (Fri close, this feed)101.96Down 0.07 percent vs this run's Thursday print of 102.04. The sign does not agree with the wire. Do not average 101.92 with 101.96. Do not trade the sign
Gold December settlement3,898.90 dollarsDown 3.3 percent. Settlement story. Not a last trade
Spot gold, 14:13 New York3,880.97 dollarsDown 3.5 percent at that hour. Not the settlement. Not the later wrap
Spot gold, later wrap3,874.58 dollarsDown 3.63 percent in the close wrap. Do not average with 3,880.97
Gold continuous bar (this feed)3,884.90 dollarsDown 3.63 percent vs this feed's Thursday bar of 4,031.40. Not the December settlement of 3,898.90. Do not trade it
Gold fund (Fri close, this feed)355.78Down 3.47 percent vs Thursday's 368.57. The fund is not a futures settlement
Energy fund (Fri close, this feed)70.02Up 1.91 percent vs Thursday's 68.71. An equity close. It rose with the settlement. It does not rewrite 104.12
Oil fund (Fri close, this feed)168.83Up 0.38 percent vs Thursday's 168.19. An equity close. It rose less than the settlement. Do not average
Semiconductor fund (Fri close, this feed)522.49Down 7.0 percent vs Thursday's 561.67. A cash close. The chip index fell 7.2 percent. Different index. Do not average
Long bond fund (Fri close, this feed)81.84Up 0.43 percent vs Thursday's 81.49. A one day bounce. Not a cover
High yield fund (Fri close, this feed)77.43Down 0.19 percent vs Thursday's 77.58. Credit softened. It did not crack
Investment grade fund (Fri close, this feed)104.27Up 0.05 percent vs Thursday's 104.22. Not a crack, and not a new bid

Top five drivers

United States The Cash Close Sold the Spend

The Open Already Happened. Do Not Buy the Dip.

SignalYesterday the rule was not to buy an open that had not printed. The open printed. The close sold the spend. Do not trade Thursday's extended prints as Friday's cash close.

The S&P 500 fell 140.32 points, or 1.82 percent, to 7,580.07. The Nasdaq Composite fell 747.73 points, or 2.86 percent, to 25,437.00. That is the largest one day drop since 5 June. The Nasdaq is down 7.8 percent from its all time closing high on 6 Oct. That 7.8 percent is from the high, not from Thursday. The Dow fell 572.25 points, or 1.09 percent, to 51,770.31. All three indexes finished the week lower. The S&P 500 and the Nasdaq logged monthly losses. The Dow logged a monthly gain. This note has no exact monthly percent for those three indexes. Do not invent one.

Breadth flipped. Decliners led advancers by 1.8 to 1 on the New York Stock Exchange, and by 3.03 to 1 on the Nasdaq. Thursday, advancers had led. The Nasdaq had 70 new highs and 355 new lows. The S&P 500 had 43 new highs and 5 new lows. Volume was 19.87 billion shares, against a 17.26 billion average for the last 20 full sessions. A down index, with more stocks down than up, and with volume above average, is not Thursday's concentration day. It is also not a crash. The S&P 500 new high list did not break. The damage sat in chips and in the Nasdaq new low list.

Intel is the cash close that Thursday's after hours prints could not agree on. The shares fell 28.6 percent. This feed closed at 65.76, from Thursday's 92.07. That is the same 28.6 percent. Do not go back to 18, 21, or 23. Those were not the cash close. The company had already blamed weak PC demand and a factory line. Friday did not split those into a new percent. The cash close is 28.6 percent.

Amazon is the other side of that lesson. Thursday's extended prints were 6.5 percent, 7 percent, and 7.3 percent, and they did not agree. Friday's cash close was down 1.4 percent. This feed closed at 240.35, from Thursday's 243.79. That is the same 1.4 percent. The scare came back. The cash close is not the print after Thursday's close. Do not sell Friday as if it were the extended print, and do not buy it as a clearance of the spend.

Alphabet lost another 1.4 percent, after Thursday's 12.6 percent. This feed closed at 279.84, from Thursday's 283.82. Nvidia fell 4.2 percent. This feed closed at 204.64, from Thursday's 213.66. AMD fell 10.9 percent on the close story. This note has no separate AMD price. Do not invent one. The chip index fell 7.2 percent, and more than 15 percent on the month. The semiconductor fund on this feed fell 7.0 percent, to 522.49. Those are two indexes. Do not average 7.0 with 7.2.

The earnings season did not save the tape. Of 299 S&P 500 companies that have reported, 82 percent have beaten. Expected growth is 31.6 percent, year on year. Thursday's note had 253 companies, 81 percent, and 31.0 percent. Do not mix those counts. A higher beat rate, and a lower close, is the point. The bar is the cash, not the beat.

Exxon rose 2.2 percent. Chevron rose 2.8 percent. That is the energy sleeve inside a down tape. It is not a reason to add it. A crypto theft of 6.3 billion dollars, in the same close story, pulled related shares down between 7.2 percent and 10.6 percent. A theft is not a US close, and it is not a reason to cover the bond or to buy the dip.

Macro ImpactThe question is still whether the spending turns into cash. Friday answered it for the open. It did not answer it for the next report. Buying the chip fund because it fell 7 percent, or because Amazon's cash close was only down 1.4 percent, is how a sold tape becomes the position you have to defend on Monday. Apple reports Monday. That report is not in. A weekend is not an entry.

PositioningDo not buy the semiconductor fund. Do not short it either. The close already happened. The next large report has not. Cash still beats a chase into a market that is closed.

Key SourcesReuters, 30 Oct, https://www.reuters.com/business/nasdaq-futures-tumble-amazon-intel-results-deepen-ai-spending-woes-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/legal/transactional/global-markets-global-markets-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/legal/legalindustry/wall-st-week-ahead-midterm-elections-earnings-jobs-data-loom-ai-wary-market-2026-10-30/
Iran The Settlement Rose

The Roll Fell. One Ship Is Not an Outage.

SignalDo not trade the continuous bar as the settlement. Do not trade one confirmed strike as a lost barrel. Do not trade a returned mediator as a deal.

December Brent expired Friday. It settled up 2.76 dollars, or 2.4 percent, at 117.64 dollars. Thursday's settlement was 114.88 dollars. The 2.76 dollars land on 117.64. One wrap printed 117.63. Do not average those. Do not print a second settlement. January Brent, the active contract, gained 2.63 dollars, to 113.43 dollars. That is not 117.64.

US crude settled up 2.12 dollars, or 2.08 percent, at 104.12 dollars. Thursday's settlement was 102 dollars. The 2.12 dollars land on 104.12. The close wrap agrees. For October, Brent finished 13.6 percent higher and US crude finished 15.2 percent higher. That is the month. The day is 2.4 percent and 2.08 percent. The settlement story calls these six month highs, the highest since the end of April.

The continuous bar is the trap. On this feed, the Brent bar closed at 112.33 dollars, down 2.22 percent from Thursday's 114.88. That is not a fall in 117.64. It is not January's 113.43 either. It is 1.10 dollars under the January settlement. The US crude bar on this feed closed at 102.95 dollars. That is 1.17 dollars under the settlement of 104.12. A last trade is not a settlement. Do not trade 112.33. Do not trade 102.95.

The confirmed strike is one ship. A small boat attached two limpet mines to a tanker in the strait. The engine room caught fire. The ship was temporarily disabled. The crew was safe. There was no environmental impact. The fire was out. The ship continued to its next port. The British maritime desk put the incident on Thursday, 25 nautical miles northeast of Khasab. Security sources named the ship. This is the first known successful limpet strike in the waterway since the war began in February. A ship that kept sailing is not a lost cargo. Yesterday's mine count was not one number, and it was not this confirmation. Do not merge them. Do not upgrade one ship into an outage.

The rest is still not a settlement. Mediators returned to Tehran. A return is not a deal. Iran has the vice president's letter and has not answered it. The embassy told non emergency staff to leave Saudi Arabia. The order was effective 23 Oct. A departure order is not a lost refinery. Thursday's refinery claim still has no Saudi confirmation of an outage in this note. There is still no strike order. The oil story says traders braced for an escalation after Tuesday's vote. A brace is not an order.

Macro ImpactYesterday the trap was a lower settlement and a higher screen. Today the settlement is higher, and the cheap bar is a roll. Selling the sleeve because 112.33 is under 117.64 is how you give back the hedge into a strait that is not open. Adding the sleeve because the settlement jumped 2.4 percent, into a weekend, on one ship that kept sailing, is how you buy an election that has not been held.

PositioningHold the crude sleeve. Do not add it. Do not sell it. Do not trade 112.33 as the settlement. Do not trade 102.95 as the settlement. No airlines and no transports. The energy fund rose 1.91 percent while the settlement rose 2.08 percent. That close is not a reason to add the fund, and it is not a reason to sell the sleeve.

Key SourcesReuters, 30 Oct, https://www.reuters.com/business/energy/oil-rises-supply-concerns-houthis-attack-saudi-arabia-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/world/tanker-strait-hormuz-hit-by-limpet-mines-security-sources-say-2026-10-30/ ; Reuters, 29 Oct, https://www.reuters.com/business/energy/us-oil-prices-fall-investors-gauge-risks-mideast-supply-2026-10-29/

United States Yields Fell

The Hike Case Did Not. Do Not Cover.

SignalThe long end rallied again. The officials who spoke on Friday asked for more hikes, not fewer. Do not trade the rally as a pivot.

The benchmark 10 year yield fell 5.8 basis points, to 4.931 percent. The 30 year fell 1.97 basis points, to 5.3093 percent. The 2 year fell 6.64 basis points, to 4.59 percent. The yield index in the score closed at 4.929 percent, down 6.0 basis points from 4.989. The 5 year index closed at 4.721 percent, down 8.0 basis points from 4.801. The 30 year index closed at 5.309 percent. These are two curves. Do not average 4.931 with 4.929. This note has no Friday par curve print. Do not invent one from Thursday's curve.

The labor cost print did not ease the case, and it did not make a new one. Employment costs rose 0.8 percent in the third quarter, in line, after 0.9 percent. Over the year they rose 3.4 percent, the same as through June. Wages rose 0.7 percent in the quarter and 3.1 percent on the year. Benefits rose 0.9 percent in the quarter and 3.9 percent on the year. Wages adjusted for inflation fell 0.6 percent over the year through September. The wage bill is not the inflation shock. Oil and the spend are. A cooler wage print next to 3.6 percent inflation, from Thursday, is not a cover.

The hold is already in. The target range is 3.75 percent to 4 percent. On Friday a voter said the committee needs at least two more quarter point increases, then a pause. A non voter said more firming is necessary, and soon, and that policy is still accommodative. A third said the direction is straightforward and the question is pace. Two officials had dissented for a hike on Wednesday. Neither filed a written reason on Friday. The chair did not say what the December meeting will do. That meeting is 8 Dec and 9 Dec. Futures odds of a December hike eased. The wrap gave no new percent. An increase is still more likely than a hold, on that wrap. Do not invent a percent. Do not reuse Thursday's figures as Friday's.

December gold settled 3.3 percent lower, at 3,898.90 dollars an ounce. That is the settlement. Spot at 14:13 in New York was 3,880.97 dollars, down 3.5 percent. A later wrap printed 3,874.58 dollars, down 3.63 percent. Do not average the two spots. This feed's continuous bar closed at 3,884.90 dollars, 14 dollars under the settlement. Do not trade 3,884.90. The gold fund fell 3.47 percent, to 355.78. Silver slid under 50 dollars an ounce. The wrap printed 49.06. Gold's fall is the rate story, not a war bid. The war hedge is still crude.

The dollar is not a signal. The wrap had the index up 0.04 percent, at 101.92. This feed closed at 101.96, down 0.07 percent from this run's Thursday print of 102.04. The sign does not agree. Do not average. Do not trade it.

Macro ImpactA flight from the spend pulled yields down. It did not pull the hike case down. Covering the short because the 10 year benchmark fell 5.8 basis points is how you buy a bond into a December meeting that is still a hike meeting, and into officials who asked for more. Adding to the short because the data were not soft, after the yield has already fallen, is a chase into a market that is closed. The long bond fund rose 0.43 percent. That is the close. It is not a new entry.

PositioningStay underweight long duration. Do not cover. Do not add to the short into a closed weekend, or into Friday's labor print. Hold cash and short bills over the long end. Do not buy the gold dip. A zero weight in gold is fine. If you want the war hedge, it is the crude sleeve, and that sleeve is not a new trade today.

Key SourcesReuters, 30 Oct, https://www.reuters.com/legal/transactional/global-markets-global-markets-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/business/feds-musalem-says-rate-hike-is-needed-soon-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/business/us-labor-costs-rise-moderately-third-quarter-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/world/india/gold-slips-higher-oil-us-inflation-data-bolster-fed-hike-bets-2026-10-30/ ; Federal Reserve calendar, December 8 to 9, 2026

The Score Rose to 44

The Label Did Not Flip. Do Not Add Because You Have Not Crossed.

SignalFriday's close did not flip the regime. A higher score is not a sell signal one point under the line. A volatility index at 19.42 is not a crash, and it is not an all clear.

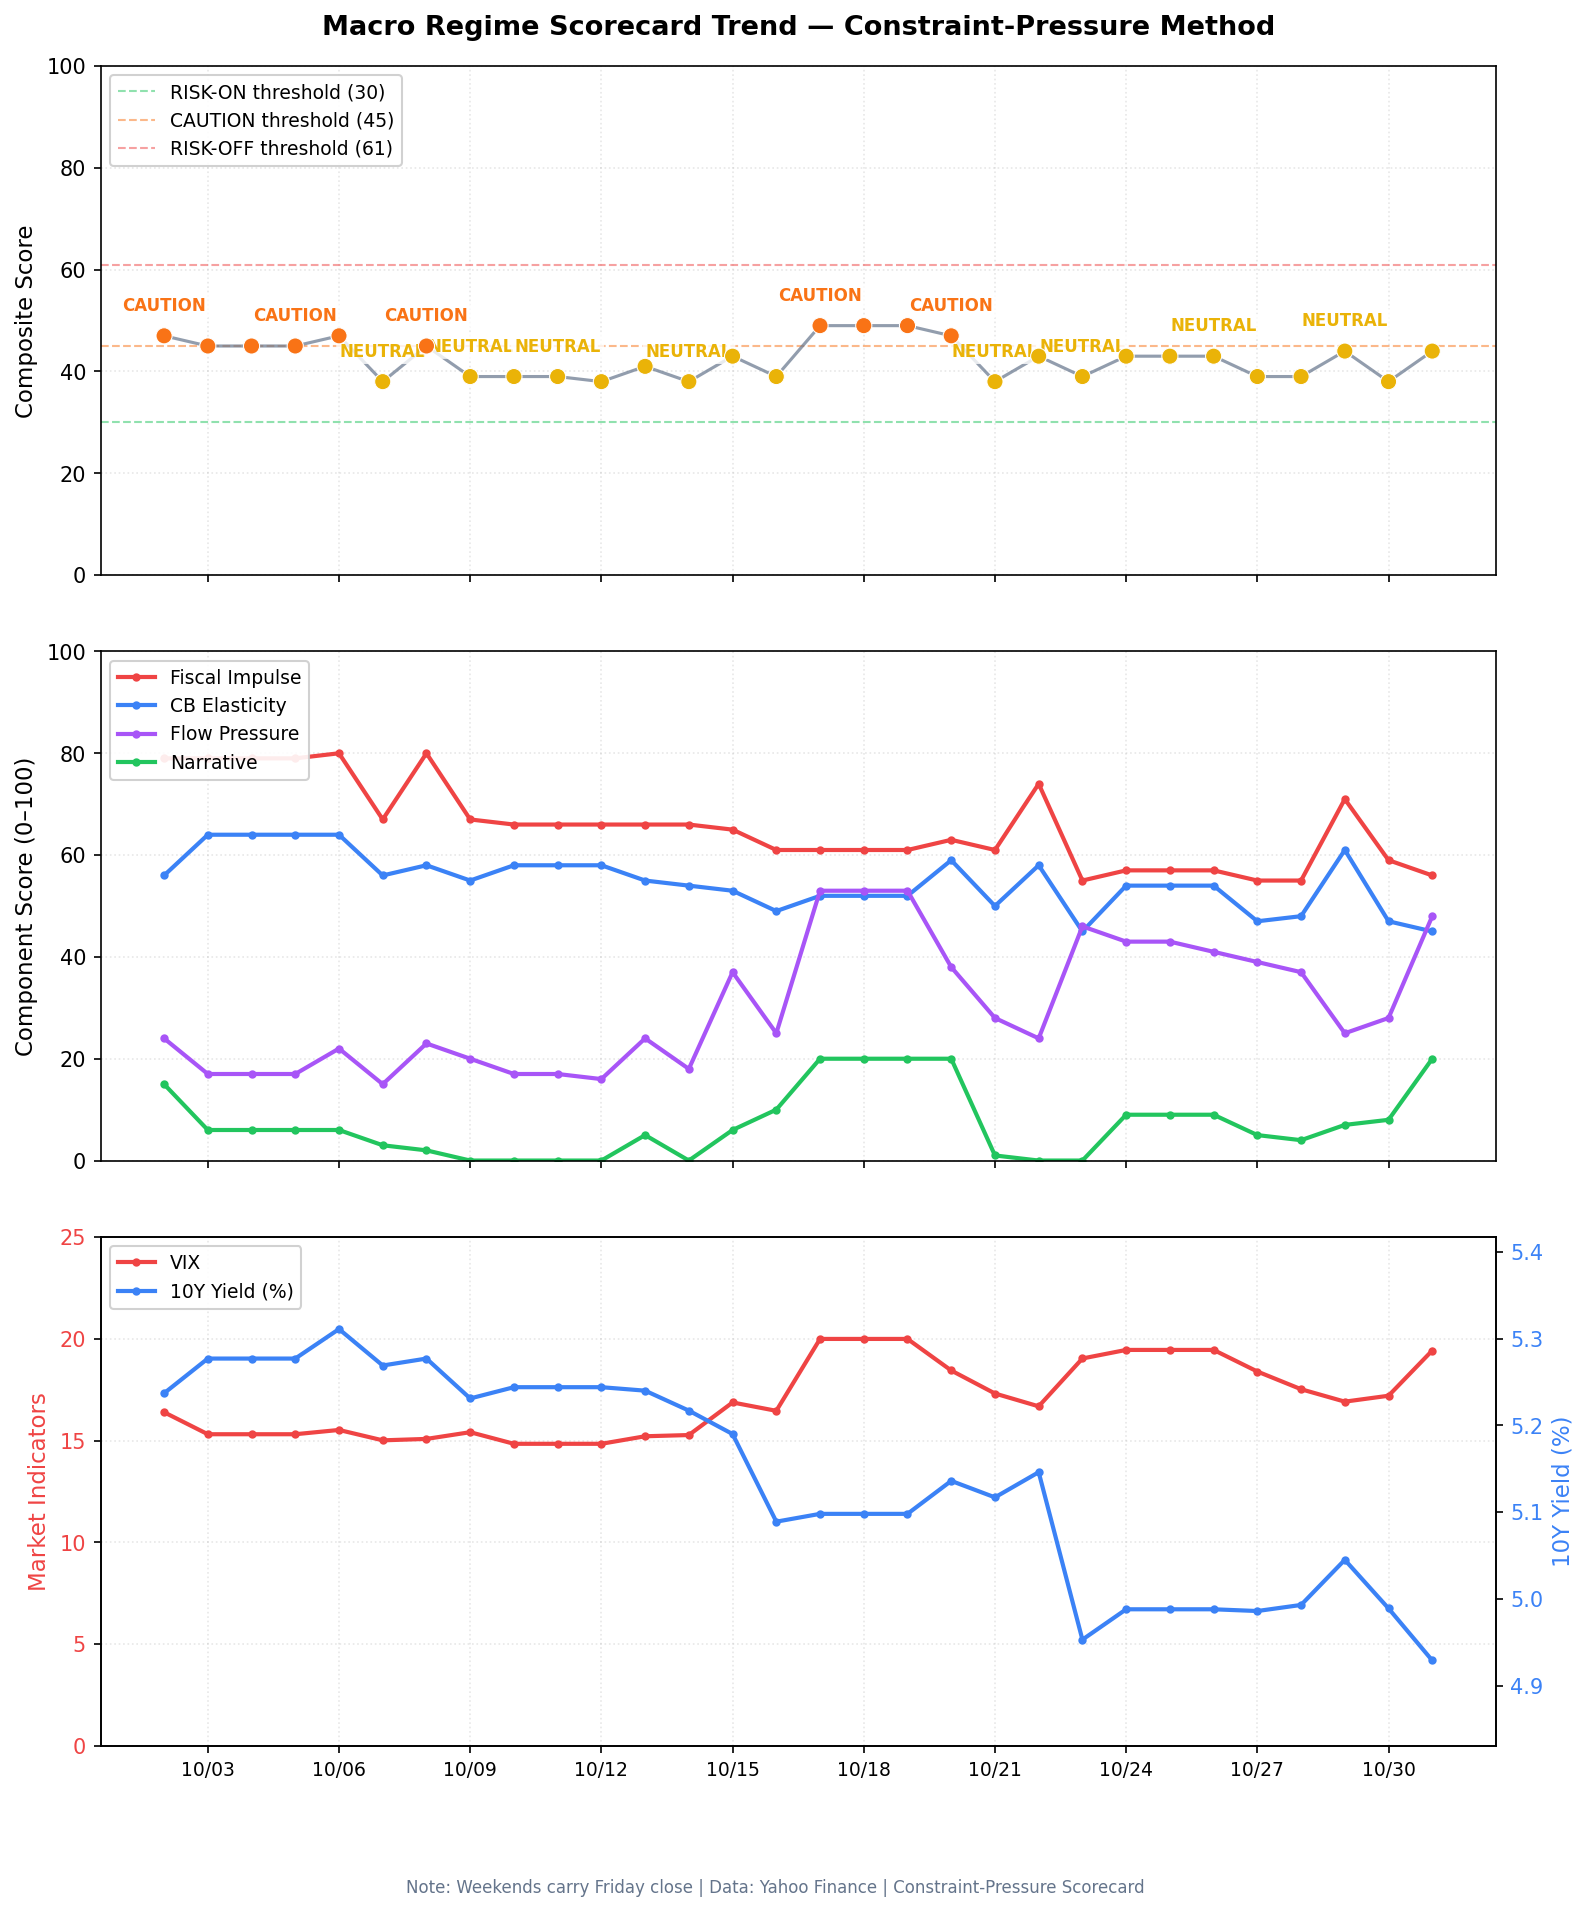
The score is 44. Yesterday's score was 38. Fiscal pressure is 56, down 3 points. Central bank pressure is 45, down 2 points. Flow pressure is 48, up 20 points. Narrative stress is 20, up 12 points. The volatility index in the score is Friday's 19.42. The yield index in the score is Friday's 4.929 percent. A Saturday screen is not in the score. There is no Saturday settlement in the score.

The high yield fund fell 0.19 percent. The investment grade fund rose 0.05 percent. Credit did not crack. That is not a reason to add risk 1 point under the CAUTION line, with a strait that is not open and a vote that has not been held.

Macro ImpactA score that rises 6 points and stops 1 point under CAUTION is a hold, not a signal. Flow pressure rose because the volatility index rose from 17.20 to 19.42. Narrative stress rose because the story broke. Stocks fell. Oil settled higher. Yields fell. Gold settled lower. Fiscal pressure eased because the yield index fell. The score rose on the stock scare, not on a bond all clear. Treating 44 as a buy because it did not cross 45 is how you add risk into a close that already sold the spend. Treating 44 as a flip is how you sell a book that has not changed its label.

PositioningDo not add risk because the label is still NEUTRAL. Do not cut risk because the score rose. The sleeve you had yesterday is the sleeve you should still have. The reason to keep it got tighter, not looser.

Key SourcesReuters, 30 Oct, https://www.reuters.com/business/nasdaq-futures-tumble-amazon-intel-results-deepen-ai-spending-woes-2026-10-30/ ; Reuters, 30 Oct, https://www.reuters.com/legal/transactional/global-markets-global-markets-2026-10-30/

United States The Vote Is Tuesday

The Jobs Print Is Friday. A Weekend Is Not a Close.

SignalThe next settlement is not a Saturday screen. It is a vote, then a labor print, then prices. Do not trade a calendar as a close.

Tuesday 3 Nov is the US midterm election. The oil story says traders are braced for an escalation after that vote. A brace is not an order. A poll is not a settlement. The same day, at 10:00 in New York, the bureau prints September job openings. An openings print is not the employment situation.

Friday 6 Nov, at 08:30 in New York, is the October employment situation. The labor print is not in. Claims were low as of Thursday's note. Do not cover before the print, and do not fade it from a forecast.

Tuesday 10 Nov, at 08:30 in New York, is the October consumer price index. September's gauge was hot. This print is not in. Do not trade a forecast. Friday 13 Nov, at 08:30, is the producer price index. That print is not in either.

Apple reports on Monday. Several other large reports sit in the same week. This note does not assign those other days. A report that has not printed is not a reason to buy Friday's dip, and it is not a reason to short a closed market.

The December policy meeting sits beyond this two week list. It is 8 Dec and 9 Dec. It is still the hike meeting. Friday's wrap said the odds eased, and that an increase is still more likely than a hold. It gave no new percent. Do not invent one.

Macro ImpactKorea's Friday morning print is already behind us. It was not a US close then, and it is not one now. The spending is still the question. The cash close sold it. The next test is a vote, a jobs print, and the reports that have not printed. Selling the weekend as if it were a new close is the same error as buying it.

PositioningStay underweight China cyclicals. No new policy figure in this note. Do not use a closed Asia session as a proxy. Do not sell Friday's close again on Saturday. Do not buy it. The sleeve is unchanged until the vote and the labor print say otherwise.

Key SourcesReuters, 30 Oct, https://www.reuters.com/legal/legalindustry/wall-st-week-ahead-midterm-elections-earnings-jobs-data-loom-ai-wary-market-2026-10-30/ ; Bureau of Labor Statistics release calendar, November 2026 ; Federal Reserve calendar, December 8 to 9, 2026

Risk matrix

Factor Direction Conviction Horizon Δ vs yesterday
Regime scoreStill NEUTRALHighDays↗ 44. Yesterday was 38. Did not cross 45. Did not cross 30. One point under the line. A closed weekend is not in the score
Brent settlementHigherHighDays↗ December settled at 117.64 dollars, up 2.76 dollars from Thursday's 114.88. Expired Friday. Not the January contract. Not the continuous bar
WTI settlementHigherHighDays↗ Settled at 104.12 dollars, up 2.12 dollars from Thursday's 102. Not a last trade at 102.95
Contract rollDo not trade itHighDays↔ This feed's Brent bar, at 112.33 dollars, is not a fall in 117.64. It is not January's 113.43. Do not trade it
HormuzOne ship, not an outageHighDays↗ One tanker, limpet mines, crew safe, no spill, ship continued. Not a lost cargo. Not yesterday's unconfirmed count
StraitNot openHighDays↔ Mediators returned. A return is not a deal. An unanswered letter is not an opening
Strike clockBrace, not an orderHighDays↗ Traders braced for after the vote. A brace is not a strike
Fed pathHold done, December is the riskHigh1 to 3 mo↘ Odds eased. No new percent in this note. An increase is still more likely than a hold. Do not invent the percent
US 10 year benchmarkLower for a dayHigh1 to 3 mo↘ 4.931 percent, down 5.8 basis points. Not the index
US 10 year indexLower for a dayHigh1 to 3 mo↘ Score uses 4.929 percent, down 6.0 basis points. Do not average with 4.931
Labor costsCooler, not a coverHigh1 to 3 mo↔ Costs up 0.8 percent in the quarter, 3.4 percent on the year. Real wages down 0.6 percent. Not a pivot
DollarWires disagreeLowDays↔ Wrap 101.92, up 0.04 percent. This feed 101.96, down 0.07 percent. Do not average. Do not trade the sign
NasdaqLower in cashHighDays↘ Down 2.86 percent to 25,437.00. The open already happened. Not an entry
S&P 500LowerHighDays↘ Down 1.82 percent to 7,580.07. Broader than Thursday. Not a crash
BreadthMore stocks down than upHighDays↘ Decliners led. Thursday, advancers had led. Nasdaq new lows expanded. S&P new highs still led new lows
GoldSettlement lowerHighDays↘ December settled at 3,898.90 dollars, down 3.3 percent. Not the continuous bar. Not a new entry
ChipsLower in cashHighDays↘ Chip index down 7.2 percent. The fund on this feed down 7.0 percent. Do not average. Do not chase

Portfolio

Sleeve Stance Rationale
CrudeHold. Do not add. Do not sellSettlement higher, continuous bar lower, one ship kept sailing, letter not a deal. The sleeve is the hedge. It is not a new trade
Energy equitiesHold with the sleeve. Do not addThe fund rose 1.91 percent with the settlement. That close does not rewrite 104.12, and it is not a reason to add into the vote
Long durationUnderweight. Do not coverBenchmark 10 year at 4.931 percent for one day. Officials asked for more hikes. December is still the hike meeting. Do not add to the short into a closed weekend
Cash and short billsOverweight versus the long endPaid to wait through the vote and Friday's labor print. This note has no Friday cash bill yield. Do not invent a reason to extend
SemiconductorsDo not chase. Do not shortCash close sold the spend. The next large report is Monday. A closed market is not an entry
GoldNo new entryDecember settlement down 3.3 percent. The fall is the rate story. The war hedge is crude, and crude is not a new trade
Airlines and transportsNoThe settlement rose. One ship is not an opening. A weekend is not a fare trade
China cyclicalsUnderweightNo new policy figure. Do not use a closed session as a proxy
Broad equityDo not addThe cash close was a broader down day. The vote has not been held. The labor print is not in

The next two weeks

Date Event Why it matters
2 Nov (Mon)Apple reportsThe close already sold the spend. This report is not in. Do not buy Friday's dip into it, and do not short a closed market for it
3 Nov (Tue)US midterm electionsThe strike brace is tied to after this vote. A brace is not an order. Do not trade the polls as a settlement
3 Nov (Tue)Job openings, September, 10:00 New YorkAn openings print is not the employment situation. Do not trade it as Friday's labor print
5 Nov (Thu)Productivity and costs, third quarter, 08:30 New YorkA preliminary print. Not the labor print. Not a reason to cover early
6 Nov (Fri)October employment situation, 08:30 New YorkThe labor print is not in. Do not cover before it, and do not fade it from a forecast
10 Nov (Tue)October consumer prices, 08:30 New YorkSeptember's gauge was hot. This print is not in. Do not trade a forecast
11 Nov (Wed)Veterans Day, bureau holidayThe bureau is closed. Do not expect a price print
13 Nov (Fri)October producer prices, 08:30 New YorkNot in. Do not trade a forecast. Sits at the edge of this two week list

The December policy meeting sits beyond this two week list. It is 8 Dec (Tue) and 9 Dec (Wed). It is still the hike meeting. Friday's wrap said hike odds eased, and that an increase is still more likely than a hold. It gave no new percent. Do not invent one. Do not cover before the labor print that sits in front of it.

Scorecard

44 of 100 sits in NEUTRAL. Caution starts at 45, risk-off at 61, risk-on below 30.

Variable Score Interpretation
Fiscal Impulse56Down 3 points from 59. The yield index closed at 4.929 percent, down 6.0 basis points. The day eased. The level is still not easy. Still not a bond bid
CB Elasticity45Down 2 points from 47. The 5 year index fell 8.0 basis points, to 4.721. The belly eased for a day. December is still a hike meeting. Do not read 45 as a cut
Flow Pressure48Up 20 points from 28. The volatility index closed at 19.42, up 2.22 points. The close is under 20. The high yield fund fell 0.19 percent. More stress. Not a crack
Narrative Coherence20Up 12 points from 8. Stocks fell, oil settled higher, yields fell, gold settled lower. The story broke. The score took the break. Higher stress is not a buy signal, and it is not a flip
Composite44NEUTRAL

The label did not flip. The score is 44. Yesterday it was 38. The line for CAUTION is 45. The line for RISK-ON is 30. The line for RISK-OFF is 61. A higher score means more stress. This score rose 6 points. It did not cross 45. It did not cross 30. It is 1 point from CAUTION and 14 points from RISK-ON, with a settlement that rose, a roll that is not a fall, and a vote that has not been held. A 44 going into that calendar is a hold, not a signal.

Data through the 30 Oct 2026 US close. This is a Saturday edition after that close. Cash markets are closed. There is no Saturday settlement.

Score trend, thirty days

Macro regime composite score, last thirty days, with the neutral and caution lines
One point a day. The composite is the same four components, weighted the same way, thirty days back.