🌍 Market Regime — August 28, 2026
August 28, 2026 · Top 5 regime drivers, risk matrix, positioning
 Fed Chair Warsh speaks at Jackson Hole today. Three officials already warned on inflation this week. Markets watching for a hawkish signal three weeks before the September Fed meeting. Nvidia surged 8.7 percent yesterday after earnings beat forecasts. The stock rose from $209 to $228. AI capex demand remains very strong.
 Trump rejected reviving the Iran ceasefire. Oil rose with Brent up 2 percent to $88. The Hormuz shipping route remains disrupted. No deal in sight.
 China's recovery is losing momentum. Multiple reports this week show weaker output and consumption. US is also pressing Chinese banks over Iran sanctions. July payrolls fell 23,000, the first decline in months. The headline looks weak even if the full picture is mixed. August data due September 4 will clarify.
Markets: S&P 7731 (+0.72%) | VIX 14.51 (-4.6%) | 10Y 4.672% | Brent $88.26 (+1.98%) | WTI $83.17 (+1.63%) | Gold $4634 (-0.94%) | DXY 99.16
Weekend edition using Friday 27 Aug US close data. Markets are closed Saturday/Sunday.
Top 5 Regime Drivers
1. Fed Chair Warsh Jackson Hole Speech — TODAY
Signal: Fed Chair Kevin Warsh delivers his first major keynote at the Jackson Hole symposium on Friday, August 28 — just three weeks before the September FOMC. Three Fed officials already went public this week with inflation warnings ahead of the speech, raising expectations that Warsh will echo a hawkish tone. CME FedWatch shows a 25bp September hike priced at roughly one-in-three odds, with the bar for a hold described as "low." The 10Y yield has stabilized near 4.67% after trading in a 4.64-4.74% range all week.
Macro Impact: If Warsh signals a willingness to hike in September despite market pricing, duration gets hit and the dollar strengthens. A more cautious tone would be risk-on for equities and bonds. Either way, the speech is the single highest-conviction catalyst of the week.
Positioning: Flat duration heading into the speech. Long dollar vs EUR and EM currencies on hawkish surprise. Watch 4.75% on 10Y as a break higher that would confirm the hawks are winning.
Key Sources: Reuters Aug 27, CNBC Aug 27, Yahoo Finance Aug 25
2. Nvidia Q2 Fiscal 2027 Earnings — Yesterday
Signal: Nvidia reported Q2 fiscal 2027 results on Wednesday August 26 after market close. EPS came in at $2.22, beating the $2.09 consensus estimate by 6.2%. Guidance also surpassed analyst forecasts. The stock surged 8.7% on Thursday August 27, rising from $209.66 to $227.98 — the biggest one-day gain in months. The AI capex narrative remains fully intact despite valuation concerns.
Macro Impact: Nvidia's beat keeps the AI infrastructure theme alive and supports the broader tech sector. It also underpins the argument that AI demand is real and accelerating, which has been a key support for equity valuations broadly. However, big-tech capex of $650B+ annually is also cited as a fiscal inflationary pressure.
Positioning: Overweight semiconductors and AI infrastructure (NVDA, AMD). The VIX declining to 14.51 despite the Iran/oil backdrop suggests equities are not in fear mode — the Nasdaq strength is pulling the market higher.
Key Sources: CNBC Aug 26, MarketBeat Aug 27, Public.com Aug 27
3. Iran Ceasefire Collapses / Hormuz Tensions Elevated
Signal: On Thursday August 27, Trump publicly rejected a return to the Iran ceasefire memorandum, pushing oil prices higher. Brent rose 1.98% to $88.26 and WTI gained 1.63% to $83.17. The rejection means the June ceasefire has effectively expired with no revival. Six months into the US-Iran war, regional supply remains constrained and talks are at a standstill per Politico. A Reuters poll showed analysts cutting 2026 oil price forecasts for the first time since the war began — but near-term Hormuz uncertainty is still keeping a floor under prices.
Macro Impact: Oil is up from the mid-$80s two weeks ago to current levels, which reprices the inflation outlook. If Brent holds $88+ into September, the Fed faces persistent energy-driven headline inflation on top of sticky services CPI. This makes the rate decision harder.
Positioning: Overweight energy (XLE). WTI $85+ level is a threshold that historically creates consumer spending headwinds. Watch whether $90 on Brent triggers demand destruction calls.
Key Sources: Reuters Aug 27, CNBC TV18 Aug 27, Politico Aug 27, BGNES Aug 24
4. China Recovery Stalling
Signal: Multiple reports this week highlighted China's economic recovery losing momentum. Reuters noted consumption and output losing steam. The Guardian flagged that the slowdown may be extending rather than bottoming. US Treasury is pressing Chinese banks over Iran-related sanctions exposure, and Trump threatened broader China trade measures as part of the Iran strategy — testing the US-China detente. Deloitte's weekly economics summary confirmed a broad weakening trend.
Macro Impact: A China slowdown means weaker EM demand, lower commodity prices, and reduced risk appetite globally. The linkage to oil is complex — China weakness could cap oil demand, offsetting the Iran supply premium. For US markets, China deceleration adds a global growth worry but also takes pressure off the dollar from a growth differential standpoint.
Positioning: Underweight China-adjacent EM (KWEB, FXI). Long gold as a hedge on China/EM stress. Watch copper as a leading indicator.
Key Sources: Reuters Aug 2026, The Guardian, Politico, Al Jazeera
5. US Labor Market Deterioration — July Payrolls Miss
Signal: July US payrolls came in at -23,000, the first negative print in months and well below the +150,000 consensus. The unemployment rate fell but only because of declining labor force participation. Prior months saw significant downward revisions. This stands in contrast to the June record-high payrolls headline and creates a confusing picture — either the labor market is weakening faster than the headline suggests, or the July reading is an anomaly.
Macro Impact: Weak payrolls argue against a Fed rate hike — the dual mandate has an employment component. But with CPI still running above target (July CPI +3.7% per Al Jazeera), the Fed faces a stagflationary dilemma: hike to fight inflation or cut to support employment. The tension between these two is the defining macro conflict of the month.
Positioning: Neutral equities — the payrolls miss and the inflation/war premium are pulling in opposite directions. Long gold and long duration on a relative basis. Watch August payrolls (due early September) as the decisive data point.
Key Sources: CNBC July, NBC News July, QZ July, Illinois.gov July
Summary Risk Matrix
| Factor | Direction | Conviction | Horizon | Δ vs Yesterday |
|---|---|---|---|---|
| Fed rate path (Sept) | Hawkish tilt ↑ | Medium | 3 weeks | Stable |
| Jackson Hole speech | Hawkish signal ↑ | High | Today | New |
| Iran/Hormuz oil premium | Oil up ↑ | High | 1-4 weeks | +$3/bbl Iran premium |
| China growth | Slowing ↓ | Medium | Monthly | Weakening |
| US labor market | Weakening ↓ | Medium | Monthly data | Payrolls miss |
| NVDA/AI capex narrative | Bullish ↑ | High | Earnings season | Beat +8.7% yesterday |
| Global risk appetite | Mixed ⟳ | Medium | Daily | VIX fell to 14.51 |
Portfolio Construction
| Position | Direction | Rationale |
|---|---|---|
| Semiconductors (NVDA, AMD) | Overweight | AI capex cycle intact, NVDA beat confirms demand |
| Energy (XLE) | Overweight | Iran tensions underpin $83+ WTI floor |
| Gold | Overweight | China/EM stress + dollar neutral = safe haven bid |
| US duration | Neutral | Jackson Hole today — wait for clarity on 10Y break |
| EM equities | Underweight | China slowdown + dollar strength risk |
| Dollar (DXY) | Neutral/slight long | Hawkish Fed + weak EM = dollar support |
Key Events / Watchlist — Next 2 Weeks
| Date | Event | Importance |
|---|---|---|
| 28 Aug (Fri) | Warsh Jackson Hole keynote | 🔴 HIGH |
| 28 Aug (Fri) | NVDA post-earnings analyst day | 🟡 Medium |
| 4 Sep (Fri) | August US payrolls report | 🔴 HIGH |
| 8 Sep (Tue) | Bank of Japan policy decision | 🟡 Medium |
| 16-17 Sep | September FOMC meeting | 🔴 HIGH |
| 25 Sep (Fri) | Q2 US GDP revision | 🟡 Medium |
Regime Scorecard
Data through 27 Aug 2026 US close (08:10 CEST live scorecard update).
| Variable | Score | Interpretation |
|---|---|---|
| Fiscal Impulse | 50 | 10Y at 4.67% — moderately restrictive, trending easier from 4.74% Monday |
| CB Elasticity | 42 | 5Y at 4.40% — below neutral, Fed constrained by inflation above target |
| Flow Pressure | 13 | VIX 14.5 (-4.6%) — lowest reading in weeks, low fear despite Iran/oil |
| Narrative Coherence | 2 | SPY +0.7%/5d; QQQ-SPY breadth +7; NVDA drove most of Thursday's gain |
| Composite | 29 | RISK-ON |
Regime thresholds: <30 RISK-ON | 30-44 NEUTRAL | 45-60 FÖRSIKTIGHET | ≥61 RISK-OFF
The scorecard registers RISK-ON — VIX at 14.51 is the lowest reading in weeks, and the 10Y has eased from 4.74% to 4.67%. The main tension is between hawkish Fed (Jackson Hole today) and a market that is not pricing in much hiking risk. A Warsh hawkish surprise could push the 10Y above 4.75% and flip the scorecard toward NEUTRAL.
Score Trend (30 days)
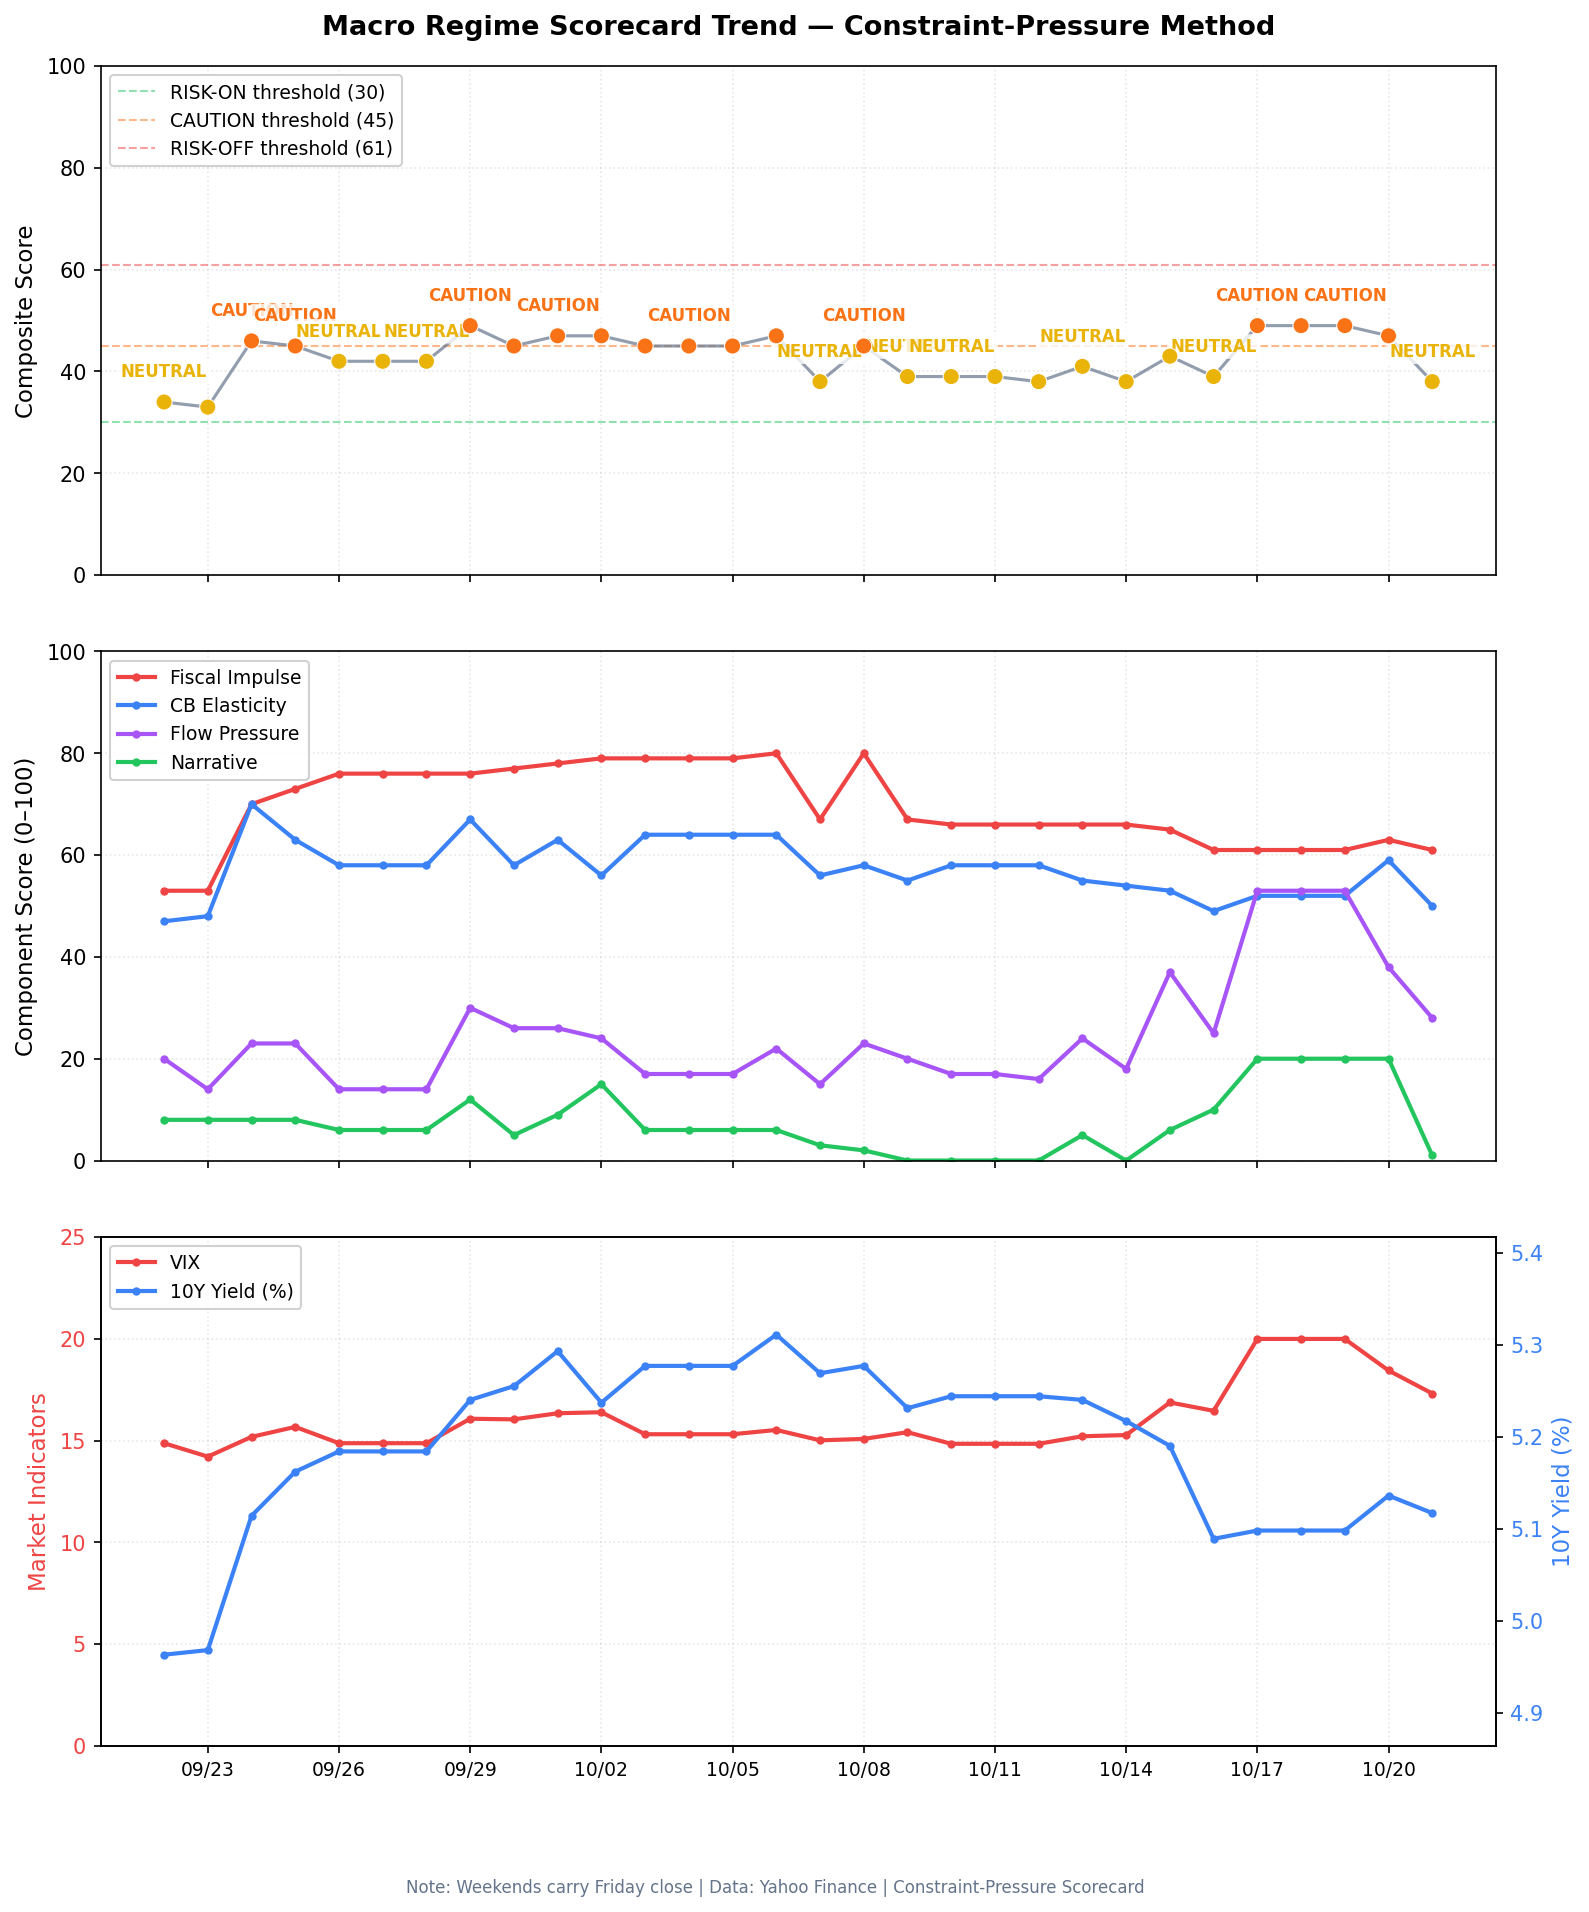
Generated
28 Aug 2026 08:10 CEST (live scorecard update) | Next full review: Monday 31 Aug 2026